

Frasers Centrepoint Trust manager bullish on leasing demand even as H1 DPU slips 0.1% to S$0.0613
FRASERS Centrepoint Trust ’s (FCT) distribution per unit (DPU) inched down 0.1 per cent to S$0.0613 for the first half ended Mar 31, from S$0.06136 the year before.
The retail real estate investment trust’s (Reit) gross revenue and net property income (NPI) improved. However, property expenses were higher year on year, financial results released on Wednesday (Apr 26) showed.
Committed occupancy for the Reit’s retail portfolio hit a high of 99.2 per cent in the first half. Century Square’s occupancy grew to 96.8 per cent from 88.7 per cent, after the manager secured lease commitment for the property’s anchor cinema space.
“The headline occupancy is really a testament that we have very strong demand,” said Richard Ng, CEO of FCT’s manager, at a media briefing accompanying the results announcement. “Prime retail space is one where retailers are very focused on over the course of the pandemic, and also partly because of the increase in costs, there is a flight towards quality.”
The real estate investment trust (Reit) manager noted that its asset enhancement initiative (AEI) at Tampines 1, scheduled to complete in the third quarter of 2024, is also showing strong leasing traction.
“The 90 per cent pre-commitment to our AEI at Tampines 1 (achieved prior the works commencement), again, is a testament that we have very strong demand,” Ng said.
For the six months ended Mar 31, gross revenue was up 6.5 per cent to S$187.6 million from S$176.2 million in the year-ago period on the back of higher occupancy, stronger turnover rents, and positive rental reversion for new and renewed leases. Atrium income also rose as events resumed on Mar 29, 2022.
NPI grew 5.7 per cent on year to S$138 million for the half year, from S$130.5 million.
Distributable income increased 0.3 per cent to S$104.7 million, from S$104.4 million in the same period a year ago. The manager had retained S$3 million in tax-exempt income available for distribution to unitholders, but released S$1.7 million of income available for distribution previously retained in H2 2022.
The distribution will be paid out on May 30, after books closure on May 5.
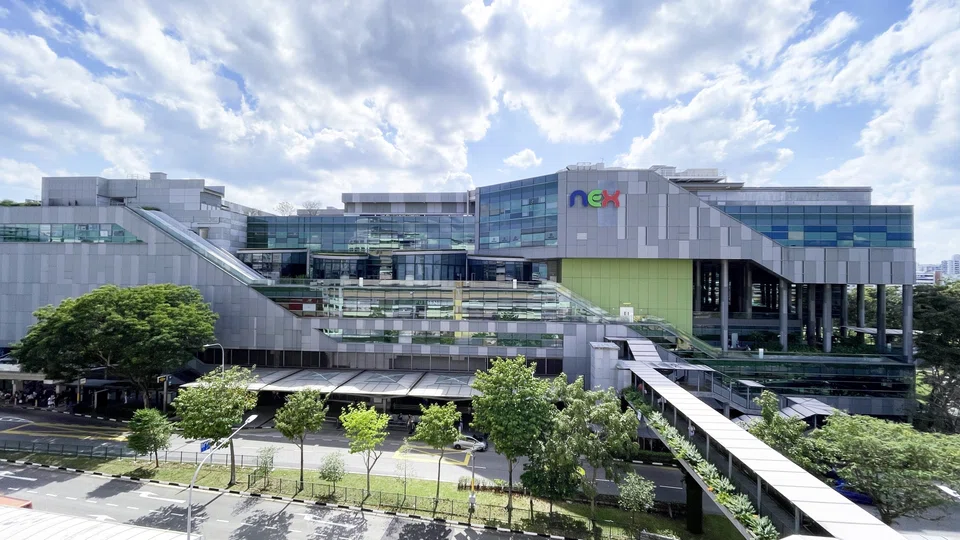
FCT’s aggregate leverage stood at 39.6 per cent as at Mar 31, 2023, up from 33 per cent on Sep 30, 2022. This was mainly due to increased bank borrowings to fund the Reit’s acquisition of a 25.5 per cent interest in Nex and additional 10 per cent interest in Waterway Point.
Ng said that the acquisitions will provide additional growth for FCT. The manager is also looking at growth opportunities through further acquisitions and asset enhancement initiatives.
“When we evaluate opportunities, we are always looking from the perspective of ‘how could this acquisition add onto our portfolio?’... We are not going to go in and acquire something that is going to destroy value,” Ng noted.
Meanwhile, FCT’s proportion of fixed interest rate borrowings was raised to 76.4 per cent from 73.2 per cent as at Dec 31, 2022, to better manage interest-rate risks. The all-in average cost of debt in the year to date stands at 3.6 per cent, compared with 3.5 per cent as at Dec 31.
“Despite the headwinds from rising interest rates and operating costs, we saw good traction in lease renewals and signing of new tenants amid improved retailer sentiments and healthy consumer spending,” Ng said.
He also noted an increasing trend of consumers prioritising their spending on essential goods and services, which bodes well for FCT’s retail portfolio.
FCT units were trading 1.3 per cent or S$0.03 lower at S$2.29 as at 10.15 am on Wednesday.






