

The rebirth of the Nikkei: Why investors are turning their eyes to Japan
Reforms have increased transparency and strengthened accountability
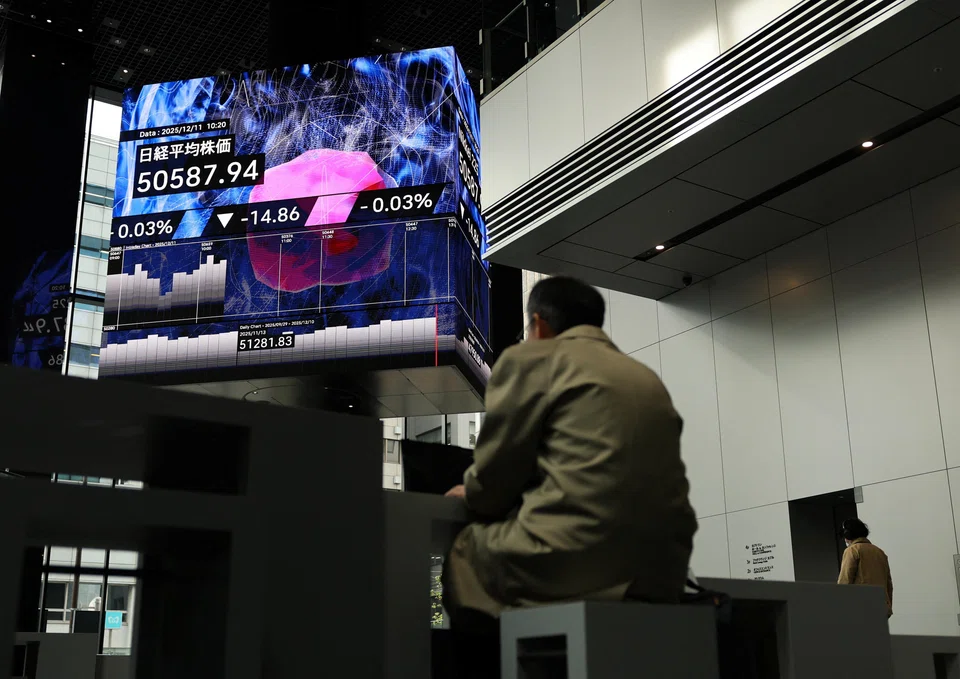
THE Japanese stock market has made a strong comeback, and is once again on investors’ radar after years of being overlooked due to a weak economy and a deflationary backdrop. Japan’s benchmark index, the Nikkei, has risen 28 per cent over the past twelve months. The biggest winners? Tech, semiconductors and financials.
Although valuations have improved in recent months and are no longer at depressed levels, there is still room for further earnings growth and improvements in Japanese companies’ fundamentals – factors that justify higher multiples.
The renewed strength in the Japanese market reflects the success of several measures introduced to improve efficiency and governance among listed companies. Historically, these firms have held large cash positions and maintained cross-shareholdings, which has weighed on their profitability.
In recent years, the government of Japan and other institutions – such as the Tokyo Stock Exchange – have promoted reforms to increase transparency, strengthen accountability and ensure greater independence on corporate boards. These changes best explain the rise in Japanese stock prices.
The government’s plan is highly ambitious: it seeks to increase Japanese savers’ allocation to local equities, complemented by measures from the Tokyo Stock Exchange encouraging companies to reduce their high cash balances. The pandemic also marked a turning point in Japan’s departure from its longstanding deflationary environment.
In addition, in October, Sanae Takaichi became prime minister of Japan. With a distinctly pro-economy stance, she aims to accelerate the transformation of corporate leadership structures within Japanese companies. From a more macroeconomic perspective, Japan’s exit from a deflationary environment is providing an additional tailwind for corporate earnings.
Japanese consumption has spent several decades in a kind of desert, with confidence severely damaged by the deflationary spiral in which the country was trapped – one that affected corporate profits, employment, consumption and, ultimately, prices.
The composition of the index has also contributed to its appreciation, given its exposure to technology, semiconductors and financial services, in line with broader global trends.
What do we expect for the Japanese economy and markets in 2026?
The latest gross domestic product data showed a 1.8 per cent contraction in activity in September, but a closer look at the underlying components reveals that both private consumption and investment proved resilient.
Japan currently has a relatively solid base of domestic demand, and the government intends to build on this by deploying a new fiscal stimulus package. In other words, the sizeable package being proposed lays the groundwork for an economy that could, to some extent, overheat in 2026.
The country’s exit from deflation reflects this dynamic – the arrival of new measures aimed at containing inflation would only prolong those symptoms. The key will lie in the Bank of Japan’s ability to maintain a monetary stance finely calibrated enough to keep the economy in balance: to avoid discouraging consumption while at the same time preventing inflation from becoming entrenched and de-anchoring expectations.
It will be crucial to monitor how this interplay between activity and prices evolves, as well as the degree to which institutions tolerate movements in either indicator. Ultimately, fiscal and monetary policy are the fundamentals that sustain the credibility of the currency and, therefore, capital flows.
Javier de Berenguer is investment manager and fund selector at Mapfre Inversion. Eduardo Garcia Castro is senior economist at Mapfre Economics.
TRENDING NOW
CPIB hauls Multi-Chem CEO, COO in for questioning; stock hits ‘circuit breaker’

Fed hike throws Singapore banks a margin lifeline; UOB likely to benefit more

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

From Haidilao to Oriental Kopi: How some of Asia’s favourite F&B players are faring in 2026

