

Massive impairment by Ezra's subsea JV partners clouds its future (Amended)
Its JV partners unveil writedowns from their stakes in Emas Chiyoda Subsea; Ezra's stake in ECS 'could face impairment of US$185m to US$385m'
Singapore
EZRA Holdings's early-morning trading halt on Wednesday has fuelled speculation over how the beleaguered offshore-and-marine group can withstand another massive impairment charge corresponding to the writedowns that have been unveiled by its subsea joint-venture (JV) partners.
A Maybank Kim Eng internal research note warned about taking cues from the two writedowns totalling 51 billion yen (S$635 million) by the Japanese partners of Emas Chiyoda Subsea (ECS).
The brokerage said Ezra will see its entire equity wiped out upon taking its corresponding share of impairment.
The JV partners, Chiyoda Corp and NYK Line, on Tuesday issued warnings against one-time writedowns - 38 billion yen for Chiyoda and 13 billion yen for NYK Line, for respectively 35 per cent and 25 per cent interest in, and loans to ECS.
Taking the cue from the 37-77 per cent range of writedowns recognised by its Japanese partners, Maybank Kim Eng said in its internal note that Ezra's stake in ECS could face impairment of between US$185 million and US$385 million.
Further assuming a best-case scenario where the entire US$81.9 million JV impairment on Ezra's financial statements for FY16 was for its stake in ECS, the group still faces impairment risk of US$103 million to US$303 million, which could potentially wipe out its equity to controlling interest of US$232.98 million, the brokerage said.
In Q4 FY16, Ezra had already taken on board US$370.3 million in total impairments and provisions, which resulted in a Q4 loss of US$339.6 million. The full-year loss for FY16 was US$887.75 million.
The group had in aggregate US$819.34 million of secured and US$365.48 million of unsecured borrowings payable in a year or less on its balance sheet as at Aug 31, 2016.
Its annual report lists its principal bankers as DBS, DNB Asia, OCBC and UOB.
Considering Ezra's short-term debt alone would have far outweighed its equity to controlling interest, a consensus emerging in the market is that the group clearly needs a fresh equity injection to pull through another massive impairment on its ECS stake.
When it released its FY15 results, Ezra had already acknowledged that the group would face a going-concern issue if efforts made at reaching out to its stakeholders and in consolidating its funding requirements did not achieve a favourable and timely outcome.
Asked by The Business Times about Chiyoda and NYK Line's massive writedowns, the group declined comment.
Observers are, however, split on how they interpret the intent of these Japanese investors and Ezra's chances at attracting fresh equity injections.
Asked if Chiyoda and NYK Line may pull the plug on Ezra, DVB Bank's managing director Geir Sjurseth said: "I would like to think the Japanese are caught by necessity to take the impairments."
Both Chiyoda and NYK Line had taken a calculated risk and chosen to enter ECS when visible cracks had emerged in the O&M sector, he noted.
The DVB senior banker added that Japanese companies tend to take a long-term view with their investments, though he qualified that no one would have expected to "take huge impairments within just over six months" from injecting investments.
Others argued that the move by Chiyoda and NYK Line to take writedowns totalling S$635 million, beyond the values of their equity stakes, was a way of preparing for the worst that could come for their JV.
(In the two deals completed with Chiyoda and NYK Line last year, the implied value of 100 per cent equity in ECS was US$360 million.)
One broker expressed doubt over whether Ezra can still attract new, sincere investors.
In addition to the woes confronting ECS, Ezra's majority-owned offshore support vessel (OSV) subsidiary Emas Offshore Limited (EOL) had been bleeding cash and the group had entered into share-charge arrangements for its shareholding in the profitable yard subsidiary, Triyards, with DBS and OCBC.
Observers had linked Ezra's recent cash flow problems to EOL's scuffle with its Malaysian oilfield-services associate Perisai Petroleum over Perisai's exercise of put option to sell a 51-per-cent stake in the joint venture, SJR Marine, to EOL for US$43 million. A noteholder winding-up petition against Perisai had threaten to thwart a settlement towards the put option between EOL and its Malaysian JV partner.
The broker noted that the beleaguered O&M group also faced mounting pressure on the trade payables front, with its erstwhile subcontractor Bibby Offshore issuing a letter of demand against the ECS JV for more than US$14.7 million allegedly owed. He said the group may have to turn to its founding Lee family for fresh equity.
A letter obtained by BT indicated that Bibby Offshore is going after ECS for an alleged trade debt from an offshore-installation services agreement and a work order entered into between the two parties.
Ezra's legal spat with Bibby Offshore emerged after two other trade creditors, Forland Subsea AS and Ocean Yield ASA, issued separate statements suggesting Ezra's subsea business unit could not service two standing bareboat charters.
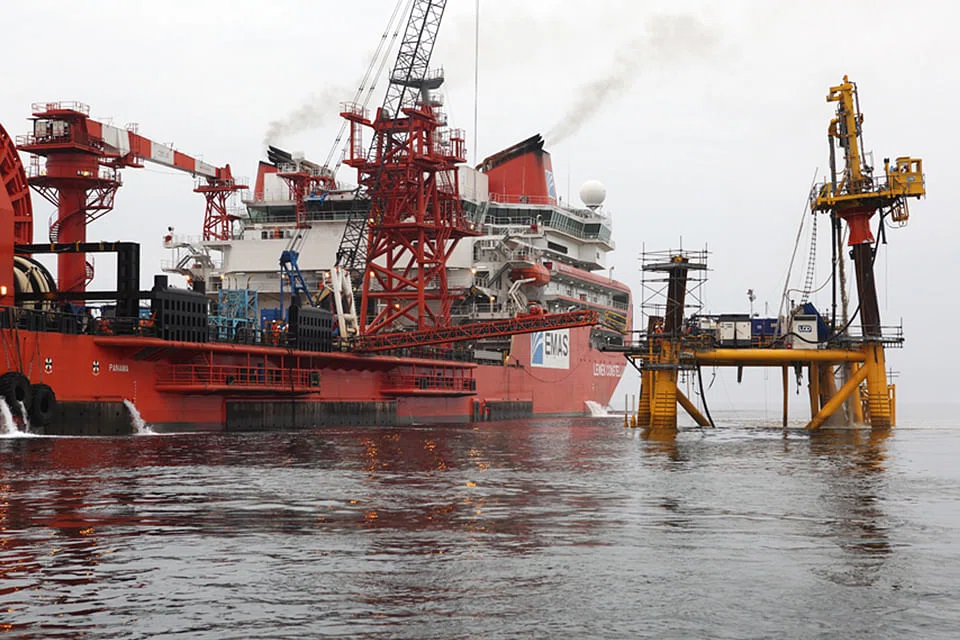
Shortly after, Forland Subsea said in a follow-up statement that it had reached a temporary agreement with Emas AMC (now ECS) for the deployment of an offshore-support vessel, Lewek Inspector, to complete an ongoing project off Congo.
Shares in Ezra last changed hands at S$0.048 before the counter was put on a trading halt.
Amendment: Maybank Kim Eng clarified that the JV impairment on Ezra's FY16 financial statements should have been stated in US dollars not in Singdollars. Consequently, the impairment risk on Ezra's ECS stake should have been US$103 million to US$303 million. The article has been revised to reflect this update.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Stocks to watch: DBS, DFI Retail, Frasers Property, Clint, ESR-Reit, Centurion, Coliwoo
DFI Retail to bag US$340 million, Starbucks business in Asia in deal with Maxim’s Caterers
Green fuels, autonomous ships: How Singapore is future-proofing its shipping industry

