OSIM: is the stock selloff over?
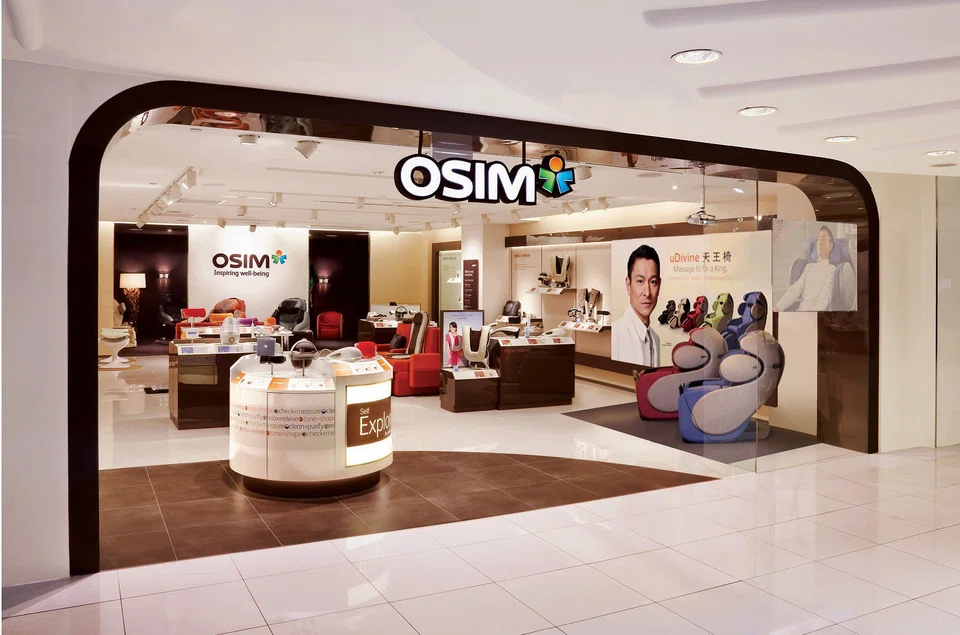
THE stock price fall was shockingly swift. And those still invested in lifestyle products group OSIM International must be wondering when the pain will end.
Amid the search for answers, some observers blame the dismal third-quarter net profit, which fell 28 per cent to S$16 million. This translated to Q3 earnings per share (EPS) of just 2.11 Singapore cents (Q3 2013: 3.14 cents), bringing nine-month EPS to 9.87 cents, below the 10.21 cents it earned a year earlier. The more bearish analysts are projecting full-year earnings of 13 cents or so, lower than last year.
At the current stock price of about S$1.80 and taking out net cash of 30 cents a share, the market is pricing in an earnings multiple of under 12 times - which is not rich. If investors think OSIM can maintain earnings at this level in perpetuity, with no growth at all in any of OSIM's massage products, supplements or tea businesses, then S$1.80 sounds like a fair price to pay.
With a six-cent dividend payout, prices are unlikely to fall below the S$1.50 to S$1.60 level, when dividend yields near 4 per cent and ex-cash earnings multiples drop under 10 times.
All this is scant comfort to those who had bought in when OSIM was more than S$2.80 a share. People assumed OSIM's strong double-digit percentage growth in revenue and profit would continue forever, boosted by a promising luxury tea brand - TWG Tea - that it had acquired. Assuming 15 cents per share a year of forecast earnings, OSIM was trading ex-cash at a multiple of 18 to 19 times - roughly that of luxury goods powerhouse LVMH now.
Vicious circle
What had happened to precipitate the quick U-turn in expectations?
As with all high-PE ratio stocks, a vicious circle sets in once earnings slow down and the price multiples people are willing to pay are revised downwards.
OSIM duly plunged in end-October after unveiling the disappointing third-quarter results.
Management guided that the company was in "a period of increased investment across the group". Legal fees and start-up costs for TWG Tea were key culprits. But that alone does not explain the share price plunge. Investors are usually patient when a company puts capital to work.
What is behind the selloff is an arguably bigger concern: that OSIM's core massage chair business is hitting a rough patch again. A whiff that something is awry with the fundamentals, and investors scramble for the exits.
Investors with longer memories will remember that exactly eight years ago, OSIM suddenly fell into the red for its third-quarter. Management blamed this on fakes in China making unsubstantiated claims, resulting in negative publicity. It said the third quarter was "a blip".
But more bad news came when OSIM eventually gave a surprise profit warning a few months later. Combined with worsening results from the US retailer it acquired, Brookstone, OSIM would fall into a downward spiral until it wrote Brookstone off in early 2009. This time, investors are wondering if history will repeat itself, with a new acquisition of TWG Tea, the usual optimism from management and a China slowdown to boot.
How bad is the core business decline in the third quarter? Group revenue rose 3 per cent to S$158 million in the third quarter from S$153 million a year ago. But this year, TWG Tea's results have been consolidated within OSIM's numbers. TWG Tea's sales were about S$42 million for its year ended March 2013. Management said it is growing at "double-digits".
Assuming, conservatively, that sales are just S$50 million in calendar year 2014, and are evenly spread out, OSIM's third-quarter revenue excluding TWG Tea's contribution is about S$145 million. This is already a revenue decline of 5 per cent for the core business and nutritional supplements business combined.
The more TWG grew, the worse the decline would be.
China, OSIM's main market, is determined to slow its economic growth to a more sustainable pace. The Singapore business also looks flat or is possibly slowing. Given the tough operating environment, it remains to be seen if OSIM's third-quarter slowdown is another minor blip, or the beginning of a down cycle.
Reassuringly, OSIM's margins were kept at the same level or even rose slightly, depending on which cost measure you use. But cost savings and closing down unprofitable stores, which OSIM has been doing, can only go so far.
If the slide in revenues worsens during the holiday season this year, an earnings decline is not unthinkable for 2014.
TWG Tea, meanwhile, is making money on its wholesale arm which supplies hotels and airlines. But given the scale of its expansion, one-off setup costs will hit OSIM's earnings. Legal uncertainty will add to costs.
This quarter, the number of TWG Tea outlets is expected to rise to 45 from 37 at end-September. Another 15 to 20 new stores are targeted to be opened next year. As management disclosed in a recent announcement, every central kitchen (that supports five to 10 outlets) costs over S$1 million, every outlet S$1 million. Staff also need to be trained.
What lies ahead
A slowing China, weak consumer sentiment in the region, combined with a period of increased investment, have frightened investors off OSIM and the promise of TWG Tea.
Some observers see hope in founder Ron Sim, given his 30-year track record of growing the group through thick and thin. But things might get worse before they get better. Believers have to hunker down for a while.