

Shifting narrative on the rupee demonetisation
With the measure's unintended consequences, Modi seems to suggest now that its main aim was to move towards a digital or cashless society.
ALL eyes were on the outcome of the fifth bi-monthly policy review of the Reserve Bank of India's (RBI) Monetary Policy Committee (MPC) for some clarity regarding the macroeconomic impact of the demonetisation exercise in India that was initiated on Nov 8.
With the unanimous consent of all the six members of the MPC, the RBI's decision on Dec 7 to leave the benchmark policy rate (the repo rate) unchanged at 6.25 per cent surprised the market somewhat. While India has been a growth star in a disinflationary global economy, recent data suggests a slowing down of the economy - largely but not solely due to the withdrawal of 500 and 1,000-rupee notes from circulation, which has resulted in a sharp credit squeeze.
Several small and medium-size businesses, agriculture-related businesses and other business activities belonging to the informal sector which are almost completely cash-dependent have faced severe economic disruption. In view of this, the general expectation among analysts was that the RBI would reduce its key policy rate by at least 25 basis points to partially offset the growth slowdown.
As against this, there are valid concerns about a highly volatile global environment which has seen emerging markets and their currencies being hit by the so-called "Trump tantrum", resulting in a sudden stop in capital inflows. Given this situation, a further cut in interest rates may have only added to the depreciation pressures on the Indian rupee with a negative and worsened inflation outlook - which (while still subdued) could be negatively impacted by the recent Opec decision to cut oil supplies and the consequent reflating of oil and energy prices. There are also the potential inflationary pressures arising from implementation of the Seventh Pay Commission recommendations as well as the goods and services tax (GST).
In explaining its decision to maintain the status quo on interest rates, the RBI noted that while demonetisation could "drag down growth this year", more information was needed about its impact, and if "the impact is transient, as widely expected, growth should rebound strongly". This said, the RBI cut the economy's growth forecast for the current fiscal year to 7.1 per cent from 7.6 per cent earlier due to disruption in supply chains and demand compression.
Further, the RBI also highlighted concerns about meeting the objective of achieving consumer price index (CPI) inflation of 5 per cent by the last quarter of 2016-17 and the medium-term target of 4 per cent CPI inflation, while taking the view that, on balance, it was "prudent to wait and watch how these factors play out and impinge upon the outlook".
The RBI perhaps could still cut rates in its next policy meeting timed after the Union Budget presentation next Feb 8, by which time there may be greater clarity both in terms of growth and inflation trajectories as well as a relatively more comprehensive assessment of the macroeconomic impacts of demonetisation.
Despite no rate cut this time around, the RBI's overall monetary policy stance has actually been accommodative. To be sure, the demonetisation exercise led to an unexpected surge in bank deposits, with the value of old currency notes deposited in the banks so far touching 11.5 trillion rupees (S$241 billion). This, in turn, could have caused a sharp rise in overall liquidity in the economy if the banks had on-lent the money to the public and driven down lending rates.
But the RBI took a rather unusual decision to raise the incremental cash reserve requirement (CRR) to 100 per cent for a fortnight between Nov 26 and Dec 9 by way of preventing the banks from on-lending this surplus liquidity.
In its policy review, however, the RBI noted that this incremental CRR would be withdrawn on Dec 10, which presumably would provide the economy a much-needed liquidity boost.
A DAMP SQUIB?
In fact, the original decision by the RBI to impose the onerous incremental CRR does not seem totally unwarranted given that the deluge in deposits to the tune of 11.5 trillion rupees was contrary to what the government had originally estimated: that roughly five trillion rupees of the 15 trillion rupees that was taken out of the economy would not find its way back into the banking system. The fact that banks are now inundated with deposits is ironically bad news for the government in terms of dealing a death blow to corruption and black money.
The return of so much money into the banking system can only imply two things: either the black money has been "whitened" through the quintessential Indian jugaad (creative manipulation); or it was never black to begin with, as it was stored in available cash substitutes including real estate, gold or foreign currency.
Whichever might be the case, this deposit surge might dampen the expectations that if some of the black money is not returned to the banking system, it would have then translated into potential windfall gains for the RBI that could have been a fiscal benefit for the government. However, the RBI governor was categorical in his statement that any such windfall for the central bank due to reduced liabilities would not be passed on to the government as a form of a special dividend.
Considering the potential miscalculation involved in terms of how much black money is circulating in the economy, Prime Minister Narendra Modi's government itself seems to have been slowly shifting the narrative of demonetisation objectives from one of combating corruption and black money to moving towards a digital or cashless society. This seems fair given that the potential tangible long-term benefits of this experiment lie in enhancing financial inclusion in the economy.
Notwithstanding the above, more generally, the demonetisation push should be viewed as an attempt to provide an impetus for a large segment of the society to start migrating towards cashless payments as well as greater use of banking services through digital forms.
Another laudable objective behind the demonetisation exercise relates to the crackdown on fake Indian currency notes (FICN) or counterfeit currency notes, which are viewed as an important step in curtailing terrorist financing. Of particular concern is the widespread belief that this money - with the old 500-rupee and 1,000-rupee notes accounting for the bulk of these counterfeit notes - has been used for nefarious activities such as terrorist financing, leading to much disquiet. If this is true, then the post-demonetisation phase should see a notable reduction in terrorism-related activities.
In relation to this, banning high-denomination currency notes is a policy idea that is gaining credence worldwide. It has been strongly advocated by notable Harvard economists such as Larry Summers and Kenneth Rogoff, both of whom have recommended getting rid of big bills (like US$100) in the context of clamping down on criminal activities such as money laundering and tax evasion. Singapore, for instance, stopped issuing S$10,000 notes from October 2014 to combat financial crime.
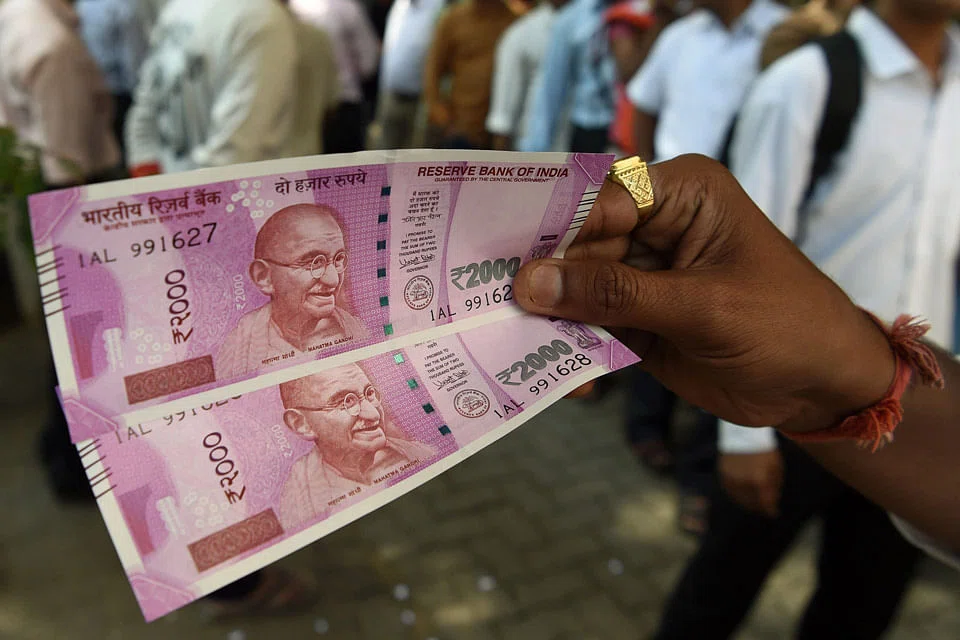
In this regard, apart from oft-repeated complaints and concerns about the manner of implementation of this demonetisation saga, one of the possible mistakes that the Modi government made in the process was to introduce a larger currency denomination of 2,000 rupees, which seems to be at odds with the original objective of curbing corruption and money laundering.
It may well turn out that the introduction of the 2,000-rupee note was intended to be a short-term measure, and that it too might be revoked in the near future. It is unclear, however, whether the public would stomach another major round of demonetisation in the foreseeable future.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
‘Our bread and butter’: Family-run Loo’s Hainanese Curry Rice hands reins to third generation

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
US says China to buy 10 million tonnes of coal in 2027 and 2028

