

More downs than ups for China's junk bonds
Combined 35 rating cuts by S&P, Moody's exceed four upgrades
Hong Kong
CHINA'S junk bonds suffered nine times more downgrades than upgrades this year, and another issuer faced a final deadline on Friday after the first default by a developer.
A combined 35 rating cuts on the US dollar-denominated notes by Standard & Poor's and Moody's Investors Service exceeded four upgrades, data compiled by Bloomberg show.
Coal importer Winsway Enterprises Holdings Ltd needs to pay a US$13.15 million coupon on its 2016 bonds as a grace period ends. S&P cut its grade on Winsway, water treatment provider Sound Global Ltd and Evergrande Real Estate Group Ltd in the past month.
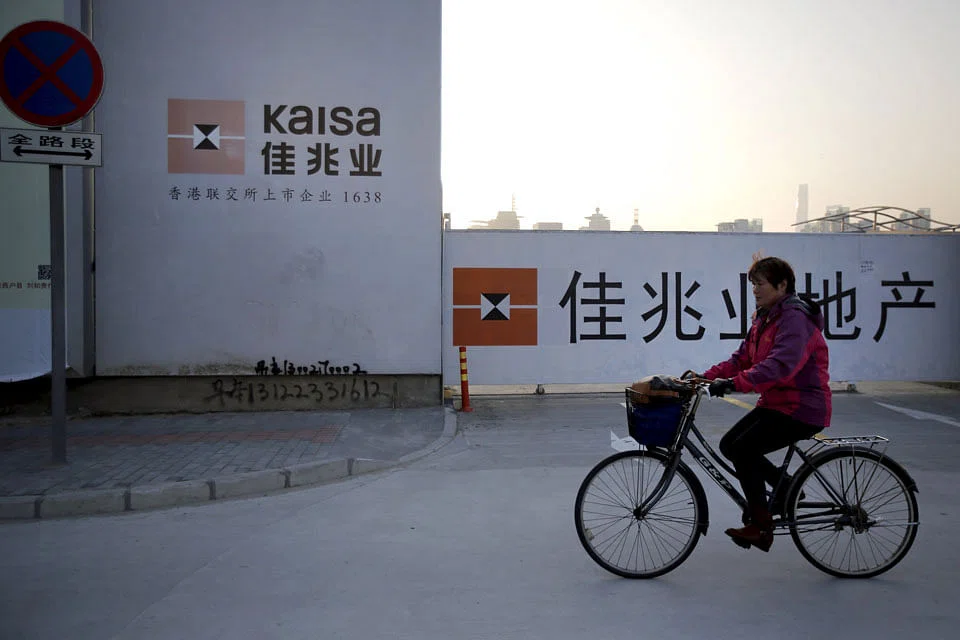
The central bank's two interest rate cuts since November and easier home financing failed to prevent Kaisa Group Holdings Ltd from becoming the first Chinese real estate company to default on bonds. Over half of the nation's high-yield companies tracked by CreditSights Inc lack enough unrestricted cash to cover short-term debt, according to the independent credit researcher.
"Rating downgrades tell you that fundamentals are deteriorating," said Gaurav Singhal, a Hong Kong-based credit analyst at Nomura Holdings Inc. "Now, the biggest questions are whether the ongoing policy easing will work and most importantly, whether bondholders are getting paid for the risk it may not."
The latest day of reckoning in Chinese credit markets was Friday, as a 30-day grace period ends for Winsway to make the interest payment on its US$309.3 million of 8.5 per cent bonds.
The importer of coal for steelmakers missed the payment last month and said that it planned to discuss debt restructuring. The securities were at 28.3 cents on the dollar as at 9.52 am in Hong Kong, near their record low of 28 cents marked on Thursday, according to prices compiled by Bloomberg.
Laura Shi, a spokeswoman in Beijing for Winsway, said that the company will disclose information about any coupon payment after Hong Kong stock exchange trading hours.
S&P lowered 11 bonds and raised none last month, the weakest start to a quarter since 2005. At Moody's, 13 downgrades versus one upgrade in the first quarter lifted the trailing 12-month ratio to a level not seen since at least 2009, an April 16 report showed.
Sound Global's notes were relegated three steps to "CCC-" by S&P on April 30 after the Beijing-based company said that an audit discovered a two billion yuan (S$427.9 million) cash shortfall. It has a 50:50 chance of defaulting on its US dollar bond within six months, S&P said.
The company's US$150 million of 11.875 per cent 2017 fell as low as 63 cents on the dollar last month and were at 75.3 cents as at 9.55 am in Hong Kong.
"Chinese property developers' cash flows were squeezed by slower collection rates and the tight credit environment in China last year," Sandra Chow and Cheong Yin Chin, analysts at CreditSights, wrote in an April 21 report. "Refinancing risk becomes a growing concern as operations come under pressure and their funding channels shrink."
The People's Bank of China (PBOC) cut its reserve ratio by one percentage point effective April 20, the most aggressive reduction since the global credit crisis. The government has also eased downpayments on second home purchases.
The stimulus helped boost returns on Chinese US dollar junk bonds to almost 3 per cent in April, the most since September 2013, an index compiled by Bank of America Merrill Lynch shows.
The rebound from a 0.3 per cent loss in March was led by oil companies MIE Holdings Corp and Honghua Group Ltd as crude prices recovered. Fantasia Holdings Group Co and Hopson Development Holdings Ltd paced gains among developers.
"The market is getting desensitised by Kaisa and at this stage, bigger macro forces - both monetary and fiscal policies onshore - dominate," said Alan Kao, a bond trader in Hong Kong at Haitong International Securities Co, a unit of China's second largest brokerage. "Policymakers are taking some uncertainty away."
S&P also cut coal producer Hidili Industry International Development Ltd to "CCC-" with a negative outlook from "CCC" on April 28, as well as Guangzhou R&F Properties Co to "B+" from "BB-" on April 30 citing leverage and refinancing risk.
Among onshore debt, three with equivalent face value of US$1.61 billion mature this month from China Datang Corp, Shandong Iron & Steel Group Co and Kailuan Group Ltd Liability Corp, according to Bloomberg data. Their common denominators: an unprofitable business, falling revenue and more bonds outstanding than cash in hand.
China's Communist Party leaders vowed in a meeting last week to step up targeted measures to counter downward economic pressure.
The PBOC has also considered using a tool kit that includes unconventional policies such as a loan programme that channels money to favoured areas of the economy. The central bank may inject liquidity via policy banks such as China Development Bank, Caixin magazine reported on Monday, citing an unidentified person.
"Although bond investors have long been considered the smart money, all of their genius is no match for the power of central banks in the current environment," said David Tawil, a co-founder of hedge fund Maglan Capital LP in New York, referring to how central bank policies are supporting asset prices. Bloomberg
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Why the best annuity in Singapore may not be enough
In a super-aged Singapore society, we must learn to differentiate independence from dignity

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing

