


Yield-hungry investors chase industrial investments in Asia to record high
Singapore
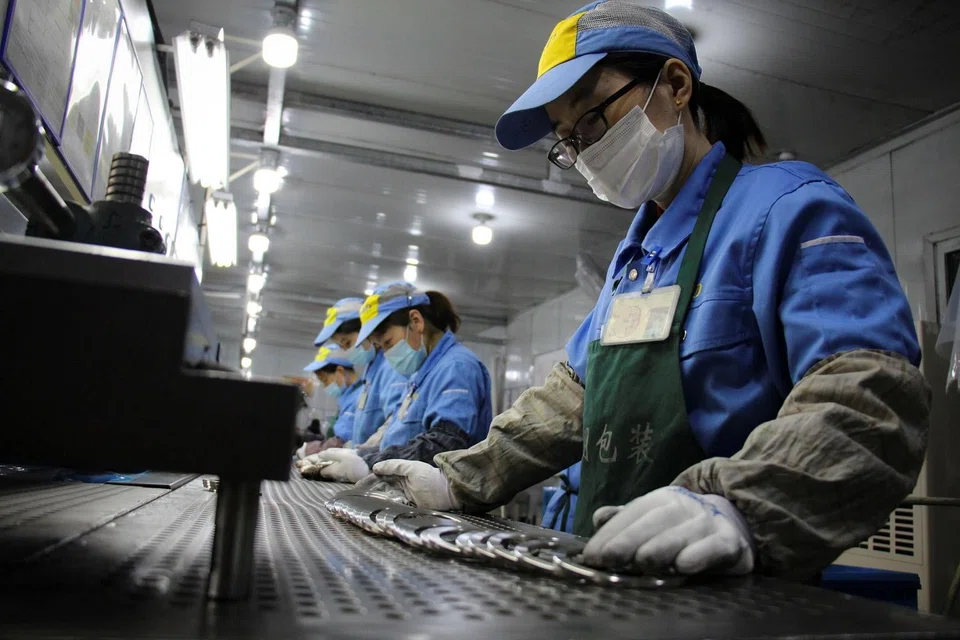
WHILE the office remains the preferred asset class among commercial properties in Asia, yield-hungry investors are chasing industrial and logistics investments to a record high, spurred by the e-commerce acceleration during the pandemic.
Property experts told The Business Times that in a generally challenging year for Asia property investments, where numbers and values have fallen compared to 2019, the industrial and logistics sector has been an exception, standing out as an area of relative stability and opportunity.
Strong capital inflows to the sector since the pandemic have narrowed the yield spread with the office sector to just 30 basis points (bps) globally and 75 bps in the Asia-Pacific. With further logistics yield compression expected in 2021, the spread is set to narrow even further.
Stuart Crow, chief executive officer, Capital Markets, Asia Pacific, at JLL, said the long-term outlook for the Asia Pacific logistics sector is "incredibly positive".
"Generally, investors remain under-allocated to logistics and multifamily assets, due to the continued expansion of e-commerce globally and the increased adoption of technology - they are looking closely at available opportunities to close this gap."
Mr Crow said the trend was observed in 2020, where investors pushed to increase their allocation to logistics and data centres with these sectors attracting over US$15 billion of new funds.
"The primary focus is on Australia, Japan, South Korea and China, and given the expectation for continued low interest rates, large amounts of capital and the continued hunt for yield, we expect demand for this asset class to remain robust," he said.
Terence Tang, managing director, Capital Markets and Investment Services Asia at Colliers International, said after a period of wait-and-see, investors became impatient and started their search for yields in Asia, confident that the region will bounce back from the pandemic strongly.
"We are seeing a growing interest in industrial and logistics across most of the markets in Asia, driven by technology transformation and lifestyle changes," Mr Tang said, adding that post-Covid, certain sectors involving hospitality and retail are deemed riskier than others.
Greg Hyland, CBRE's head of Capital Markets, Asia Pacific, expects the robust demand for logistics assets and investor allocations to continue to increase this year.
"In our conversations with clients, we have seen indications of strong intentions to purchase, with some even willing to bid above asking prices. In some markets, the yields are tighter than office and I believe there is room for future compression over the course of the year," he said.
Investment in the logistics sector reached a record high in the Asia-Pacific in 2020, with four of the region's markets ranking in the top 10 biggest logistics markets globally in the year, Benjamin Chow, an analyst based in Real Capital Analytics (RCA) in Singapore said.
"The e-commerce revolution was already well underway before 2020, and the Covid-19 pandemic served to reinforce investor appetites for warehouses even further," he added.
Deal activity totalled US$13.5 billion in 2020, according to preliminary RCA data, just eclipsing investment levels in 2018 and 2019. South Korea and Australia notched record years for investment in distribution facilities, while China and Japan both had their second most active years. Together, these four markets accounted for 96 per cent of all logistics deal volume in the Asia-Pacific in 2020.
Neil Brookes, head of Capital Markets, Asia Pacific, at Knight Frank, said the industrial sector accounted for 22.3 per cent of all commercial transaction volumes last year. This is a 50 per cent increase when compared to its 14.8 per cent historical five-year average.
"Heading into 2021, we believe this trend is likely to continue as e-commerce driven industrial demand growth continues to rise exponentially, especially as internet penetration gathers pace in Asia," he said.
As the most preferred asset class for investors last year, the office accounted for 47 per cent of all commercial transaction volumes in 2020, according to Knight Frank. This, however, has shrunk slightly when compared to its historical five-year average market share of 52 per cent.
"This was not surprising given the softer rent growth expectations on weakening tenant bottom lines, rising vacancies, and shrinking demand as firms implemented more work-from-anywhere strategies," Mr Brookes said.
Mr Tang also sees strong interest in the office space, particularly in Singapore, where transacted prices in some cases are higher than pre-Covid levels.
"The office is still very important for building and cultivating a corporate culture and a place for collaboration," he reckoned.
The second-half of last year brought about relief for commercial capital markets across Asia Pacific as economies started to reopen and post signs of recovery, bolstering growth expectations and acting as stabilisers to asset price volatility.
According to Knight Frank, total Asia-Pacific commercial transaction volumes for the last two quarters of 2020 came in at US$61.7 billion, down about 37 per cent year-on-year. This brought the full year's commercial transaction volume to US$134.6 billion, down about 31 per cent year-on-year, which was the lowest level seen since 2012's US$131 billion.
Despite the overall year-on-year (y-o-y) decline in volumes, markets such as South Korea, Japan, and the Chinese Mainland recorded positive y-o-y growths; mainly on the back of a quick economic recovery post a well-managed pandemic response, access to cheap credit, and robust domestic demand.
The standout market this year was South Korea which recorded US$36 billion in commercial transaction volumes, up 28 per cent y-o-y, with notable transactions such as ARA's acquisition of Parc 1 Tower 2 for US$897 million.
Analysts expect to see more capital flow out of the region this year as economies reopen and investors look to diversify their exposures and pick up assets at attractive pricing in global gateway cities such as London.
JLL's Mr Crow said Europe remains the most attractive investment destination for cross-border buyers, with close to US$175 billion flowing from the Asia-Pacific to Europe, Middle East and Africa (EMEA) alone over the last decade.
Just as in Asia, offices remain the sector of preference for Asian investors. "However, there is a growing shift towards logistics, living sectors including multi-family and student accommodation, and alternative asset classes such as data centres," Mr Crow said.
CBRE's Mr Hyland said investors are still showing very strong interest in Asia - with Tokyo, Singapore and Seoul emerging as the top three destinations.
READ MORE: Online shopping should give ARA Logos a lift






