

DBS sees shades of 'green premium' in Asian project bonds
Also fuelling demand is the rising awareness of sustainability impact on green project bonds
Singapore
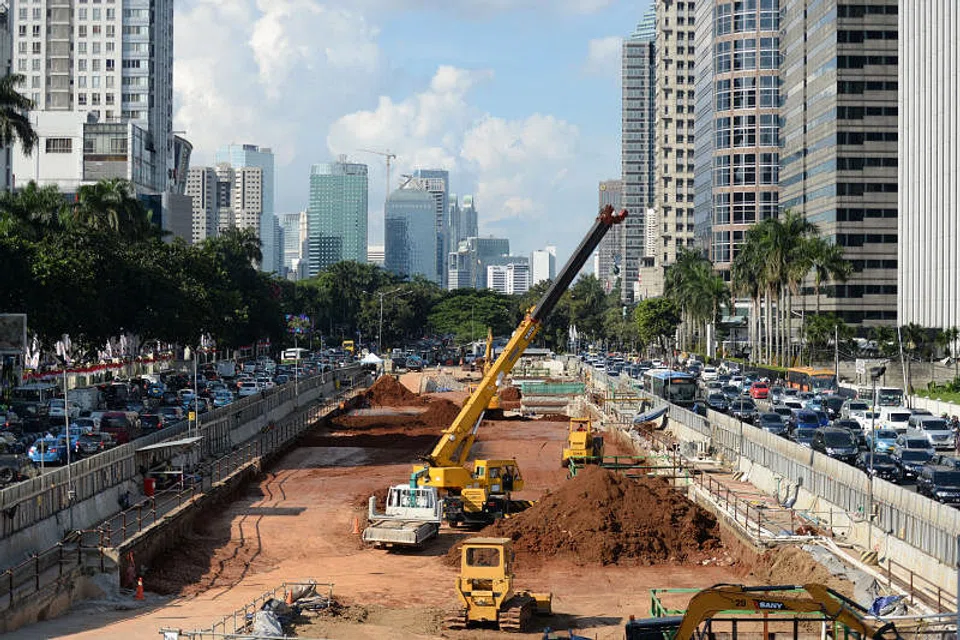
AS Asia's massive infrastructure needs continue to grow, it is clear that traditional bank debt alone is not enough to plug the widening gaps.
And the need for over US$26 trillion in infrastructure investments until 2030 has sparked the revival of project bonds in capital markets, with about six US-dollar issuances in the region since 2017.
But that overarching demand for infrastructure financing is not all that is driving this funding resurgence.
The rising awareness of how sustainability can drive the structure of green project bonds is pushing demand to new heights globally, said DBS head of fixed income Clifford Lee.
DBS has been making inroads in Asia's project bond space, acting on three of six US-dollar issuances in Asia since 2017. The bank was most recently the joint global coordinator for a dual-tranche green project bond for Indonesia's Star Energy Geothermal. The US$1.1 billion deal in October saw demand amounting to US$2.8 billion from a diverse base of investors spread across the US, Asia, Europe and the Middle East.
Amid choppy markets owing to geopolitical tensions and Covid-19, the project bond's green label were a strong selling point for investors, Mr Lee told The Business Times.
Bonds that raise funds for renewable energy projects are typically labelled green project bonds.
In Star Energy's case, its green project bond is tied to geothermal power plants. This is different from coal firm Paiton Energy's project bond in 2017, where the underlying asset is a coal-fired plant.
"Not only are the use of proceeds green (for Star Energy), but the very assets that generate the cashflow are also green," said Mr Lee.
The transaction's "green premium" helped tighten funding costs by 30 to 40 basis points compared with similar deals.
"For the first time, we actually see some proof that once you structure a bond in a sustainable form, you will get stronger and better reception from the market to give you better funding levels," said Mr Lee.
The way the deal was structured also lifted credit ratings to investment-grade (BBB-), which proved crucial among investors.
This comes as Star Energy's debut green bond in 2018, rated "BB-", was not as well-received then. The deal raised US$580 million, falling short of the US$650 million target.
"If you have a bond where the underlying credit is not strong, or the pricing is not well received by the market, it wouldn't be more accepted even if it's green," said Mr Lee.
While the market is hungry for more investment-grade green project bonds, there remains a supply-demand mismatch in the region.
Paiton Energy's project bond in 2017 was the first in Asia since 2000. Though Star Energy's latest transaction paves the way for more green project deals, they are expected to be rare and few for now.
This comes as infrastructure spending in the region is still slow to pick up due to the current economic fallout and political instability in many countries, said Mr Lee.
Meanwhile, banks in Asia are also hungry to fund such projects.
"Immediate and good project financing opportunities are usually taken up by banks via bank loans. Very few opportunities come to the bond market," said Mr Lee.
The challenge is in identifying projects beyond those funded by the banks, and take them into longer tenors for the public market.
"This is a developing space. The markets are still learning how to fine-tune the bond structures and their pricing (in line with the) stage of development in Asia," said Mr Lee.
In the conventional green bond space, issuances have become par for the course for DBS.
The bank's market share for green bonds rose to 2.8 per cent year to date, from 0.4 per cent a year ago, as it had acted as bookrunner for several issuances this year.
There has also been a spike in social bonds amid the pandemic, with proceeds going towards Covid-19 impact alleviation efforts.
Year to date, social bond issuance volumes in Asia soared to US$17.2 billion, from just US$3.2 billion in the year-ago period.
As at Oct 14, DBS has acted on five social bond issuances this year. This compares with just two in 2019 and one each in 2018 and 2017.
TRENDING NOW

Ex-Sembcorp Marine CEO Wong Weng Sun acquitted of charges in Brazil corruption case

Can Mark Shaw bring Singapore back to Orchard Road and the movies?

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Prudential announces regional leadership changes, including for Singapore, Indonesia

