

Patchy subculture driving misconduct at financial firms: ex-regulator
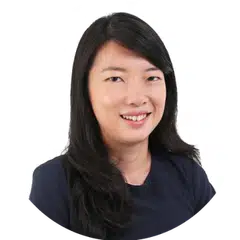
A FORMER regulator turned consultant said financial institutions should better define "proper conduct", by weeding out toxic sub-cultures and drawing clear paths for staff to call out wrongdoing.
This comes amid recent high-profile financial blowups that have exposed risk management flaws of financial institutions.
It may not be feasible to set up new safeguards only after each scandal unfolds "because then you will have a rule book that is extremely thick, with a lot of specific do's and don'ts", Deloitte's Southeast Asia regulatory risk leader Wong Nai Seng told The Business Times in an interview.
All the more, then, financial institutions should clearly and repeatedly communicate the acceptable rules of engagement, said Mr Wong, formerly assistant managing director for policy, risk and surveillance at the Monetary Authority of Singapore (MAS).
"Ultimately, for some of these matters, the financial institutions need to take responsibility. They need to own the problem. I see it primarily as a problem of governance," he said.
Mr Wong did not highlight specific cases due to potential conflicts of interest, but the downfall of Archegos Capital Management is one recent case that has left some of the biggest banks reeling, and raised questions over risk controls.
Archegos had built large, concentrated bets via total return swaps brokered by Wall Street banks. The banks are now facing billions of dollars in losses after the US investment firm defaulted on margin calls, forcing a brutal near-US$30 billion fire sale.
Some have raised questions as to whether the loss was a result of incompetent risk and compliance management, or whether their views were ignored by business heads, who may have been more attracted by the short-term benefit of not jeopardising a profitable stream of income than to consider long-term risks associated with such transactions.
Then at Wirecard, the German payments firm collapsed into insolvency in June last year after revealing that some 1.9 billion euros (S$3.06 billion) were missing from its accounts. One whistleblower in the Singapore office told BT that several attempts by his colleagues to raise certain red flags were often blocked by more powerful figures in the company.
Meanwhile in Singapore, MAS on Tuesday rapped major insurers for failing to meet rules that set out how supervisors should have been paid as part of sales of investment products and life policies. These standards, among other things, set out how commissions should be capped for the sale of regular premium life policies.
Mr Wong noted that defining proper conduct is not only in terms of treating customers fairly, but also taking an appropriate view of risk and managing it well.
To add, in a dipstick poll among executives of financial institutions last November, Deloitte found "cultural norms and behaviours" as the top challenge, cited by 31 per cent of respondents, for the implementation of an individual accountability regime.
About half of the executives also considered the inconsistency of "sub-cultures" at the team level with overall organisational culture as their top cultural challenge.
Elaborating on these cultural choke points, Mr Wong said: "Some institutions may have a more collegial approach to decision-making and may find it challenging to ascribe individual accountability, to specifically identify who the manager in charge of a particular area is."
Sub-cultures sometimes facilitate wrongdoing because newer hires tend to follow what is considered "common practice" among their seniors, he said.
"For instance, when we look at some of the investigations into the Libor incident, one of the common defences put up by the traders involved was that this was actually common practice among various team members, and in fact, common practice in the industry. Everyone was doing it and it's therefore okay for me to do it as well," he said. Mr Wong was referring here to the high-profile scheme that involved bankers at major financial institutions colluding to manipulate the London Interbank Offered Rate (Libor). It came to light in 2012.
Such cultural malpractices need to be corrected with clear communication, awareness programmes and repeated training sessions that nail down for staff the key principles that the organisation operates by.
In September this year, all MAS-regulated financial institutions will have to abide by new guidelines that reinforce the institutions' responsibilities in promoting individual accountability of senior managers, strengthen oversight of employees in material risk functions, and embed standards of proper conduct among all staff.
However, unlike individual accountability regimes in the United Kingdom, Australia and Hong Kong, which either require institutions to seek pre-approvals or notify the authorities before they take certain actions, the MAS does not require regulatory submission.
Asked if this impedes enforcement, Mr Wong said: "The challenge of that, especially for a set of relatively new guidelines where the industry practice is still emerging, is that (submission requirements) may create bottlenecks for institutions. I think what MAS is trying to do is really to first observe the range of practices in the market because the industry is still trying to figure out what's the right approach, what is acceptable practice."
Enforcement at this stage could take the form of on-site inspections, or engagements with the management.
Mr Wong said a proper framework for governance should first involve empowering employees to "ask the right questions". "The structure must be such that they are put in a position where they can effectively challenge the management and the way makers in the organisation," he said.
Next, there should be proper incentives to encourage employees to pursue proper conduct and call out wrongdoing. "The indicators for proper risk management and controls need to be built into the incentive structure and performance management system, so that individuals have an incentive to actually meet those targets, instead of just chasing revenue targets," he said.
To add, internal whistle-blowing policies should ensure an independent, transparent process for reporting, such as to the internal audit functions or an independent director.
Managers must then follow up appropriately and engage staff. "Let them know you have followed up, that these are the actions you have taken, and when you decide not to take any action, you have to explain the reasons to your staff, so that there is closure."
Corporate leaders and members of the senior management also have to walk the talk. This could involve reviewing certain organisational processes, such as hiring for values and ethics, in addition to technical competence.
READ MORE: Mizuho corporate culture the root cause of repeated system failures, probe finds
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
US trade chief to consider trade deal tariff caps in excess capacity probe
Bee Cheng Hiang customers’ e-mail addresses exposed in Singapore’s first case of AI-related data breach
DFI Retail to take over Starbucks business in Asia from Maxim’s Caterers

