

Vietnam needs more products, greater financial literacy to grow its banking market: Techcombank CEO
Kelly Ng
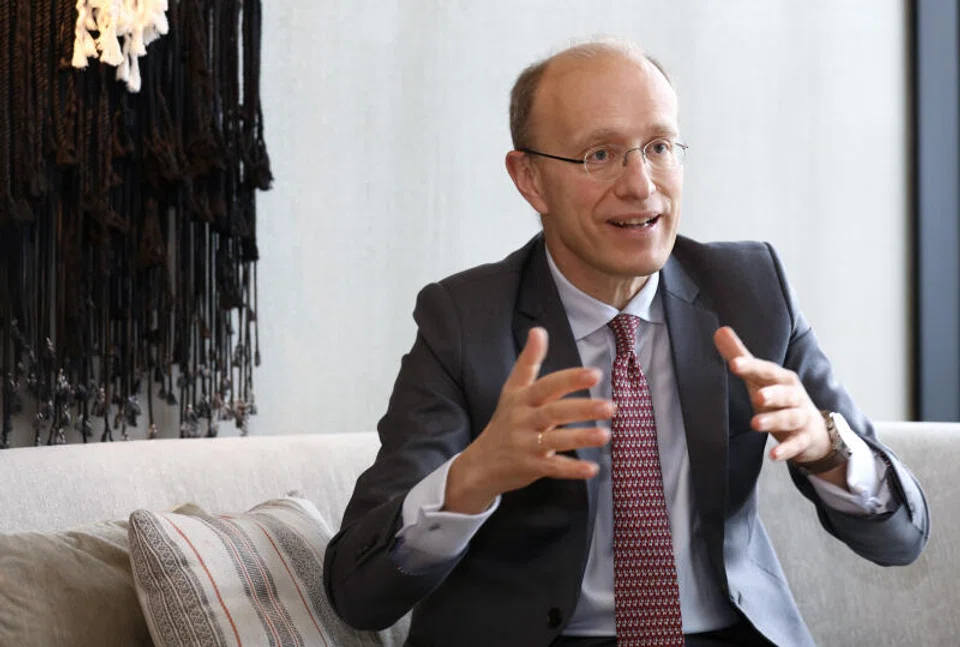
VIETNAM’s growing middle class needs access to more investment solutions and a wider variety of asset classes, as well as more financial education, said Techcombank’s chief executive officer Jens Lottner.
The bank, which is now the largest listed non-government owned bank in Vietnam, was founded in 1993 to service primarily the affluent and mass-affluent markets.
But Lottner said “privilege banking” in Vietnam still goes only as far as lounge access, fancy dinners, and higher cashback on credit cards, said Lottner, who took over as the bank’s chief in August 2020.
“On the one hand, banks have not yet built and trained relationship managers the way you would have in more developed markets. But even if we train them, what would they sell? The set of products is somewhat limited,” said Lottner, who met up with The Business Times on a recent trip to Singapore.
The opportunity being passed up is immense. Vietnam’s affluent and mass-affluent markets are expected to grow from 18.2 per cent of total households in 2019 to 30.6 per cent in 2025, according to McKinsey’s estimates.
This growing affluent and mass-affluent demographic is mostly invested in real estate, and much of Techcombank’s wealth business comes from its mortgage business.
As at end-April, about 86 per cent of all outstanding mortgages at Techcombank were held by affluent clients. These affluent clients accounted for some 70 per cent of the bank’s assets under management, but made up just 6 per cent of its total customer base.
Lottner is hoping to bring new offerings to Techcombank’s clients.
“People need to start building more diversified portfolios; otherwise you’re really stuck with real estate, because that’s what you’ve seen in the past. But I think it probably would not be what it is in the future,” Lottner said.
Vietnam has one of the least capitalised banking systems in the region, he added.
“Right now, a lot of credit is still bank-intermediated. And so the bank balance sheets are carrying a lot of the financing requirements. So if you put more and more of that growth through the balance sheet, the equity buffer will become thinner,” he said.
According to a Fitch Ratings report in March, low capitalisation levels are likely to remain a credit weakness for rated Vietnamese banks as rapid loan growth will make it challenging to raise capital adequacy ratios in the next 2 to 3 years.
Before diversification can happen, however, financial authorities must first get their house in order, Lottner said, pointing to an ongoing investigation on securities violations in the country.
The head of the country’s main stock exchange as well as the State Securities Commission chairman were fired within days of each other in May, amid a series of high-profile corporate arrests. Observers have said this is perhaps the biggest market crackdown in the history of the nation’s stock market, but also think it could usher in reforms to improve transparency.
Lottner said Vietnam’s banks can help develop the capital markets in a responsible way. “We’re sometimes unintentionally misselling, or products may not be explained the right way, and then you have people who are getting bad experiences,” he said.
“And then you have social media amplifying perceptions like retiring at the age of 25, or products that give you 50 per cent return in 6 months… I think a lot of the demand we get from our customers is actually in financial education,” he said.
This is especially so for Techcombank, which has been expanding its client base into the mass retail market. While Lottner expects the profit pool in retail banking to continue sitting with mass-affluent clients in the next 5 years, he said it is important for the bank to start establishing relationships with prospective customers at the lower end given the country’s fast growing economy and emerging middle class.
At the end of last year, the Asian Development Bank projected that Vietnam will have the highest growth rate among Asean nations this year at 6.5 per cent.
Techcombank is exploring cooperation areas with partners, including consumer conglomerate Masan Group, and hopes to acquire up to 1.5 million new customers each year.
The bank logged 5.5 trillion dong (S$323 million) in net profit in the first quarter of 2022, up 25 per cent year on year. Interest income climbed 32.5 per cent for the quarter while income from service activities went up 24.1 per cent. Its customer base had also more than doubled from the year-ago period.
Shares of Techcombank ended down 0.81 per cent at 36,850 dong on Wednesday (Jun 1).
While much has been said about how fintech companies may be disrupting banks, Lottner said Techcombank is facing more competition from incumbents in the region looking to expand into Vietnam – such as Singapore’s UOB.
Earlier this year, UOB announced it would acquire Citibank’s consumer business in 4 Asean countries: Vietnam, Malaysia, Thailand, and Indonesia.
“The UOBs of all over the world will also look very much into these (emerging) markets as an opportunity,” Lottner said. “We expect these banks to be in that market over the next couple of years in full force with all their capabilities. So the bar goes up for all of us.”
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

What role can Japan play in Asean’s future?

