

Wirecard shutdown leaves some complacent merchants stranded
Wishful thinking, aversion to change, difficult IT systems also cited for firms like M1, Safra, Starbucks scrambling to find alternatives
Singapore
COMPLACENCY, resistance to change and wishful thinking were what led to some large businesses being left high and dry by Wirecard's cessation of its payments-processing services in Singapore last week, industry watchers say.
These merchants, including M1, Safra and Starbucks, are now scrambling to find alternative service providers, although warning bells had started sounding in June, when Wirecard collapsed into insolvency.
The Monetary Authority of Singapore (MAS) had on Oct 1 ordered Wirecard entities in Singapore to cease its payment services, after the German firm said it was unable to continue providing services to a "significant" number of merchants.
Thousands of merchants in Singapore were users of Wirecard's payment terminals, but it is unclear how many have made alternative arrangements.
Aurobindo Ghosh, assistant professor of finance at the Singapore Management University, said that some of these major retailers had indulged in "some level of wishful thinking" - that other players could acquire the Wirecard business in Singapore.
They might also have been hoping that the Singapore arm of Wirecard - which handled as much as 45 per cent of the payment player's overall business - might be able to pull through, added Professor Ghosh, who is also the programme director of Citi-SMU Financial Literacy Programme for Young Adults.
He also pointed out that these larger retailers, who had spent money to customise Wirecard payments solutions for their business, would have been reluctant to change their system, given that retailers big and small were already under price pressures.
Andrew Tan, managing partner of retail consultancy atomi Consulting, said larger merchants usually integrate their payment gateways into their IT systems, which are "massive and complex".
"Often, there is a lot of customisation done for larger merchants."
It would therefore take months to find another service provider, negotiate a contract, execute the change in the system and migrate it, said Mr Tan, who also co-owns lifestyle retailer atomi.
The time taken to switch providers varies according to complexity.
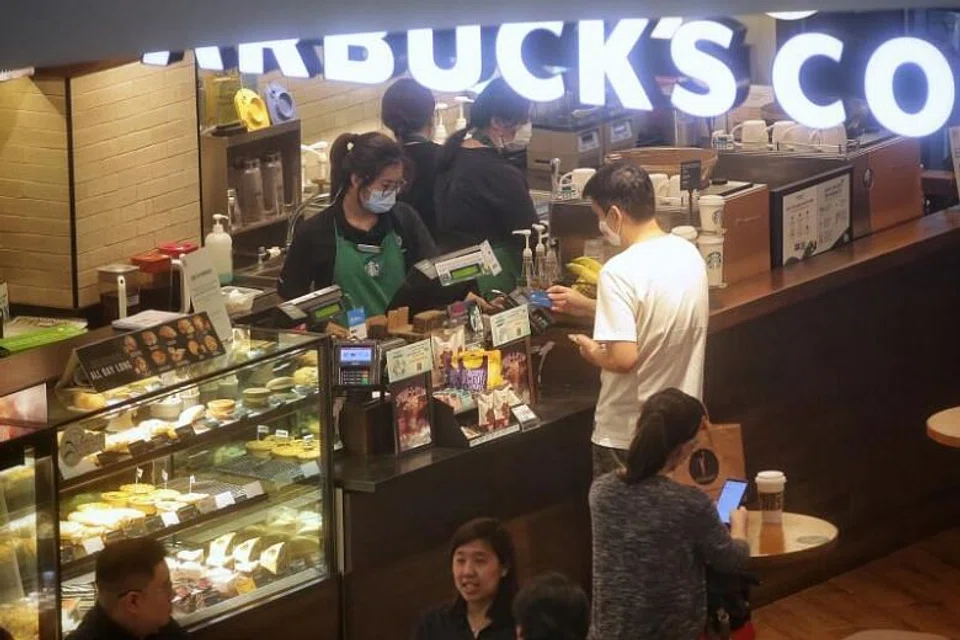
A spokesperson from Starbucks Singapore told The Business Times that the coffee chain has resolved issues with the payment terminals in its stores in less than a week; it is, however, still troubleshooting its online and in-app payments.
Starbucks customers, encountering payment terminals in the stores being down, have taken to social media to vent their frustration.
Price point may also have been a reason behind the failure to switch from Wirecard before the disruption.
Mr Tan said fintechs like Wirecard may offer merchants a lower price than other competing systems. BT understands that smaller fintech players typically charge lower rates; in some cases, some undercut rates to the point of being loss-making in order to build market share.
But Mr Tan said complacency plays a part in explaining why some retailers did not act fast enough.
"The larger companies are very much resistant to changes, especially those with large footprints, outlets and complex IT systems.
"Ultimately, it means extra work and many are resisting the need to do this so unless forced to, which is what's happening now."
Several large merchants are now switching providers following disruptions to their payment services.
In an e-mail to customers on Friday, M1 said that its monthly recurring-payment mode is temporarily unavailable because of Wirecard ceasing its services.
In the meantime, customers can pay their bills via AXS, PayNow and the My M1 app. "We're working on it and will update you once your recurring-payment arrangement is back," said M1.
In response to queries from BT, the telco said it is working with a local bank and an alternative payment gateway service provider to handle the credit card bill payments which have been disrupted.
"This process has been expedited and is expected to be ready in two weeks," it added.
Safra, via an alert on its website and e-mail to members on Friday, said all online payment services have been temporarily suspended because of Wirecard's exit, and that members may visit Safra clubhouses for transaction matters.
"Safra is working expediently to reinstate the online payment and will provide a status update in due course," it said.
Wirecard became a well-known payments player in the Asia-Pacific after acquiring the customer portfolio of Citigroup's merchant acquiring business. Following that 2017 announcement, Wirecard said its merchant-clients in Singapore, Hong Kong, Macau, Malaysia, Taiwan, Indonesia, the Philippines, Thailand, India, Australia and New Zealand numbered more than 20,000.
Prof Ghosh said: "Bigger businesses have to possibly invest in building in-house capabilities or look for smaller fintech providers.
"Having said that, this is providing space for smaller players to fill in the void left by the collapse of Wirecard."
Even as the disruption to affected businesses is likely short-term, observers say that the Wirecard debacle should be a good lesson; Mr Tan said it is best practice to plan for an alternative digital payment gateway, even if it is a daunting task.
Prof Ghosh agreed on the need to build redundancies in the system, even though it is not easy and may be a strain for small and medium-sized enterprises with limited resources.
On a higher level, he emphasised the importance of regulation and corporate governance in fintech firms.
"In an often winner-takes-all setup in a hyper-competitive landscape striving for efficiency, both redundancy and corporate governance might take a back seat," he noted.
TRENDING NOW

Why US$100 oil, 5% US yields affect Singdollar, ringgit differently vs other Asean currencies

Anthropic to open Singapore office in October, sees it as ‘standout market’ for Claude

Singapore’s covered bond boom is largely a DBS story

Malaysian developer Eco World tops bids for Sin Ming area housing plot with S$1,612 psf ppr offer

