Analysts keeping faith with pure-play China S-Reits
Firms with exposure to China may also be grappling with negative sentiment due to geopolitical risks, says UOB Kay Hian's Adrian Loh
Singapore
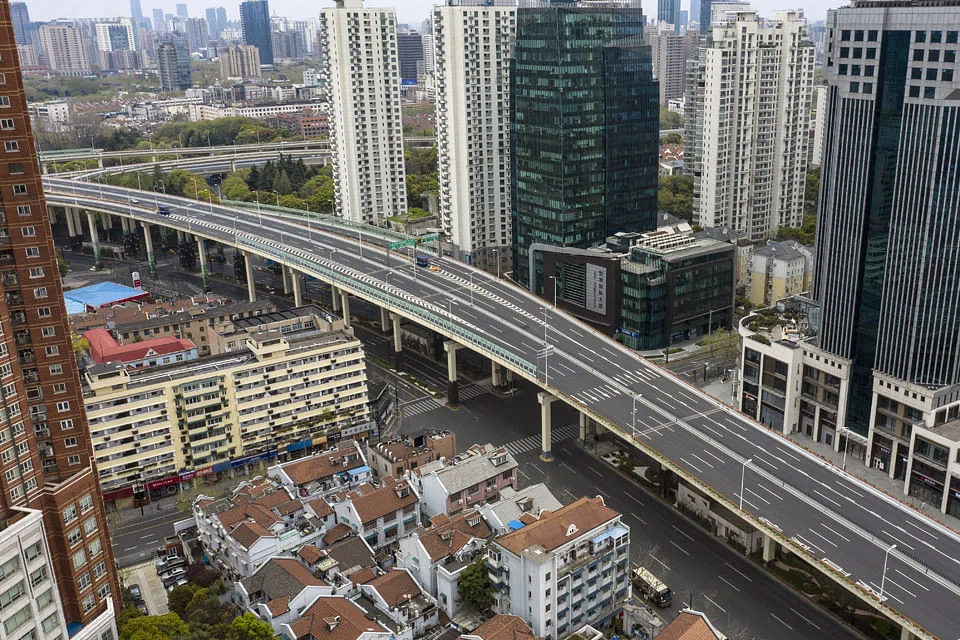
SINGAPORE-listed real estate investment trusts (S-Reits) with assets in China have suffered a beating as Beijing imposed widespread lockdowns to contain a resurgence of the coronavirus.
The Singapore Exchange has 5 S-Reits - CapitaLand China Trust (CLCT), Sasseur Reit, EC World Reit (ECW), BHG Retail Reit and Dasin Retail Trust - with pure exposure to China. Of these, 4 are trading underwater.
"With sustained outbreaks in two-thirds of the country's provinces, China's zero-tolerance policy towards Covid-19 is now facing its toughest test yet since the coronavirus first emerged more than 2 years ago in Wuhan," said UOB Kay Hian analyst Adrian Loh.
"As in prior periods of market uncertainty, investors tend to 'sell first and ask questions later', especially in an environment where news flow appears to be overwhelmingly negative," he added in a recent strategy note.
The worst-hit has been Dasin Retail Trust, which has tumbled 16.2 per cent year-to-date. The trust in March entered into a non-binding memorandum of understanding for the potential divestment of 2 of its 7 retail mall properties.
Sasseur Reit, ECW and BHG Retail Reit have lost between 0.6 and 9.8 per cent in the year to date.
CLCT has managed to tread water, with the counter up 1.7 per cent so far this year.
In contrast, the benchmark Straits Times Index has gained 9 per cent in the year to date.
"China at this juncture is exercising targeted lockdowns to control the spread of Covid-19, with Shanghai currently being the epicentre and most severely impacted," RHB analyst Vijay Natarajan told The Business Times.
However, Natarajan does not expect any material impact on the China pure-play S-Reits from these Shanghai-centred lockdowns.
He noted that only CLCT has about a direct 3 per cent exposure to Shanghai via its logistics asset, which is deemed a more resilient asset class. "The broader impact to China-focused S-Reits is likely to be from the consequence of economic slowdown on the back of China's zero-Covid policy, which at this juncture is harder to quantify," Natarajan said.
"We are currently 'neutral' on China pure-play S-Reits as we see the risks balanced by some signalling of government policy support," he added. "We see a good possibility of the Chinese government using more of its policy levers to support the economy, offset some of the weakness and propel GDP growth."
Apart from Covid-19 outbreaks and lockdowns, UOB Kay Hian's Loh said companies with exposure to China may also be grappling with negative investor sentiment due to issues such as the Russia-Ukraine war, inflation concerns, US Federal Reserve rate hikes and increased policy risks in the Chinese technology sector.
As things stand, however, Loh believes it is still too early to cut the earnings estimates for companies with exposure to China.
"We have not made any changes to our earnings forecasts as we believe that the impact at present would be mild," he said. "However, the Russia-Ukraine conflict and the worsening domestic pandemic may warrant a more cautious outlook as the country's 'dynamic zero-Covid' policy will impose significant costs to the economy."
Natarajan points out that one of the geopolitical risks arising from the Russia-Ukraine war is the possibility of secondary sanctions imposed by the West on China.
"This - if implemented and depending on its scale - will have a sharp impact on economic growth. It will consequently have an adverse impact on business outlook for China-focused Reits and result in lower valuation," he said.
However, Natarajan opines that this is an unlikely scenario. "We assess this risk to be low as this in turn will come with a severe consequence of slowing global GDP growth and likely to lead to a recessionary environment," he added.