

Analysts say SIA is fairly valued, with several adjusting target price
Their projections for FY2026 net profit range from S$900 million to S$1.4 billion
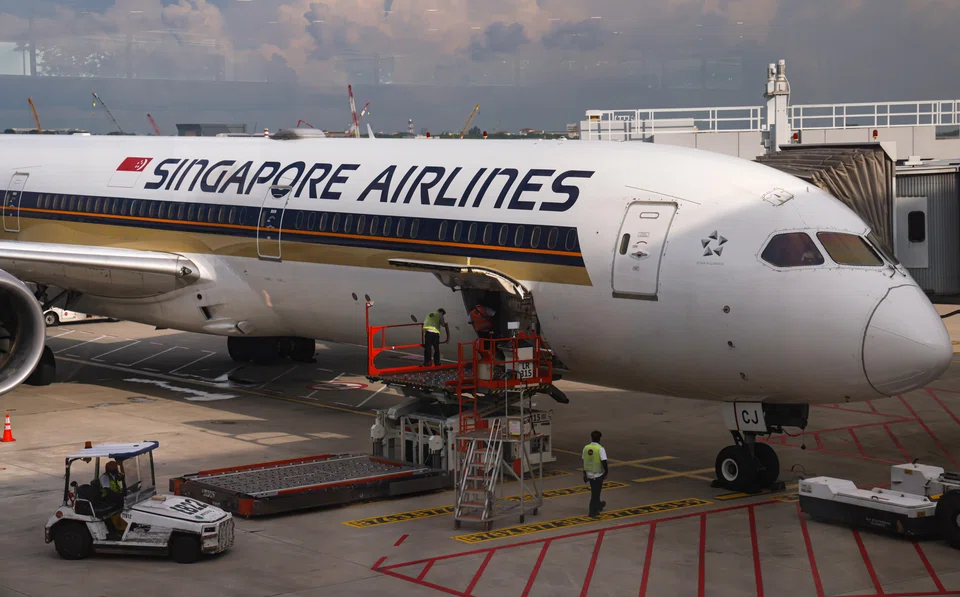
[SINGAPORE] Analysts have commented that the share price of Singapore Airlines (SIA) is fairly valued at the moment, even as several lifted their target price and recommended a “hold” on the stock, after the airline group published its FY2025 results.
Their projections for FY2026 net profit range from S$900 million to S$1.4 billion.
On May 15, SIA announced a 3.9 per cent rise in its bottom line to a record S$2.8 billion for the full year, boosted by a one-off, non-cash gain of S$1.1 billion from the Air India-Vistara merger. Revenue was at S$19.6 billion, up 2.8 per cent.
Analysts from CGS International, DBS, UOB Kay Hian (UOBKH) and OCBC all raised their target price for the airline group to a range of S$6.40 to S$6.88, but Lorraine Tan of Morningstar cut her fair value projection by 5 per cent to S$6.10.
Tan expects SIA’s operating margin cut to 4.7 per cent and 7.4 per cent for FY2026 and FY2027, respectively, from 8.7 per cent in FY2025 and 14.7 per cent in FY2024, as yields continue to normalise amid supply increases. Current yields, however, remain over 10 per cent above pre-pandemic levels.
She lowered her target price to S$6.10 to reflect lower near-term profitability, but she flagged that SIA’s yields and load factors could be hit by the low-cost offerings of Chinese carriers as they ramp up their international route capacity.
Her FY2026 net profit forecast is about S$900 million.
CGS’ Raymond Yap expects that SIA could benefit from the drop in Brent oil price and an appreciation in the Singapore dollar against the greenback, as he adjusted SIA target price from S$6 to S$6.88.
He said Brent price decreased to US$66 a barrel in April to May from US$76 a barrel in January to March, while the Singapore dollar rose to S$1.30 against the greenback currently, from S$1.34 on Mar 31.
However, he reduced the cargo and passenger yield assumptions for SIA, as the global business uncertainty brought about by the US “Liberation Day” tariffs will eventually moderate business travel and cargo demand, and flagged this as the key downside risk for the quarter ending September.
Yap’s FY2026 net profit estimate is about S$1.2 billion.
Analysts from DBS projected cargo could remain more resilient than previously anticipated, as they pointed out that SIA’s cargo volumes rose 4 per cent year on year in April, despite trade frictions between the US and its trading partners, and global freight market volatility.
They expect the US-China truce in the tariff war to spark front-loading of shipments in the coming months. They said this might lead to upside surprises in cargo volumes and yields as SIA derives about 11 per cent of its revenue from cargo, and its US cargo exposure is about 8 per cent.
DBS’ FY2026 net profit projection is about S$1.1 billion
UOBKH expects SIA’s FY2026 core net profit to drop 8 per cent year on year, as it will reflect the full-year impact of Air India’s negative contribution while the Indian airline undergoes a multi-year turnaround, with limited visibility on its profitability timeline.
However, the analyst expects SIA to generate S$1.4 billion in net profit for FY2026.
In 2024, Vistara was merged with Air India, resulting in SIA holding a 25.1 per cent share in the merged entity.
OCBC raised SIA’s target price to S$6.80 from S$6.50, and projects the airline group’s bottom line to be about S$1.2 billion for FY2026.
SIA shares were trading 0.3 per cent of S$0.02 higher at S$6.90 at 1.24 pm on Monday.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Singapore judge raises doubts iron ore trader Radiant World is owed US$1 billion

