Asia holds promise for banks amid China reopening, says StanChart CEO Bill Winters
Tan Nai Lun
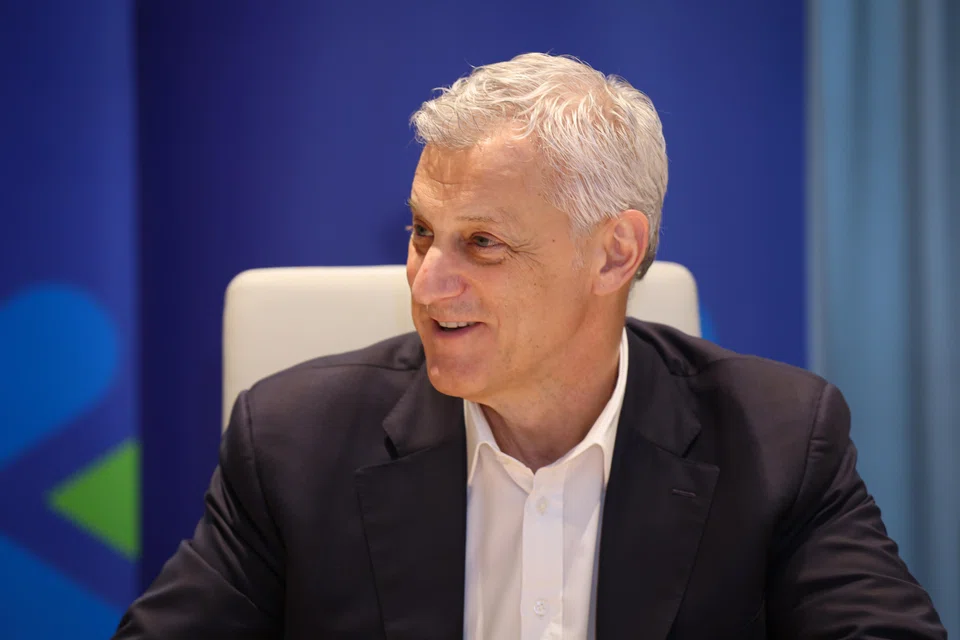
STANDARD Chartered group chief executive Bill Winters sees China’s reopening playing a meaningful part in the bank’s growth this year.
Arriving in Singapore after his visit to China, Winters added that regional economic activity remains robust in spite of the recent banking crisis.
“Thankfully, we are in quite good shape from a credit perspective,” he said in a media briefing on Monday (Apr 3). Here are some excerpts from the interview:
What are the growth opportunities for Standard Chartered in Singapore and Asia?
Trade, especially within the Asian region, is picking up very nicely. Chinese manufacturers are diversifying their manufacturing into Vietnam, Indonesia, Malaysia, or even India. We have a big market share backing companies in those countries, so it’s a big boost for us.
We also have a strategic objective to increase our penetration of the financial institutions market.
In the Asean region and Greater China, savings rates are high, but investing rates are still relatively low. We would like to be part of helping to institutionalise those savings better across China.
How has the banking crisis affected your business?
There is going to be less value attributed to Additional Tier-1 (AT1) debt, which does increase the cost of capital for a bank.
Bank shareholders, AT1 investors, and bondholders may also find it a lot riskier now (to invest in banks).
Every bank, no matter how well-funded or how strong the deposit base, may find that they need to be a little bit stronger. Maybe that increases competition for deposits, which then decreases the net interest margin for banks, which reduces profits.
Have you seen clients moving from UBS or Credit Suisse to you?
We had seen continued momentum in the early part of this year, which was consistent with a very strong finish to 2022.
There’s been a pretty major change in the private banking market – Credit Suisse was a very big private bank – although not too big in the mass affluent market, which is our sweet spot.
But we also know that there’s been a steady stream of money moving into Hong Kong and Singapore... with a surplus of liquidity in Hong Kong.
Singapore has become a target and magnet for wealthy people from everywhere, including for China. And we’re in banking, so we’re getting our share of that.
What are the other growth drivers for Singapore and Asia?
A third of our corporate business still comes from US and European clients, but their investments are coming back (to Asia).
While a slowdown in the United States or Europe is a bit of a concern, there’s a silver lining.
The bad news: If our corporate clients and the financial institutions have a less robust operating environment in their home market, that could suppress their overall investment activity.
The good news: The marginal investment is coming into the fast-growth markets, and Asean as a bloc is contributing as much to global growth as either India or China.
We don’t wish for a recession in the US or Europe – that’s not good for the world. But on the margin, we’ll probably relatively benefit from that.