

Asia’s largest Reit looks to get even bigger as it expands outside of Hong Kong
George Hongchoy, CEO of the manager of Link Reit, sees opportunity to acquire assets in times of crisis
Jude Chan
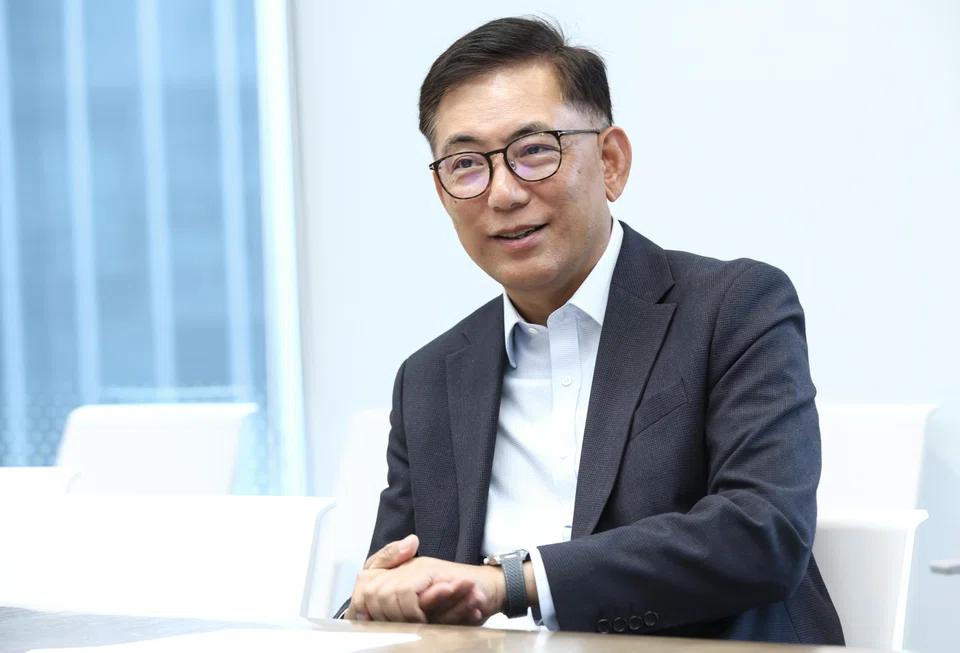
HONG KONG-LISTED Link Real Estate Investment Trust (Link Reit), which announced its entry into Singapore as 2022 was drawing to a close, is raring to sink its teeth into more asset acquisitions as it continues to diversify.
The Reit came to market in 2005 with an initial public offering (IPO) portfolio of 180 shopping centres and car parks located in Hong Kong.
A decade later, in 2015, it made its first foray out of the port city into mainland China.
Since then, it has branched into overseas markets in Australia and the UK – and now, Singapore. It also expanded its portfolio to include office and logistics assets.
Link Reit’s total portfolio value now stands at about HK$246 billion (S$41.5 billion). Nearly three quarters of this is based in Hong Kong, with another 15 per cent in mainland China.
“Geographically, we’ll probably want to get Hong Kong from 70-odd per cent to closer to 50-odd per cent, so there’s still a fair bit of movement that we need to achieve,” said George Hongchoy, chief executive officer of Link Reit’s manager.
The Reit manager envisions that mainland China assets will continue to account for about 15 per cent of its portfolio, while it deepens its footprint in the other markets it has already taken a foothold in.
Apart from these geographies, Hongchoy says Link Reit is also looking at opportunities in Japan.
“We tend to go to the more mature markets,” Hongchoy said, adding that the team considers factors such as pricing, growth trajectory and the liquidity of the property markets.
“A good investor always thinks about whether you can sell if you want to buy, because you never know,” he said. “There’s a lot of room in this region in the cities that are mentioned to continue to build a portfolio. So that’s our aspiration.”
Sweeping into Singapore
Link Reit on Dec 28, 2022, announced its maiden entry into Singapore with the acquisition of two retail malls – Jurong Point and Swing By @ Thomson Plaza – from NTUC unit Mercatus Co-operative for S$2.16 billion.
As part of the transaction, Link will enter into a 10-year asset and property management service agreement for a third suburban retail mall, AMK Hub, which will remain under Mercatus’ ownership.
Link Reit will also retain the existing teams of some 140 staff managing the properties, giving the Reit the opportunity to build its in-market capability almost immediately.
Before this, the Reit only had one employee based in Singapore, who was tasked with looking at acquisition opportunities.
“We are a little bit different from the competitors in this particular deal that we’ve heard off. Most of them, or all of them, are local players. They already have a team, so they wouldn’t value having another 140-odd people as much as we do,” Hongchoy said.
According to Citi analyst Ken Yeung, the deal will be accretive to net property income (NPI) and distribution per unit (DPU).
“Annualised NPI (of the two properties for 2022) represents a yield of 4.9 per cent based on the acquisition price, which we believe is attractive due to its relatively short weighted average lease expiry (WALE), with strong Singapore retail outlook post-Covid,” Yeung said.
He added that the asset and property management service agreements for AMK Hub should also start to provide recurring asset-light income to Link Reit.
Citi is keeping its “buy” call on Link Reit and raising its target price by 1.5 per cent to HK$66.50 to reflect the DPU accretion arising from the acquisition. Units of Link Reit last closed at HK$61.45 on Jan 13.
The deal, which will be fully funded through Link Reit’s internal cash resources and debt facilities, will bring its aggregate level ratio to 27.1 per cent, from 23.2 per cent previously.
This still gives Link Reit plenty of debt headroom before hitting the regulatory limit of 50 per cent.
In Singapore, the Reit manager is also eyeing the potential acquisition of Nex shopping mall, which was reported to have been part of the bundle of four retail assets initially put up for sale by Mercatus for a total of S$4 billion.
“(Nex) is a good asset,” Hongchoy said. “We’ll definitely want to look at it… (but) we need the seller to be interested.”
Link Reit’s diversification, including to Singapore, is also part of the Reit manager’s strategy to hedge against foreign currency volatility.
“In Hong Kong, because of our currency peg, we have to follow whatever the US Federal Reserve decides,” Hongchoy said. “They don’t think about us when they are coming up with decisions, so interest rates might go up at the time when we actually need interest rates to come down.”
“Part of the reason for diversification is that you don’t want everything to move in the same way,” he added. “Because you could be doing a fantastic job managing the malls – revenue keeps going up – but currency just takes it all off.”
Staying competitive
Hongchoy says that Link Reit has brought “quite a few senior executives” on board to help it grow its portfolio assets.
“Some would say ‘oh, the market is going down, why don’t you wait until it goes up before you do anything?’. But when everyone knows that everything’s going up, then no one wants to sell to you,” he said.
“It is always during these sort of crisis times, at the bottom, that you can find something and hopefully you can improve on it,” he added.
That said, Hongchoy says the Reit manager is “very selective” about its acquisitions and leaning towards prudence on the capital management front.
Link Reit is rated A2/Stable by credit rating agency Moody’s Investors Services, as well as A/Stable by both S&P Global Ratings and Fitch Ratings. And Hongchoy intends to keep it that way.
The Reit manager says Link Reit’s size and credit rating have helped it be more competitive when vying for assets. Link Reit is the largest Reit in Asia with a market capitalisation of HK$130.8 billion as at Jan 12.
“We’ve been cautious,” Hongchoy said. “Our size and credit rating has helped us to get a lower cost of funding, so that at time of transaction, hopefully we are more competitive than the other bidders… and maybe win some good assets.”
In a recent report, S&P Global Ratings said the Singapore malls acquisition could limit Link Reit’s capacity to absorb any hits to its business in a volatile market environment.
“With the ratio moving closer to our downside trigger of 30 per cent, the Reit’s funding structure is moving to a greater debt weighting, bringing higher financial risk,” the credit ratings agency said.
However, it added that the high quality of the assets, which will provide stable recurring income, partly tempers that risk.
The way Hongchoy sees it, there are four broad types of investors in Link Reit: income investors, index investors, real estate funds, and retail investors.
“Each one of them wants us to do different things,” Hongchoy said.
For example, he says, real estate funds do not like the Reits to diversify as they prefer to do it themselves, while the income investors push for income growth at all costs.
With a 100 per cent free float as the Reit does not have a sponsor, he adds that Link Reit also enjoys a sizeable weightage in indices as a real estate exposure.
“We just need to balance (what each of these investors wants),” Hongchoy said. “Over the last few years, it seems like the income funds are winning. They say ‘please just keep growing’ – and we’ve been delivering.”
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Floods compound Philippine growth woes from public-works scandal

Tokyo reverses baby bust with AI matchmaking and generous subsidies
More interest in ETFs, low-cost funds but Singapore still lacks pressure to further lower fund fees

