

Australia’s plan to scrap AT1 bonds unlikely to affect Singapore banks
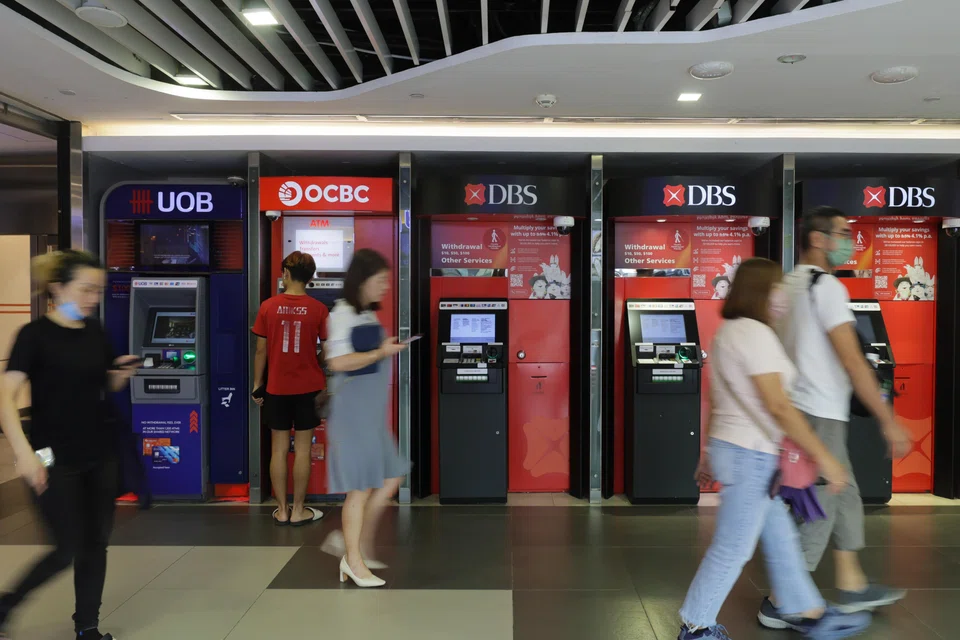
SINGAPORE banks are unlikely to face any near-term impact from a proposal by Australia’s banking regulator to phase out the use of additional tier-1 (AT1) bonds, analysts said.
The local banks will only be affected if Singapore’s regulators follow suit, but analysts said this is unlikely to happen given the nature of investors in Singapore that invest in AT1s versus Australia.
AT1 bonds are bank debt that form part of a lender’s capital. They are often regarded as a riskier investment as they rank lower in the order of claims than ordinary bonds when a financial institution fails.
On Sep 10, the Australian Prudential Regulation Authority proposed that banks phase out the use of AT1 bonds to strengthen the financial system in the event of a failure.
The move comes after several banks in the US and Europe failed or needed intervention last year. In particular, the collapse of Credit Suisse wiped out around US$17 billion in AT1s when the Swiss government engineered a takeover by UBS.
Under Australia’s proposal, the large banks will be able to replace their AT1s with tier 2 (T2) capital or common equity tier 1 (CET-1) capital, while smaller lenders can fully replace AT1s with T2 instruments.
Eugene Tarzimanov, a senior vice-president at Moody’s Ratings, noted that Australia is primarily addressing the issues of having retail investors hold bail-in securities, and the potential for contagion if they are bailed-in.
In contrast, retail investors are not allowed to invest in AT1s of Singapore banks unless they are qualified investors.
Similarly, Michael Makdad, a senior equity strategist at Morningstar, said the Monetary Authority of Singapore (MAS) is unlikely to follow suit as AT1 bonds in Singapore have only been sold in the wholesale market, with no offerings to retail investors in Singapore.
“Investors in the wholesale market should be sophisticated enough to understand the risks involved in owning AT1 securities,” he said.
Even if MAS were to hypothetically propose the phase out of AT1s in favour of more CET-1 and T2 capital as Australia is doing, Makdad said the local banks will not have much difficulty dealing with the change.
As at Jun 30, AT1 capital accounted for 0.6 per cent of DBS’ risk assets, 0.7 per cent of OCBC’s, and 1 per cent of UOB’s.
Moving AT1 capital to CET-1 may slightly reduce the amount of future earnings available for dividends, but the Singaporean banks already have ample CET-1 capital, Makdad said.
This is because Singapore’s lenders rely less on AT1s for capital adequacy due to solid core capital, said Rena Kwok, credit analyst at Bloomberg Intelligence.
Kwok noted that Singapore’s regulators are following global guidelines to allow AT1 issuance of up to 1.5 per cent of a bank’s risk-weighted assets, and she does not expect the Basel Committee will eliminate AT1s.
Tarzimanov said the longer-term issue is whether the design of current AT1 securities has reduced their effectiveness as going-concern capital.
Different regulators may have diverging views on the relevance of AT1 securities in the context of their domestic markets.
Yet, there have been many examples of banks around the world that have continued to issue such bonds in the wake of the Credit Suisse write-down, said Willie Tanoto, senior director of Asia-Pacific banks at Fitch Ratings.
In Singapore, this includes OCBC – which issued bonds in August 2023 and January 2024 that were fully subscribed – as well as other foreign banks that have opted to tap the Singapore dollar market.
“This suggests the economics of issuance continues to make sense within the issuers’ capital management plans and that there is sufficient investor appetite to absorb them,” Tanoto said.
Furthermore, he noted that none of the AT1 capital issued by the local banks were issued in Australia or denominated in Australian dollars, which means the possible phase-out will not have a material impact on their capital planning.






