

BT Explains: What are stablecoins and CBDCs?
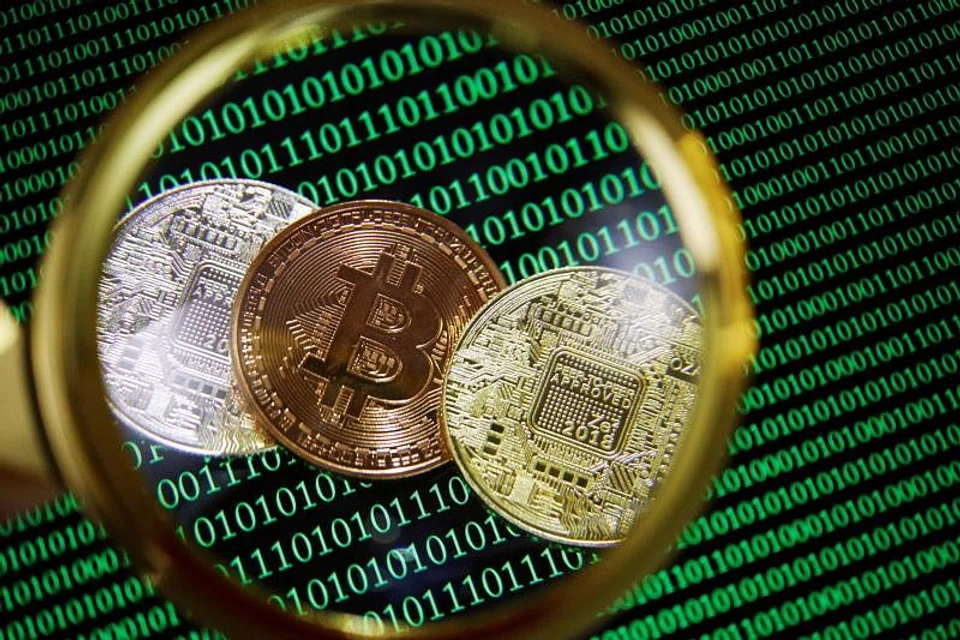
STABLECOINS have been on a tear of late, with growing global acceptance of cryptocurrencies driving their rise. They have also caught the attention of lawmakers around the world, who are urging regulatory frameworks for this broad class of digital currencies.
At the start of 2021, the total global supply of stablecoins was worth about US$29 billion, according to data from The Block, which publishes research in the digital asset space. This figure has risen to US$128 billion within 10 months, as at October 20.
At the Asia Financial Markets Forum last week, the chairman of Singapore's central bank Tharman Shanmugaratnam said "there may be a role for crypto in future finance that extends beyond pure speculation and illicit finance". (see clarification note)
In September, the US Securities and Exchange Commission Chair Gary Gensler likened stablecoins to "poker chips at the casino" which can hurt people without stronger oversight, while the US Federal Reserve chair Jerome Powell in July issued an urgent call for regulation of stablecoins.
What are stablecoins?
Cryptocurrencies are infamous for their volatility which, arguably, is a primary obstacle to them becoming more widely used. Stablecoins are a form of digital currency, first created in the early 2010s, to overcome this hurdle.
"Stable" coins are thus named because their market values are pegged to real-world assets, such as fiat or commodities, such as gold and platinum. Some are collateralised by a basket of cryptocurrencies. Think of them as currencies that offer the benefits of instant processing, like crypto, but with the stability of fiat money.
Tether, or USDT, which is pegged to the US dollar, is the largest stablecoin by market capitalisation - around US$69 billion, as at October 20. But the opacity of its reserves has been the subject of great controversy.
The Singapore dollar-pegged stablecoin XSGD has also risen to US$108 million since its launch in October 2020. About S$1.8 billion in XSGD have been transacted over the past year.
Benefits
Although much of our cash is currently already "digital" - in that our financial transactions are conducted via electronic means - stablecoins are seen as an even more efficient, cheaper and frictionless alternative for cross-border transactions because they run on the blockchain. As there is no need for intermediaries, they could help connect unbanked or underbanked segments to the financial system.
Stablecoins are also used as a place to store value when investors exit crypto trades and for margin trading.
Another useful feature of stablecoins is that they can be controlled by "smart contracts" on the blockchain which, unlike conventional contracts, do not require legal authority to be executed. This makes stablecoins programmable in ways that dollars can't be. This can make it easier for governments to run conditional cash transfer programmes, or even for devices to send money to each other. Aymeric Salley, managing director of digital assets platform StraitsX which issues the XSGD stablecoins, explains: "This example usually scares people a little bit. But if you take existing innovations, say an Uber, a Tesla and a stablecoin, and combine them together. You can build a 'self-owning taxi', meaning it will take a person from points A to B, collect money from the customer, and then use this money to get recharged at a station, change its tyres, and maintain the car. All without a driver."
Not that stable after all?
Despite their potential, many urge caution over being too bullish on this asset class.
As stablecoins are not regulated in most parts of the world, there are concerns that they be used to skirt capital controls, so as to facilitate illicit activities.
UOB's head of markets strategy Heng Koon How said: "There are legitimate concerns by regulators in regard to the lack of transparency and questionable integrity of the reserves backing the stablecoins as well as their potential to facilitate criminal and illegal fund transfers."
Concerns over stablecoins mostly centre on the opacity of their reserves. One such controversy centres on Tether, which launched in 2014 and is pegged 1:1 to the US dollar. The stablecoin has faced intense regulatory and media scrutiny in recent years around the questions of how exactly it is backed, or if it's truly backed at all. There are now 69 billion Tethers in circulation, with 48 billion of them issued this year, according to a Bloomberg report in early October.
Early this year, Tether and Bitfinex, its crypto exchange partner, were fined US$18.5 million in a legal battle launched the New York state, alleging that the companies moved hundreds of millions of dollars to cover up the apparent loss of US$850 million of commingled client and corporate funds.
Tether revealed the breakdown of its reserves for the first time in March 2021 - as part of its efforts to comply with its settlement agreement with the New York Attorney General - suggesting that commercial paper represents about half of its collateral. But it declined to give further details despite queries from various journalists.
Apart from questions surrounding reserves, there are also concerns that privately issued stablecoins could spiral into worthlessness, for instance, if the companies behind them collapse.
Central bank digital currencies
Meanwhile, central banks have stepped up efforts to explore their own stable digital currencies. The Bank of International Settlements' (BIS) poll of 65 global central banks in February 2021 found that 86 per cent were exploring central bank digital currencies (CBDCs). Seven out of 8 central banks with advanced CBDC pilots are in emerging markets.
Unlike privately-issued stablecoins, CBDCs are virtual forms of a country's official currency, issued and regulated by the nation's central bank. Some efforts to create CBDCs have been prompted by regulators' reservations about the impact of privately-issued stablecoins on financial stability and traditional monetary policy.
China is the forerunner in CBDC development and has over the past year held various public trials of its digital yuan. Notably, the digital yuan will be used in a large public trial next February, during the Beijing Winter Olympics.
In Singapore, the MAS has over the years conducted various experiments on the use of blockchain and digital ledger technology. In July, the authority partnered the BIS and the central banks of Australia, Malaysia and South Africa in an initiative dubbed Project Dunbar, to build a common platform for direct cross-border transfers using CBDCs. It has also launched a global competition asking for proposals around use-cases for retail CBDCs.
Ultimately, whether CBDCs and stablecoins can coexist will be determined, largely, by the forces of regulation and adoption.
McKinsey's Ian De Bode, Matt Higginson, and Marc Niederkorn wrote in an article published in October: "While it is too early to predict the impact of greater regulation on stablecoins, innovation continues apace with the likely emergence of many more (and newer) varieties in coming years. In contrast, early efforts to issue CBDCs have been met with only moderate adoption."
Clarification note: The story has been clarified to quote SM Tharman as saying that "there may be a role for crypto in future finance that extends beyond pure speculation and illicit finance".
READ MORE: Singapore sees promise in a crypto economy
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Income Insurance appoints former Manulife Singapore top man as new CEO

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

