

Bullion dealer matches more than S$8 million in P2P loans
Singapore
IT'S peer-to-peer (P2P) lending with a sparkly twist.
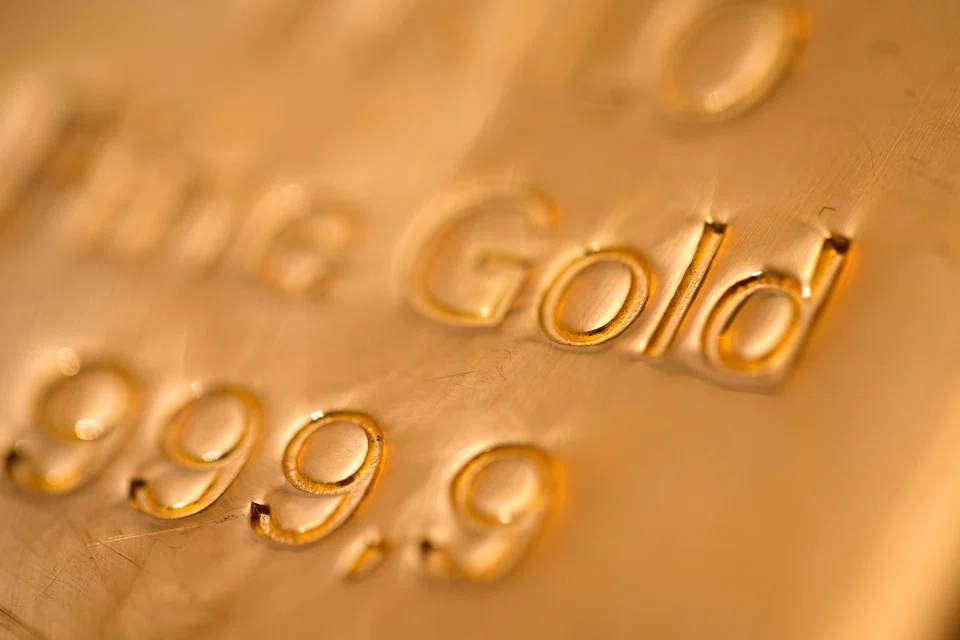
Silver Bullion, a Singapore-based bullion dealer, has matched more than S$8 million in P2P bullion-backed loans since August 2015, underscoring the rising popularity of P2P lending.
Owners of physical gold and silver who store their bullion at Silver Bullion's vault located in the east have matched 300 loans through the lending platform, it said on Wednesday.
Vergel Villasoto, a director of Silver Bullion, said: "We are seeing increasing borrowing demand on our P2P loan platform.
"More bullion owners now realise that they would not need to sell their gold or silver to raise funds. They can borrow much-needed funds in the short term using their bullion as collateral, while continuing to own their bullion and benefit from potential capital gain as with the recent rise in precious metals prices."
Such loans are fully backed by physical gold and silver, and lending that stretches beyond six months have a collateral-to-loan value of at least 200 per cent. This means that a loan of S$100,000 must be backed by a collateral worth at least S$200,000. The exceptions are loans with a one-month tenure, which have a collateral-to-loan value of 160 per cent.
If the value of the collateral falls to 125 per cent, borrowers receive a margin call. At 110 per cent, borrowers will have their collateral liquidated.
Borrowers can set their interest rate when submitting a borrowing request or can match an existing lending offer if the terms are acceptable to them. The site showed six-month lending offers for S$25,000 at 5.5 per cent per annum.
Individual lenders need to register an account with Silver Bullion, though they do not have to store gold or silver to lend money, a spokesman told The Business Times. Both lenders and borrowers are charged a 0.5 per cent fee on the principal.
No borrower has defaulted, or paid later than they should. When a borrower is late, the company charges the borrower a late penalty of 1.5 per cent of the outstanding balance on the due date and every subsequent loan start date, until the full amount is repaid. The funds repaid by the borrower will go back to the sweeper's fund. The company taps this fund to pay lenders when borrowers are late.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Seatrium allocates S$200 million for new share buyback programme

32 companies, 6 individuals bag accolades at Singapore Corporate Awards 2026
Stocks to watch: Mapletree Logistics Trust, Seatrium, Keppel DC Reit, Food Empire

