

NTUC Income's corporatisation: striking a balance between profits and purpose
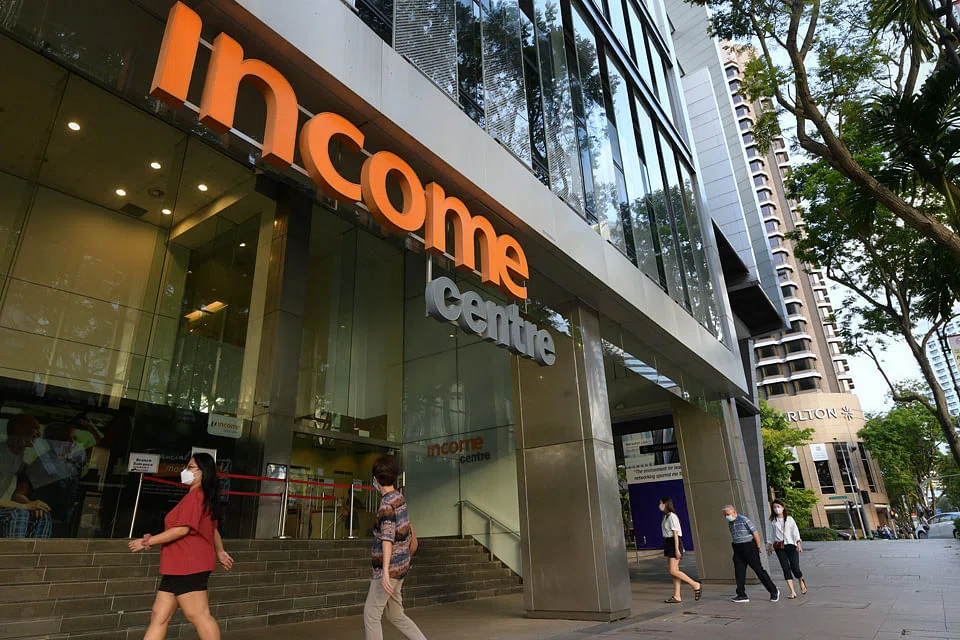
NTUC Income's proposed corporatisation, announced last week, is a startling development for a co-operative which hews closely to its social purpose of catering to the underserved in Singapore.
The big question is whether corporatisation would dilute its social mission. For the co-op's members, whose co-op shares will be converted into equivalent shares in the new entity, Income Insurance Ltd, a corporate structure offers the potential of more generous dividends and a higher share value.
But is it a win-win proposition for current and new policyholders?
To be sure, a corporate structure is the way forward if Income is to grow in Singapore and the region where it will need distribution partners and substantial capital. Even in Singapore, where it is buttressed by a long-standing business and an established brand, it grapples with stiff competition, rising consumer expectations, unrelenting pressure on costs and an increasingly burdensome regulatory backdrop.
Regional ambition
Corporatisation opens up avenues for Income to raise capital from institutions and even potentially from the public through an initial public offer.
Currently Income is governed by the Co-operative Societies Act which limits institutional membership to co-ops and trade unions. Shares are capped at par value of S$10 a share; there is a statutory 10 per cent cap on dividends.
Given rising affluence in the region, a vast protection gap and the opportunities to tap into the need for retirement adequacy, institutions will likely be eager for a foothold in an insurance group which boasts a long track record in managing assets - with a social purpose to boot.
Income has already signalled the seeds of its regional ambition when it began its foray into Malaysia, Indonesia and Vietnam with its insurance-as-a-service model last year. It launched Droplet in these markets, a micro-insurance service that protects commuters against price surges in ride-hailing platforms. But this is icing on the cake in populous markets where insurance penetration is low and affluence is growing.
Even in a mature market like Singapore, there are pockets of opportunity. Insurance penetration here is already high; on average, an individual owns more than 2 policies. But the protection gap remains wide, for one. There is still a dearth of attractive retirement or income-generating de-cumulation products. And there is the higher-margin segment of jumbo policies for the high net worth market.
Market consolidation
But standing out in a crowded market is a challenge, and this is evident in the consolidation that has taken place to date. Insurance upstart Singlife has merged with Aviva. HSBC Holdings has acquired AXA Singapore. These players and Income have a distribution model that embraces the non-tied financial advisory (FA) segment. Income itself has more than 1,000 tied agents or financial consultants, but it also competes for shelf space among licensed FA firms.
Today in the life business, its share of 8 per cent makes it the fifth largest. A decade or two ago, it was firmly in the top 4. In the health business, its share is also substantial with 700,000 IncomeShield policyholders. Even so, profitability is an ongoing challenge as an ageing population and rising healthcare costs will cause claims to escalate.
So far Standard & Poor's has maintained its credit rating for Income at AA-, a rating which Income has held since 2009.
In a report, S&P said: "Following NTUC Income's announcement of its corporatisation plan, we anticipate extraordinary support from the Singapore government to remain forthcoming for the insurer, through its majority owner NTUC Enterprise. Post-corporatisation, we expect NTUC Income to retain its solid competitive position. This is based on its reputable brand within Singapore and a satisfactory capitalisation while managing its growth strategy."
S&P expects the corporatisation exercise to provide Income with greater funding flexibility which will support its growth strategy in the medium term. "On the other hand, the proposed corporatisation would require the company's management to focus on improving capital efficiency, risk-reward optimisation and scale expansion."
Income has said the exercise will not change existing policyholders' policy coverage, benefits and terms. In-force policies, in any case, are already managed with a view to fulfilling contractual terms and promised benefits including guarantees where they exist.
Through the years, Income has stood out in terms of a more generous distribution of surpluses to policyholders, even in years when investment performance has been poor.
Income clients who maintain participating policies have historically enjoyed relatively higher bonus payouts, less-frequent bonus cuts, and a total expense ratio that ranks among the lowest among insurers with par products. Premiums from participating policies are invested collectively and returns to policyholders are "smoothed" over time.
Payouts and premiums
A number of factors support Income's more generous payouts and competitive premiums. These factors include consistently strong returns from the life fund - not an easy feat considering the low interest rate environment and the dearth of long-dated fixed income instruments to match long-tail liabilities. The 10 per cent cap on dividends to co-op members also helps to conserve surpluses. Between 2018 and 2020, the dividend rate has been maintained at a conservative 6 per cent - well below the 10 per cent cap.
Going forward, corporatisation should not dilute Income's capital discipline and commitment to its social mission. Income has pledged S$100 million over 10 years into social and sustainable causes. Capital discipline may well improve as the entry of third-party capital will raise scrutiny over efficiency and shareholder return.
Fresh injection of institutional capital is, however, a double-edged sword. Even as it enables expansion, Income has to strike a balance between profit maximisation and policyholder interests.
Ultimately for an entity with a strong social purpose, corporatisation and the benefits it brings should not be a zero-sum game.






