

OCBC, UOB customers can tap CPF funds to buy T-bills online from Mar 31 and Apr 22 respectively
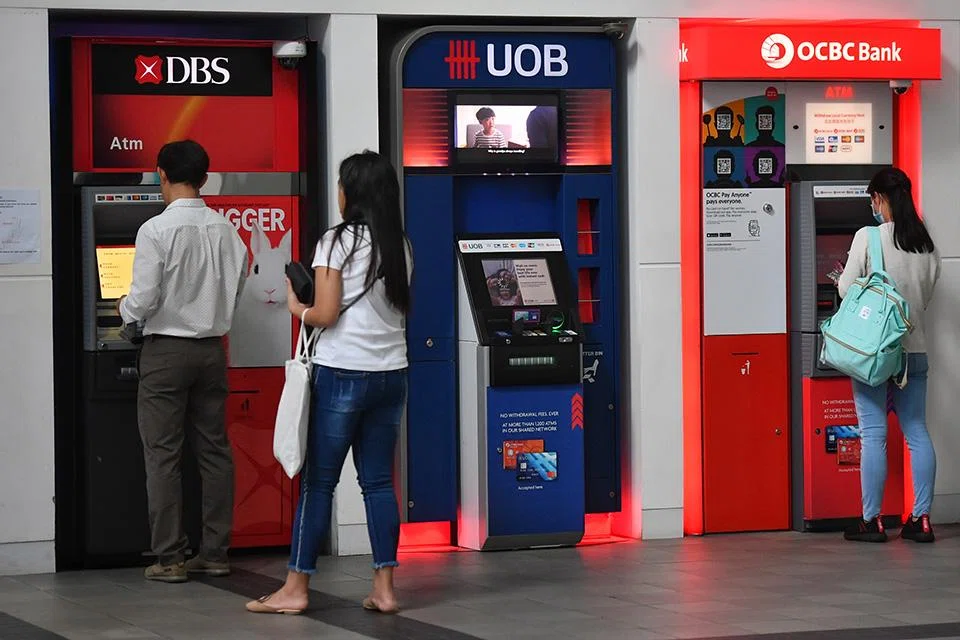
OCBC and UOB ’s Central Provident Fund Investment Account (CPFIA) customers using their ordinary account (OA) savings will soon be able to buy Treasury bills (T-bills) online.
The start date is Mar 31 for OCBC customers and Apr 22 for UOB customers.
The Monetary Authority of Singapore has also said on its website that OCBC’s Internet banking portal will, from Mar 31, start accepting online applications for T-bills purchased using OA as well as Special Account (SA) funds under the CPF Investment Scheme (CPFIS).
This makes it the only CPFIS agent bank so far to offer online applications for T-bill purchases using funds from the OA and SA.
Investors using UOB’s CPFIA services will be able to apply online for T-bill purchases using their OA savings from Apr 22. At the moment, only customers using DBS or POSB as their CPFIS OA agent can apply online using OA savings, saving them a trip to the bank branch. DBS opened its online application avenue for OA through its Internet banking portal in February.
With CPF offering OA and SA interest rates at 2.5 per cent and 4 per cent per annum respectively, some investors have urged the government to raise these rates amid rising inflation. (For comparison, the cut-off yield on the six-month T-bill in the last auction earlier this month was 3.98 per cent.)
The next T-bill up for auction on Mar 16 has opened with an offering of S$4.6 billion and a six-month tenor.
For OCBC CPFIA customers, the first six-month T-bill that they can apply online for is the one opening on Apr 5 for auction on Apr 13, or the one-year T-bill available every quarter, which opens on Apr 13.
UOB CPFIA customers will have to wait for the six-month T-bill with an auction date of Apr 26. They will have to give the one-year T-bill with an auction date of Apr 20 a miss if they want to make only online applications.
Those who buy T-bills – which are risk-free and backed by the Singapore government – with money from their CPF accounts need to complete a self-awareness questionnaire, which has 20 questions to help would-be investors assess their level of basic financial knowledge and whether CPFIS is suitable for them.
Investors should ensure that they would go for T-bills only if the yield is higher than the 2.5 per cent or 4 per cent interest rates for OA and SA savings respectively. This is because the CPF Board does not compute interest for the amount withdrawn during the month; interest is paid on that amount for the month only after a refund is made.
If six-month T-bills are purchased in the first auction of the month, investors have an opportunity cost of seven months of CPF interest. This means they will need a yield of 2.92 per cent for OA funds, and 4.67 per cent for SA funds to break even.
If the bills are purchased at the end of the month, an investor has an opportunity cost of eight months of CPF interest – with the breakeven at 3.33 per cent for using OA funds and 5.33 per cent for SA funds.
This is on top of charges by banks for purchases made using OA savings.
Investors also have to ensure that funds returned to the CPFIA at the bank upon a T-bill’s maturity are transferred back into their CPF accounts promptly, in order to earn the prevailing interest rate.
Apart from using CPF money, Treasury bills can be purchased with cash and Supplementary Retirement Scheme funds.
Attractive yields have lately nudged investors into diverting their funds to T-bills.
There have been withdrawals from current accounts and savings accounts, giving the banks a run for their money.
TRENDING NOW

Why US$100 oil, 5% US yields affect Singdollar, ringgit differently vs other Asean currencies
Singapore fintechs struggle to find finance and tech talent

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing

Why Tan Aik Keong of digital solutions specialist Agmo wants to make himself less indispensable

