

Ping An's OneConnect eyes backstage role in S-E Asian digibank race
Sharanya Pillai
Singapore
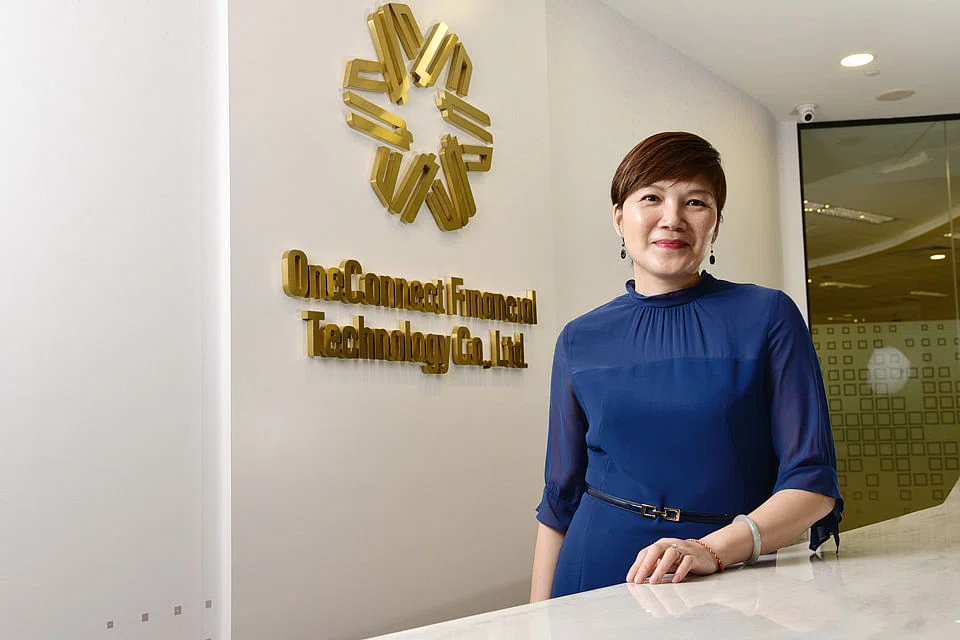
ONECONNECT, the fintech associate of China's Ping An Group, decided not to apply for a digital banking licence in Singapore after exploring the prospects, its chief executive for Asia-Pacific and the United Arab Emirates, Tan Bin Ru, told The Business Times.
The company, which already owns a virtual banking licence in Hong Kong, instead wants to position itself as a digital banking enabler in South-east Asia, providing end-to-end solutions for the upcoming crop of digital banks here.
Ms Tan was addressing market speculation that OneConnect has entered Singapore's digital banking race, after Bloomberg reported in September that the firm was mulling an application. Ping An Group and its other subsidiaries also did not apply for a digital banking licence in Singapore, Ms Tan added.
Rather than competing with the digital bank aspirants here, OneConnect sees more potential in serving them with its "digital bank-in-a-box" suite of solutions, that includes mobile banking, smart lending, supply chain finance and cloud banking tools.
"The digital banking space is a space that we are very interested to play in. It's just that we don't want to play in the form of owning the licence, but (via) our technology stack... We put everything that you need to start a digital bank in a one-stop shop," Ms Tan said, noting that OneConnect has already received interest from some of the licence applicants.
With Malaysia now planning to issue digital banking licences as well, the potential demand for OneConnect's solutions could be even greater in South-east Asia.
"Even if (the countries) don't open up digital banking licences, I think that the incumbent banks will want new solutions," Ms Tan said.
Among its capabilities, OneConnect can help digital banks build a mobile banking "superapp" that integrates services across accounts, as well as provide them e-KYC (know your customer) solutions that incorporate facial and voice recognition.
One of OneConnect's most popular products in South-east Asia is its credit scoring tool for unsecured loans, that taps on alternative data points like social media data. Such tools are especially relevant to digital banks targeting the unbanked segment, Ms Tan added.
OneConnect only entered South-east Asia about a year ago, and has 14 clients across Singapore, Malaysia, the Philippines, Indonesia and Thailand. Many are incumbents, such as Indonesia's Bank Sinarmas and UBX, a subsidiary of the UnionBank of the Philippines.
That base may seem like a drop in the ocean compared to the over 600 banks and 3,000 non-bank financial institutions, including fintechs, that OneConnect supports in China. But, South-east Asia is a fast-growing market for the US-listed firm, according to Ms Tan.
OneConnect currently earns about 7 per cent of revenue from outside of China, she noted, and is looking to raise this to 15 per cent by about 2022. "Our investors definitely see a lot of potential for our solutions to be more international... We get a lot of value out of localising what is the best created out of China."
Ms Tan is also aiming for the South-east Asian segment to break even this year, and for the number of regional customers to triple by 2021.
Over in Hong Kong, OneConnect clinched its virtual banking licence in March last year, one of eight companies to do so. It has not launched its virtual bank there yet, but is expected to do so soon.
When asked why OneConnect is pursuing digital bank ambitions in Hong Kong, Ms Tan highlighted that Ping An Group is more focused on Greater China when it comes to core financial services. "Greater China to us is a region on its own, where we would conduct both our bread-and-butter banking and insurance business, as well as the tech business. But outside of greater China, it's only the tech business, currently," she explained.
Ping An Group is the largest shareholder of OneConnect, with a 36.6 per cent stake.
Other backers include SoftBank's Vision Fund, which invested in OneConnect in 2018, before the company listed on the New York Stock Exchange in December last year.
When asked if OneConnect has any digital banking collaborations with Grab, a fellow Vision Fund portfolio company, Ms Tan replied: "I think that they are also still thinking about their strategy... They also have technology capabilities and may decide to build something on their own."
In any case, OneConnect's decision not to step into the digital bank game in South-east Asia has brought relief to some of its existing customers, she added.
"Customers were very keen to know whether we are going to compete or complement their technology stack. And because a lot of them are using our technology stack, they are actually relatively happy that we have taken the decision not to apply for the licence."
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
If AI has a one-in-five chance of destroying us, what do we do with the remaining four?

