

Rate cuts may put novel fund financing on the radar, but S-E Asia’s lenders need to up their game
Increased complexity in newer types of lending is a hurdle for industry players
FUND finance 2.0 could get a boost from an expected cut in the United States’ federal funds rate next week, but market players also noted that South-east Asia’s lenders are only just getting familiar with the more complex forms of private equity (PE) leverage.
While subscription line financing is common, other forms such as net asset value (NAV) financing are less so. Adoption is growing, but regional lenders could take time to shift from their present conservative positions.
“People here are just starting to become alive to what NAV financing can do,” said Seah Beelee, a partner at law firm Norton Rose Fulbright (Asia) who specialises in fund finance.
His expertise is being sought by banks keen on educating their teams on how NAV and other forms of fund financing work; he has conducted talks for a wide range of bank employees.
Interest is high among banks to venture further into fund finance, Seah said, but risk officers in most banks in the region would not be familiar with this type of product.
The hesitance to wade into what the industry refers to as fund finance 2.0 is partly due to the increased level of complexity.
PE funds typically deliver returns through a combination of improved efficiencies and increased leverage at acquired portfolio companies.
On top of any loans taken by these companies, a fund might take on leverage too. One commonly cited reason is to avoid having to call capital from investors.
Limited partners (LPs) who agree to invest in a PE fund do not send cash to the fund until asked by the investment manager or general partner (GP).
GPs, on their part, may try to space out capital calls for administrative purposes, and will turn to a bank for a subscription finance facility (SFF) to draw on between calls.
Clifford Lee, global head of investment banking at DBS, said SFFs are easier for a bank to get behind. “These are predicated on commitments to a drawdown for funds, and banks can easily extend loans on drawdown obligations,” he said.
NAV financing, on the other hand, is often on a non-recourse basis. If a borrower defaults, the lender will not have recourse to the assets of the portfolio companies – only to the assets of the borrower, which might be a special-purpose vehicle (SPV) without significant assets.
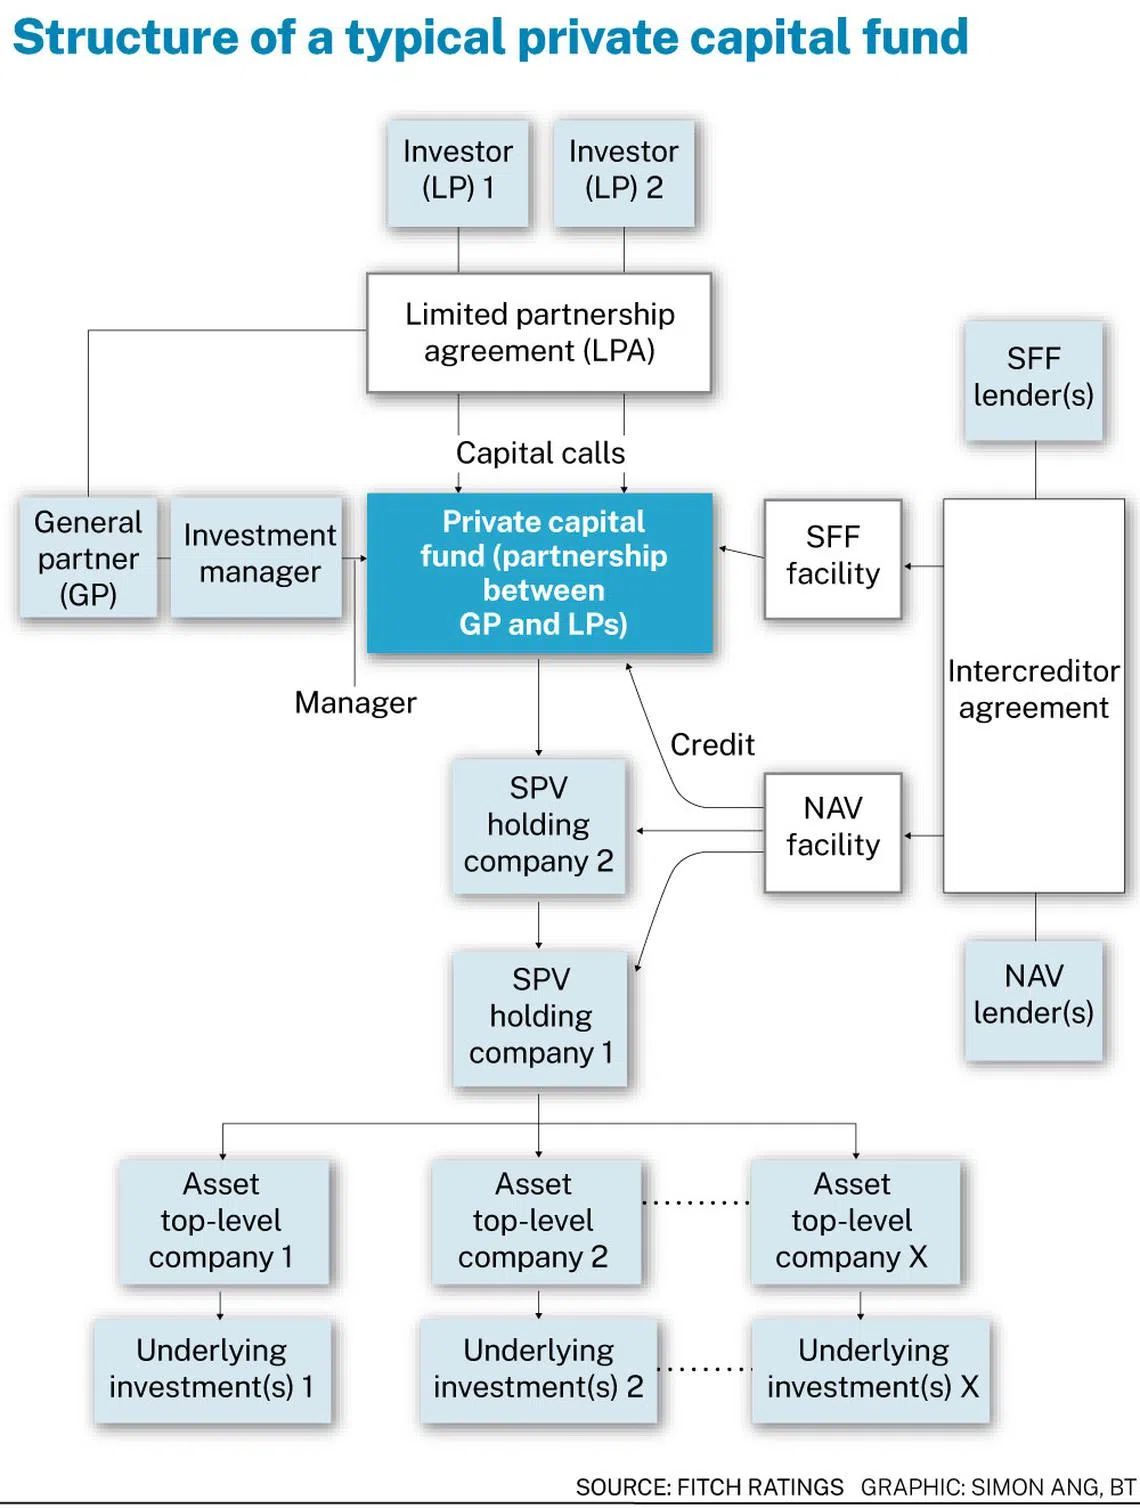
As a private, unlisted and illiquid entity, this SPV would be difficult to value. A lender would grant an NAV credit facility on the strength of cash flow from the portfolio of assets that the fund has invested into, but the structuring of such a facility is not straightforward.
“The traditional way of looking at financing against observable mark-to-market risk doesn’t apply,” Lee added.
NAV financing is prevalent in the US and Europe, where GPs have been accused of using it to goose returns or extend the lives of their funds.
Another form of financing that is popular in the developed market PE space is dividend recapitalisation, which involves taking on debt to pay dividends to investors.
Several regulators have flagged concerns about the levels of leverage within the PE industry. The European Central Bank, for one, said in its Financial Stability Review in May that “financial innovation and opaqueness in private markets could contribute to financial stability risks”.
It specifically called out “multiple layers of leverage at company, fund and investor level”, and the risks for banks “from lending exposures to these markets”.
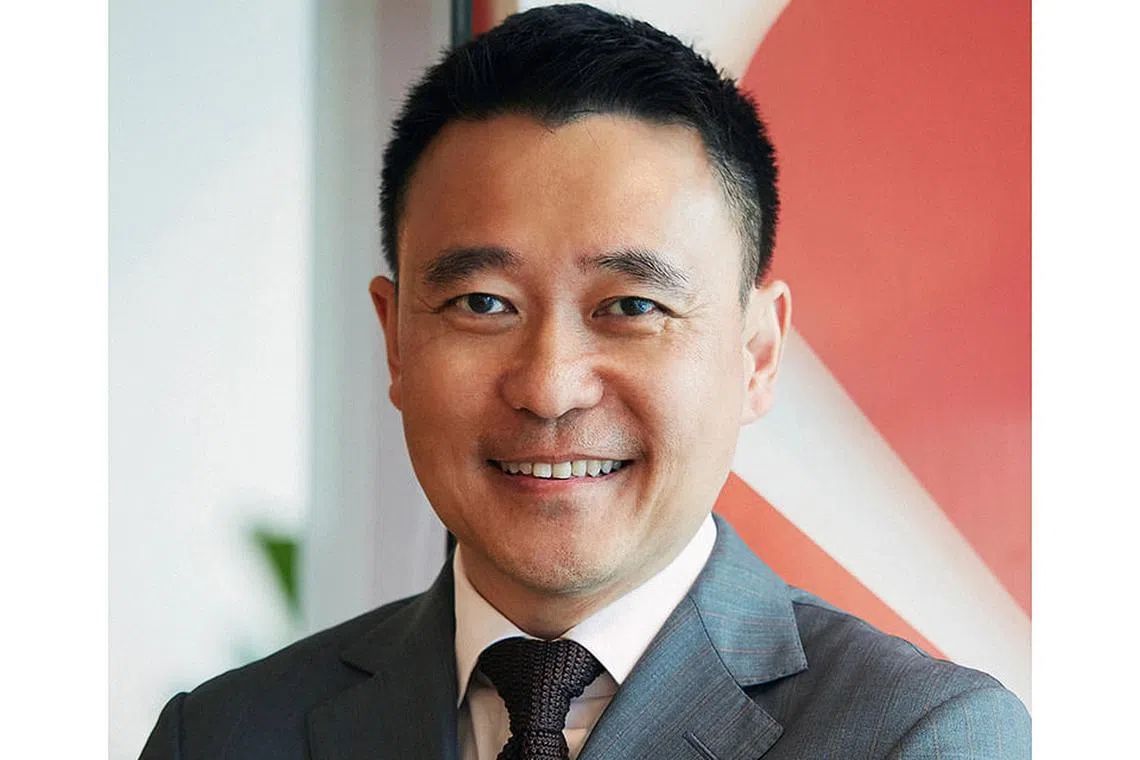
DBS’ Lee said Asia’s financing markets have traditionally taken more time to develop. This was one reason Asia was relatively shielded from the negative effects of the US subprime lending crisis in 2008 – with the 1998 Asian financial crisis still fresh on many minds, Asian bankers were more conservative in their adoption of securitisation.
They have been relatively more conservative in fund finance, too.
NAV financing is “several steps more… in terms of sophistication and risk”, Lee said, adding that banks in this region are able to tolerate lower yields and “would rather charge you less for lower risk than charge you more for higher risk”.
There is, nevertheless, strong interest among banks to offer loans to the PE industry.
Antonio Puno, head of South-east Asia investment banking at Bank of America, said the PE players that the bank works with on deals have been “taking advantage of aggressive local bank financing, both senior and mezzanine, to fund their business in South-east Asia”.
“South-east Asian local banks in markets such as Malaysia, the Philippines and Thailand have been quite aggressive when funding the right names in the right sectors, which provides firepower to sponsors,” he said.
Jean Woo, office managing partner at law firm Ashurst Singapore, said that although the Asia-Pacific’s fund finance market is still small – roughly 10 per cent of the total market size – it is likely to “grow strongly towards the end of 2024”.
“There is an expectation that the slow-down in fundraising activity will bottom out then,” she said. “The market is expecting activity in the last quarter of 2024 to be double that of the first quarter of 2024, as that is when interest rates are expected to be lower and there are more successful exits for investments.”
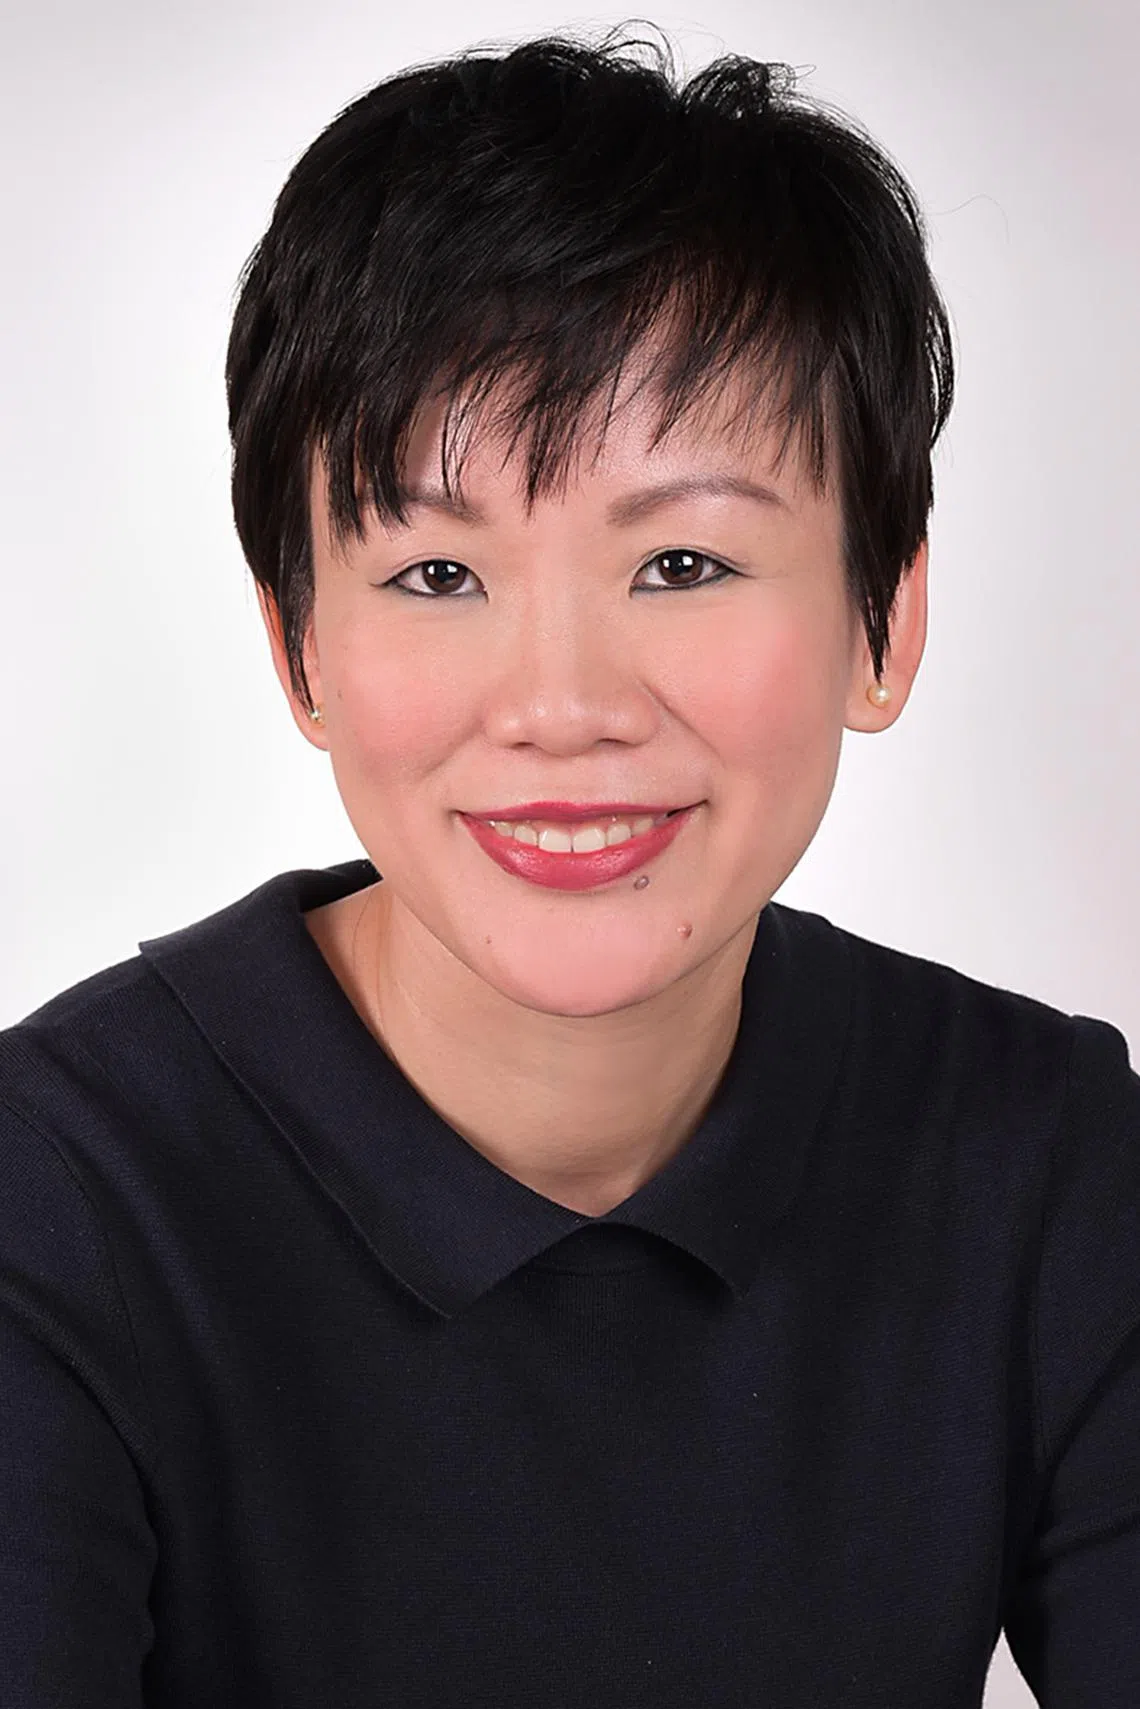
Will the NAV financing trend skip Asia, given the negative press? Not necessarily, said Lee of DBS.
“NAV financing can also be met by private credit funds or hedge funds,” he said, and banks could develop an appetite for it over time – perhaps with some alterations.
Lee said it is common for financing trends to come and go, depending on sentiment and macroeconomic conditions, and noted that securitisation is already back in vogue in the US and Europe.
“In developed markets, you have quicker adoption and quicker correction,” he said. “Asian markets pick and choose, learning from developed markets. In Asia, we have been quick followers.”
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Singapore-based Ryde accused of pump-and-dump fraud in class action lawsuit
Malaysia’s F1 return: A low-cost second chance, possible Singapore boost
Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet

