

Sticking with winners came up tops for 2017
Long momentum returned 38 per cent in the year, the strongest advance since 1999
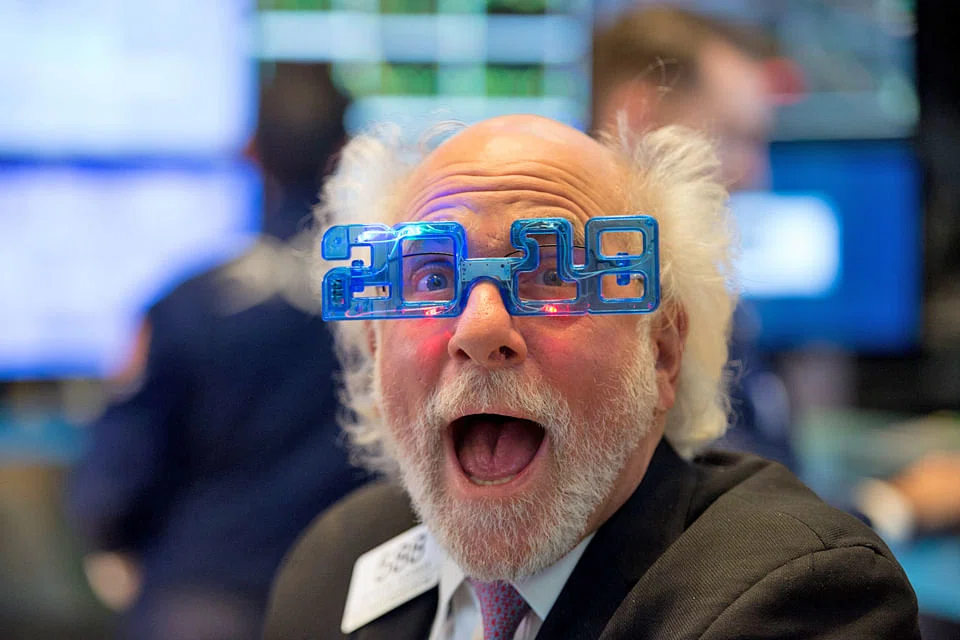
New York
SLICE the rally however you want: chips, Nasdaq, retailers, banks. But 2017 will go down as the year an investment strategy based on nothing more than sticking with winners shone brightest.
Long momentum, when traders simply buy shares that are rising the fastest, returned 38 per cent in 2017, the strongest advance since 1999. Paced by firms like Square Inc and Align Technology Inc, the strategy came within an inch of surpassing its advance the year before the dot-com crash.
More than a quantitative quirk, the overwhelming success in momentum investing was one of the things that made 2017 a turning point in equities for many observers. Less hated, less distrusted, the bull market born at the bottom of the financial crisis took on more of a speculative mien, with gains massing in fewer shares and valuations pushing ever higher.
"I can give you a million things on why this year was abnormal," said Donald Selkin, New York-based chief market strategist at Newbridge Securities Corp. The firm oversees US$2 billion. "Look at the levels of volatility, look at the FANGs, look at the S&P's rally. The market has rallied tremendously, but it's hard to imagine the party will last."
Much that went on in the market was healthy. Gains in the S&P 500 matched the annualised advance since the bull market began. While price-earnings ratios widened, it happened as earnings themselves were rising at an 11 per cent clip.
Away from technology, gains were evenly divided, with returns in five different industries clustered close to 20 per cent.
A simple concept, momentum investing is a tool of sophisticated traders, an equity "risk factor" that is the subject of copious academic research. Heavy lifting in the trade was handled by a familiar set of technology megacaps - Apple Inc, Facebook Inc, Amazon.com Inc, Microsoft Corp and Alphabet Inc - which were responsible for about a fourth of the S&P 500's gain.
Given its role in passive strategies and the amount of money tied in through exchange-traded funds, momentum's success, particularly in a year of scant volatility, was sure to strike some as having come too easily - a mindless harvesting of returns that rings alarm bells among the prudent. This year's monotonous climb has left the S&P 500 with a positive total return in 14 straight months, a record.
"Investors are falling in love with the entire market," Aaron Brask, former head of equity derivatives research at Barclays Capital, wrote in a research note on Alpha Architect website in late September. "I believe some of the most popular strategies are creating self-perpetuating flows of capital and significant risk."
For bulls, it's been a risk worth taking. The S&P 500 rose 19 per cent this year; the Dow Jones Industrial Average 25 per cent; and the Nasdaq Composite 28 per cent. Semiconductor shares within the S&P 500 surged 36 per cent; retailers rose 29 per cent; and a group of diversified banks and brokerage jumped 23 per cent.
Wall Street forecasters see little let-up in 2018. Four strategists tracked by Bloomberg project that the S&P 500 will finish 2018 at 3,000. Canaccord's Tony Dwyer sees the gauge at 3,100, a 16 per cent gain from Friday's close.
Investors have put US$2.6 billion into the iShares Edge MSCI USA Momentum Factor ETF this year, an almost fourfold advance from the ETF's inflow in 2016, data compiled by Bloomberg show.
Some stocks have been riding the momentum wave longer than others: Align Technology Inc and Nvidia Corp, two of the top gainers in the S&P 500 this year, are among the 10 best performers in the index over the past six years.
Not that the road has been totally smooth. Tech is the biggest contributor to momentum, and a few rocky days in June, when the Nasdaq 100 Index gave up US$400 billion, sent volatility in computer firms to a 2008 high versus the rest of the market.
On several occasions in 2017, stocks with the highest price momentum bore the brunt of downdrafts, a sign of unwinding among quantitative funds. Then they recovered.
Dennis DeBusschere, head of portfolio strategy at Evercore ISI, says headwinds to the momentum trade that started to emerge in the fourth quarter should continue into 2018, particularly if the improvement in actual and projected economic growth continues.
Add this to concern about thinning market breadth - 2017 was the first up year of the bull market when the cap-weighted S&P 500 beat the equal-weighted version - and worries about skyrocketing valuations, with the S&P 500 teetering at a price-to- sales level unseen since the dot-com bubble.
Still, the momentum mentality has rewarded investors in 2017, turning market bears that once roared at any sign of trouble into reluctant bulls. A Goldman index tracking the most-shorted shares has climbed 19 per cent since January, biting anyone on the wrong side.
For John Stoltzfus, chief investment strategist at Oppenheimer & Co, who has one of Wall Street's most bullish forecasts for the S&P 500 next year, that capitulation along with improving economic fundamentals is what drove momentum in 2017.
"This is the recognition that this appears to be a point where the economy is growing at a pace that can support the stocks rally." BLOOMBERG
TRENDING NOW

What shattered Crystal Jade? How the culinary empire shrank from 120 to just 9 outlets
‘We’ll wait and see’: Investors wary after STI sinks below 5,000 amid global AI selldown
‘The next 40 years’: SingLand CEO Jonathan Eu on remaking Marina Square
Singaporean extradited to face US charges over global insider trading scheme

