

Brokers' take
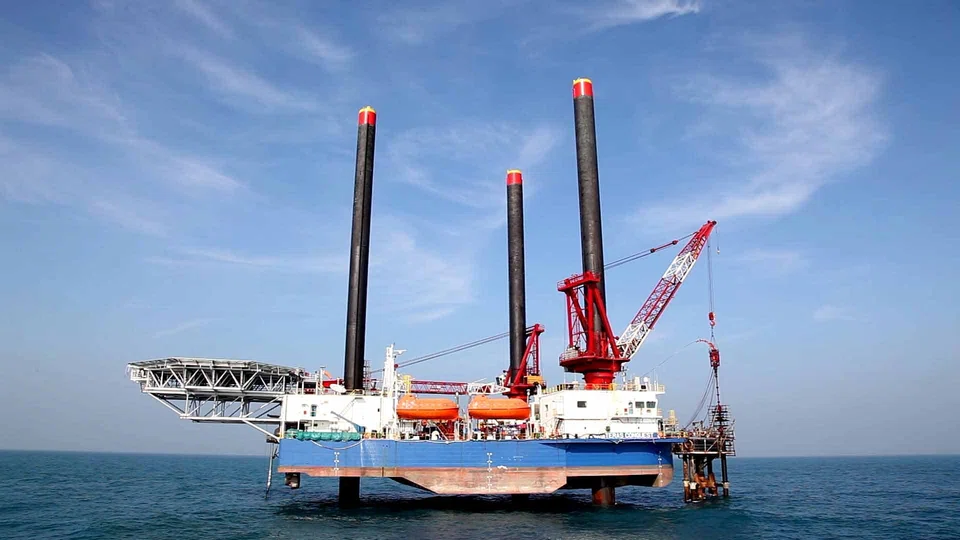
Ezion Holdings | Sell
May 18 close: S$1.13
Target price: S$0.88
KGI Fraser Research, May 18
The deteriorating rig market from the oversupply has caused us to be more bearish on the offshore rig sector, especially owners of old assets. We see Ezion's drilling rigs as highly vulnerable to cancellations. Thus, we downgrade Ezion to sell with a target price of S$0.88 based on 0.8 times price-to-book (P/B) (higher range of international peers to account for its liftboat business). The uncertainty in dayrates, utilisation rates and risks of cancellations makes earnings based valuations irrelevant in the current market, and thus we change to P/B multiples to give less volatility with valuations.
StarHub | Buy
May 18 close: S$4.26
Target price: S$5.00
Maybank Kim Eng Research, May 18
Q1 2015 made up 19 per cent of our FY15F as StarHub decided to lead the sector in capturing unusually-strong iPhone 6 demand. Normally, iPhone demand tapers off in Q1 after Q4's peak. This was not the case this year, likely because iPhone 6 was a major form factor change.
We view StarHub's decision positively despite the earnings miss. Its higher subsidy costs now should translate into better quality earnings in the future. Specifically, we see two benefits. StarHub now has 24,000 more postpaid subscribers that it can upsell more services to. Secondly, it has locked them into two-year contracts, fortifying its subscriber base before the new entrant breaks in. Pay TV was stable. Singtel has become a more rational player and we expect it to remain so this year, critically because BPL is up for renewal again.
Thai Beverage | Add
May 18 close: S$0.76
Target price: S$0.87
CIMB Research, May 15
Our raised estimates are mostly from beer. Management guidance suggest that the effects of weak sales, post-sports tax, should not be long-lasting. Clearly, beer profitability has swung around, on operating leverage and the tailwinds of raised prices last year; we expect the positive signs to sustain.
We see the evolution of an alcohol company into a beverage company. In the old days, the company parlayed its spirits distribution strength to grow a beer business. Now, it is on the threshold of using the free cash flow from its spirits and beer businesses, to fund a fight in the non-alcoholic segment. Volume is key here.
Compiled by Jamie Lee
Disclaimer: All analyses, recommendations and other information herein are published for general information. Readers should not rely solely on the information published and should seek independent financial advice prior to making any investment decision. The publisher accepts no liability for any loss whatsoever arising from any use of the information published herein.
Brokers who wish to send in their reports can email us at btnews@sph.com.sg
TRENDING NOW

World’s largest offshore wind platform by Seatrium consortium on track to be completed by 2028

Is stamp collecting enjoying an analogue revival or are its best days over?

GovTech retrenches another 38 staff in second round of layoffs

MBS adjusted property Ebitda falls 20.6% in Q3 with fewer high-roller visits, weaker hold

