Brokers' take
Genting Singapore>Outperform
Credit Suisse, Oct 7
Target price: S$1.00
Oct 7 close: S$0.765
FROM our recent marketing trips to Singapore and Hong Kong, we conclude that investors remain concerned about two things: VIP gross gaming revenue (GGR) might not have bottomed; and the Zika outbreak could negatively impact Genting Singapore's (GENS) mass business. We believe that investors are generally adopting a "wait and see" approach and will be watching H2 2016's results very closely for signs of improvement. That said, most investors agree that valuations are cheap relative to the Macau Gaming Sector. We retain our "outperform" rating given that the upside risk (31 per cent upside) outweighs the downside risk (9 per cent downside), in our view. Our target price excludes the Jeju project.
Singapore offshore & marine sector>Underweight
UOB Kay Hian Research, Oct 7
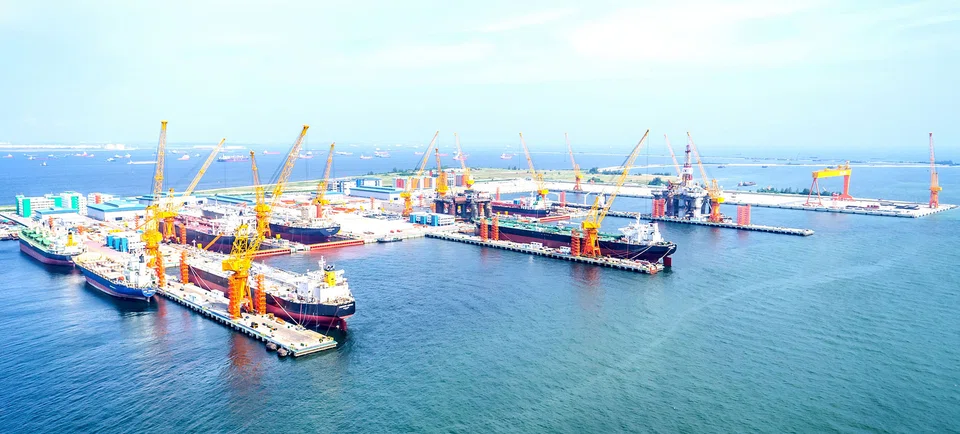
IMPROVED sentiment in oil prices has seen a lift in offshore support vessel stock prices despite minimal change in fundamentals. Oil majors are likely to keep 2017 capex flat, leading to no earnings improvement until 2018. However, we recognise there are trading opportunities and see a possible rebound to the -1 standard deviation level. We expect an increase in oil majors' capex in 2018 assuming oil prices stabilise at US$50-60/barrel for most of 2017. An uptick in earnings is expected after H1 2017. Between now to then, several quarters of poor earnings still lie ahead for offshore marine players, on top of further debt/bond repayment issues.
Innovalues > Buy
Maybank Kim Eng Research, Oct 6
Target price: S$1.15
Oct 7 close: S$0.875
THE stock has retreated since it hit a high of S$1.11 in July, but we remain positive. Improving revenue growth and margin expansion on current valuations still support our positive view. The merger and acquisition process has been ongoing since April and we believe impatient investors who bought the stock hoping for a quick conclusion may finally be throwing in the towel. This opens up room for longer-term holders to get in. We maintain "buy" with a Street-high target price of S$1.15 (13.5 times FY17 price-earnings ratio, 10 per cent below peers).
Compiled by Kenneth Lim
Disclaimer: All analyses, recommendations and other information herein are published for general information. Readers should not rely solely on the information published and should seek independent financial advice prior to making any investment decision. The publisher accepts no liability for any loss whatsoever arising from any use of the information published herein.