

Brokers’ take: Analysts see resurgent fountain of wealth in Suntec Reit
Sharanya Pillai
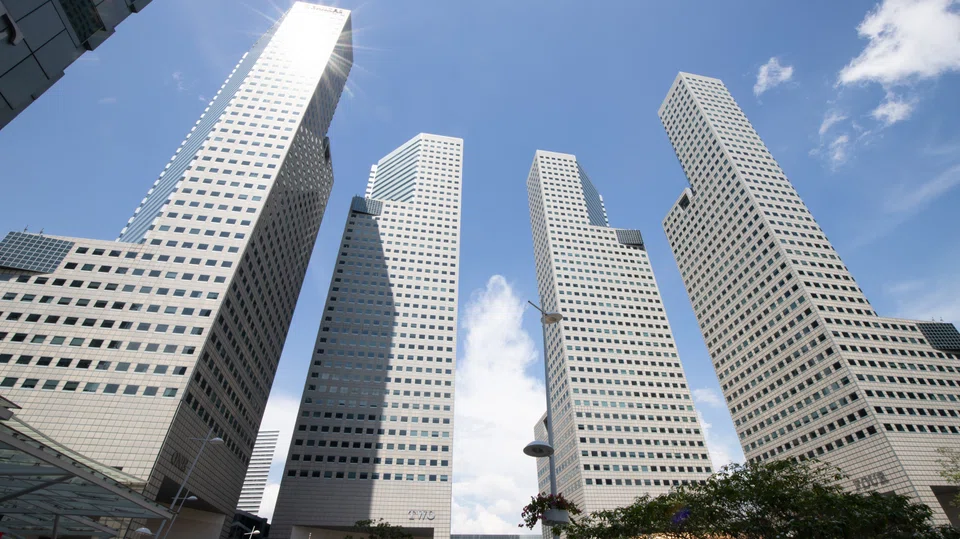
OPTIMISM about Suntec Reit ’s office portfolio, as well as recovery in the retail and convention segments, has prompted at least 1 broker to upgrade its call on the counter. Most of the other analysts who cover the stock also see better prospects for the sectors in which Suntec Reit operates, although several have flagged its high leverage.
CGS-CIMB on Wednesday (Jul 27) elevated its call on Suntec Reit from “hold” to “add”, while maintaining its target price at S$1.79.
The research house had in fact lowered its distribution per unit (DPU) estimates for FY2022 to FY2024, to factor in slightly higher interest costs and Suntec Reit’s guidance for higher utilities costs in FY2023.
“However, we believe Suntec Reit’s 13 per cent decline in share price over the past 3 months would likely have priced in these challenges,” analyst Lock Mun Yee said in her note.
At the same time, Lock sees recovery ahead for many of the Reit's properties.
Suntec Reit posted a 15.8 per cent increase in DPU to S$0.0481 for H1 FY2022. Amidst recovery in office occupancy, it enjoyed positive rental reversions of 5.5 per cent for its office portfolio.
Suntec Reit’s H1 retail net property income, meanwhile, rose 40 per cent to S$45.4 million, on the back of higher occupancy and rents at Suntec Mall. And its convention centre turned in a S$2.9 million profit.
Suntec Reit is also embarking on enhancement works at the second level of Suntec Mall’s east wing. Slated to be completed by Q4, this exercise will increase leasable space by 13 per cent and generate a projected 15 per cent return on investment, Lock noted.
In the United Kingdom, Suntec Reit benefited from income from the Minster Building and lower retail rent rebates. Lock noted that the Reit has “minimal” expiries in Singapore, the UK and Australia for the second half of this year.
RHB analyst Vijay Natarajan also sees momentum in Suntec Reit’s office portfolio, with its H1 DPU coming in “slightly ahead of our expectations”. He maintained his "buy" call on the Reit in a Thursday research note, with an unchanged S$1.95 target price.
“Concerns over the impact of financing cost from rising interest rates are slightly overblown in our view, and we expect organic growth to outpace inflation,” Natarajan said, adding that the Reit trades at an “undemanding” 0.7 time book value.
Morningstar equity analyst Xavier Lee called Suntec Reit’s 6 per cent forward yield “attractive”, while also echoing confidence about office demand in his Wednesday note.
“Despite facing competition from the upcoming Guoco Midtown, demand for the trust’s Suntec City office remains strong, underpinned by new tenants from the financial services, technology, media and telecommunications sectors,” said Lee.
There are, however, some concerns about Suntec Reit’s leverage. OCBC Investment Research flagged the Reit’s balance sheet as the “weak link”. Aggregate leverage remains high at 43.1 per cent, despite inching down slightly from the previous quarter.
“Its hedge ratio for its borrowings remains relatively low at 56 per cent. According to Suntec Reit, every 50 basis points increase in interest rates would negatively impact its distributable income by 4.7 per cent,” the research team said in a Thursday report.
OCBC has a “hold” call on the stock and cut its FY2023 DPU projection by 3.5 per cent, due to higher interest cost estimates.
Maybank, which has a “buy” recommendation, and a target price of S$1.85, also acknowledged that Suntec Reit’s gearing remains high, but reckons that this could prompt capital recycling.
The Reit was trading at S$1.61 as of 3.41 pm on Thursday, up 1.3 per cent.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Hwa Seng Builder, two China companies win S$1.2 billion Tuas Road Viaduct phase two contracts

Deal between tycoon friends sparks scrutiny of Philippine power sector

Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet

