

Brokers’ take: UOBKH upgrades GoTo to ‘hold’ on reasonable valuations
Russell Marino Soh
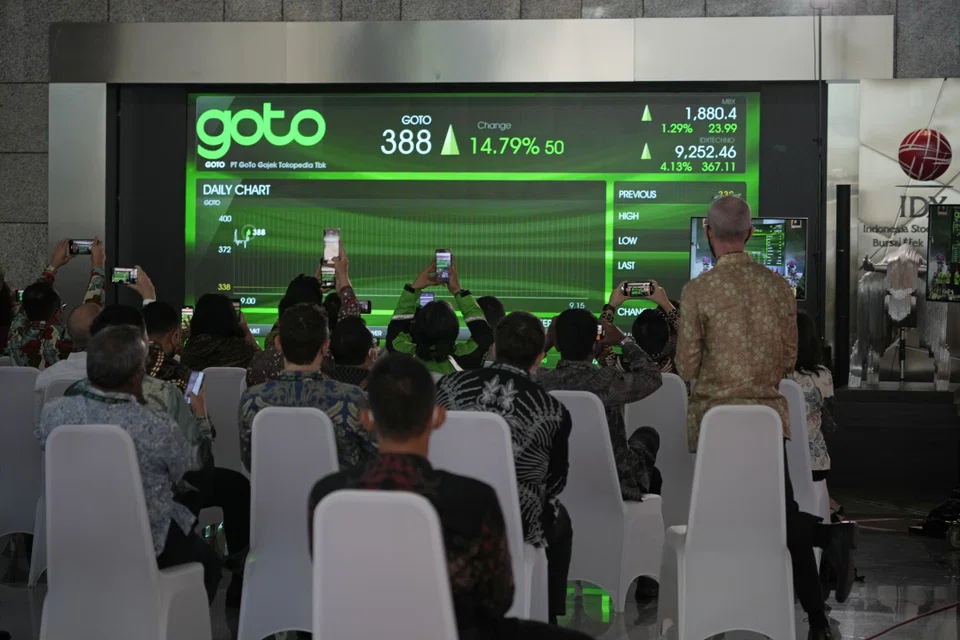
UOB Kay Hian (UOBKH) has upgraded its call on GoTo Group to “hold” from “sell”, citing its “reasonable” current valuation, market leadership and improving outlook.
UOBKH analyst Stevanus Juanda noted that the Indonesian tech giant is showing a “positive trend towards profitability”, with a 216.6 per cent year-on-year increase in revenue for its third quarter ended Sep 30.
“(GoTo) can start delivering better results at the bottom line, and not just at the top line,” Juanda added, pointing to the group’s lowered promotion costs and other cost-cutting initiatives.
Shares of GoTo fell after the group on Monday (Nov 21) posted a net loss of 20.32 trillion rupiah (S$1.8 billion) for the first nine months of 2022. By Wednesday’s open, shares of GoTo were trading at 192 rupiah, down from 216 rupiah on Monday morning.
Juanda said that the current valuation of GoTo is “more reasonable” than before. The brokerage dropped its target price to 190 rupiah from 240 rupiah, after applying a 25 per cent premium to account for its market leadership over competitor Bukalapak.
UOBKH lowered its estimated net loss to 27.6 billion rupiah in 2022, and 24.66 billion rupiah in 2023.

Summarising his outlook for the group, Juanda believed it would benefit from “high revenue growth, an increase in take rate, as well as operation expenditure management”.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW
Analysts cut DBS target price on lower 2027 earnings, but see buying opportunity after share price slide
China Investment Corp, PGIM’s 50% stake in Nex mall up for sale; asking about S$1.2 billion
Nvidia CEO Jensen Huang drops from world’s top 10 richest after chips sell-off
OCBC wealth clients turn defensive amid market volatility as Q3 profit rises 3%

