

Building ESG metrics into executive remuneration
A new report delves into issues such as the subjectivity of ESG metrics, their possible abuse, and where Asean stands on such practices
THE rapidly burgeoning level of interest in environmental, social and governance (ESG) matters among companies, investors and regulators has led to increasing calls for ESG metrics to be incorporated into executive remuneration. But scepticism remains about how this should be done, even among investors who rate ESG issues highly.
Among the concerns are the subjectivity of ESG metrics and their possible abuse. Using quantifiable ESG metrics may reduce the possibility of abuse, but may not necessarily capture the most critical ESG factors for a company.
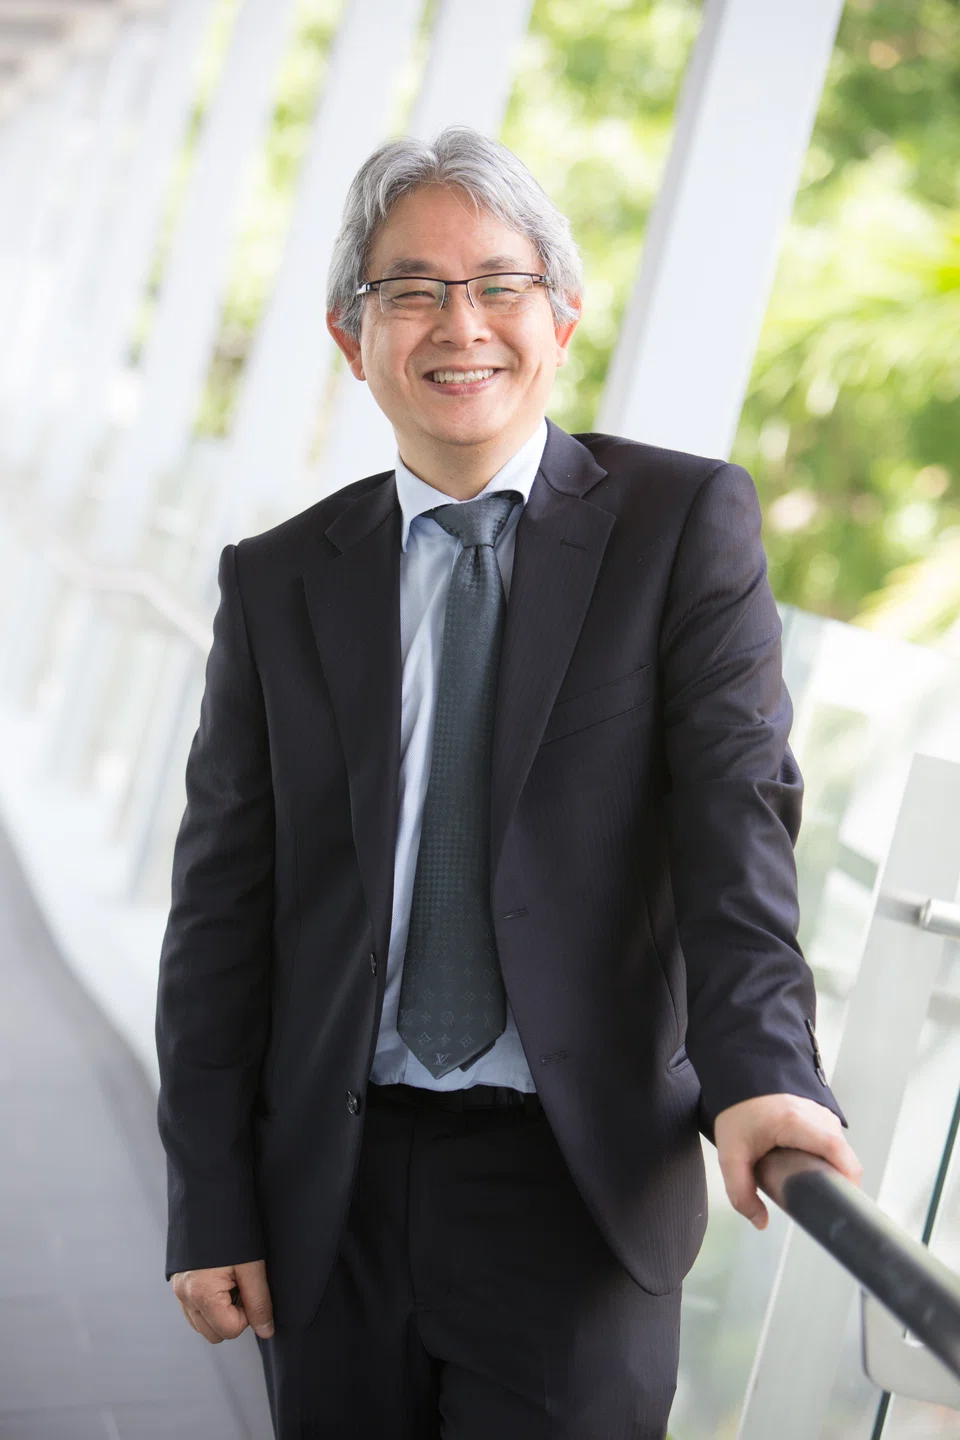
A report launched on Monday (May 23) — Integrating ESG Factors Into Executive Remuneration, led by corporate governance advocate Mak Yuen Teen — attempts a deep-dive into the issue and some of its concerns.
“What this report seeks to do is to identify the key questions that remuneration committees and boards need to think about when considering whether and how to incorporate ESG factors into executive remuneration,” said Mak, a professor of accounting at NUS Business School.
His report lists 10 key questions that boards of directors and remuneration committees should consider when determining if and how they should incorporate ESG factors into executive remuneration. For each question, the report looks at existing research that might help boards and remuneration committees address the question.
For example, the first question is whether companies should link ESG issues to executive remuneration. The report cites research on the number of companies around the world that link ESG factors to executive remuneration, along with academic studies that show the efficacy of linking them, and the benefits and issues with different approaches.
“It summarises what academic and practice research tells us about these issues,” says Mak, who authored the report with the backing of Sustainable Finance Institute Asia (SFIA), an independent institute focused on catalysing ideas on sustainable finance at the policy level, and professional accounting body CPA Australia.
“I felt it would be useful to consolidate the increasing amount of academic and practice research that is being published on different aspects of ESG, and explain the implications of this research in a way that is understandable and useful to companies, investors, regulators and other stakeholders.”
Each question is also accompanied by “In a Nutshell” summaries at the start, to help businesses focus on the pertinent areas, and can be summarised as follows:
- Linking ESG factors to executive remuneration: are there specific material ESG risks for the company, whether meaningful metrics can be used to capture these risks, and if measurable targets can be set for these metrics;
- Choice of ESG factors and metrics: different aspects of ESG are important to different sectors and companies; key considerations include the process of selecting appropriate ESG factors, and having metrics start from a robust materiality assessment of the factors most important to the company and industry;
- Quantitative vs qualitative metrics: quantitative metrics are often preferred by investors, but they may be too narrow or not adequately capture the material ESG issues important to the company; where quantitative metrics are used, companies should consider disclosing specific targets at least after the end of the performance period and explain how they are set; for qualitative metrics, companies need to explain how performance against them is assessed;
- Methods of incorporating ESG factors into incentive plans: while stand-alone ESG metrics are the most objective and have the clearest link to remuneration, they are likely to be most suitable for companies with few material ESG factors; for other companies, a separate ESG scorecard with an overall weighting and specific ESG metrics can be considered;
- Weighting of ESG metrics: surveys show that most companies that link ESG factors to remuneration have a weighting of between 5 per cent and 25 per cent; if ESG is important enough for a company to incorporate into remuneration, then the weighting should be sufficiently meaningful to influence behaviour;
- Incorporating ESG metrics into short-term (STIs) or long-term incentives (LTIs), or both: in general, companies should have both STIs and LTIs in place; LTIs are necessary to motivate executives to take a long-term view, while STIs are necessary to recognise executives for progress in meeting annual goals that are aligned to long-term value creation and success; the balance between them depends on factors such as the business and the ownership of the company;
- Measuring ESG performance against pre-set internal targets vs external benchmarks: most international companies relatively advanced in their journey of incorporating ESG factors into executive remuneration appear to use mostly internal targets; realistic internal targets, set through a robust goal-setting process, can better reflect the company’s context; external comparisons against peers and ESG ratings can increase objectivity and provide a more comprehensive basis for assessing performance, but there may be challenges in choosing appropriate peers and obtaining comparable information, and the lack of consistency among external ESG ratings limits their usefulness;
- Balancing objectivity and discretion: investors increasingly want to see a link between ESG factors and executive remuneration, but prefer metrics that are specific and measurable; even in cases where highly formulaic approaches are used, the remuneration committee/board should have the discretion to adjust the actual payout, and companies should be transparent.
The depth and breadth of the research cited for each question is extensive because, Mak explains, incorporating ESG metrics into executive remuneration is not a simple matter of merely selecting some measures and linking them to executive remuneration.
“ESG must be integrated into strategies, policies and practices of a company, and remuneration policy is part of that integration,” he said. “And it must be thoughtfully implemented, in a transparent manner, and overseen by a competent and independent remuneration committee.”
The report also provides the first-ever assessment of the extent to which major listed companies in Asean are incorporating ESG factors into executive remuneration.
The companies selected were the 135 named as Asean Asset Class companies in the 2019 Asean Corporate Governance Scorecard Awards. They come from six markets: Indonesia, Malaysia, the Philippines, Singapore, Thailand and Vietnam.
The report said it found, among other things, that only 21 companies — or 16 per cent — from Malaysia, the Philippines, Singapore and Thailand, explicitly disclosed that they incorporated ESG factors into executive remuneration; the highest percentage of companies that did so came from Singapore.
Mak observed that companies in this region still have a way to go before catching up with international ones, when it comes to integrating ESG factors into executive remuneration, especially in terms of transparency.
“Asean companies are just beginning the journey,” he said. “While a larger percentage of large Singapore companies say they have incorporated ESG metrics into their executive remuneration, like other Asean companies, there is not much transparency in terms of specific metrics, targets, weightings, etc.
“Hopefully, over time, we will see better disclosures from companies in this region in this regard.”
A particular challenge in this region, he pointed out, is the abundance of founder- and family-controlled companies. “Often, short-term incentives in such companies are based on profit-sharing and there is little or no long-term incentive. The alignment of long-term interest is through their share ownership, but they may not be thinking about ESG issues. Reducing climate risk or treating migrant workers well may be far from their minds.”
Figuring out how to get these companies to embrace ESG, including in their remuneration policies, will be a challenge: “It may not be public shareholders or regulators that can move the needle for such companies, but their customers and lenders.”
The full report is available at Mak’s website: https://governanceforstakeholders.com/.
TRENDING NOW

Malaysian king buys stake in Singapore-listed mining firm expanding into rare earths

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
Longer wait times expected as S’pore healthcare institutions report system disruptions

