

Cache Logistics Trust produces steady set of results for Q3
Singapore
MAINBOARD-LISTED Cache Logistics Trust posted a distribution per unit (DPU) of 2.140 Singapore cents for the third-quarter of 2014, up 0.7 per cent from a year ago.
The distribution will be paid by Nov 26.
Gross revenue rose slightly by 0.4 per cent in the third-quarter to S$20.87 million, compared with the same period last year.
But net property income (NPI) dipped 0.5 per cent to S$19.48 million from S$19.59 million in the corresponding quarter last year, due to an increase in property expenses.
The Reit, which owns 13 warehouses in Singapore and China, said income available for distribution went up by 1.2 per cent on a year-on-year basis to S$16.71 million in the third-quarter this year.
For the first nine months of the year, the trust's NPI went up by 2.4 per cent to S$58.62 million, compared with the same period in 2013.
Income available for distribution also climbed by 2.3 per cent for the first nine months of 2014, to S$50.1 million, from S$48.95 million.
Based on an annualised DPU of 8.490 Singapore cents and a closing price of S$1.165 per unit as at end-September 2014, Cache Logistics maintained a distribution yield of 7.2 per cent.
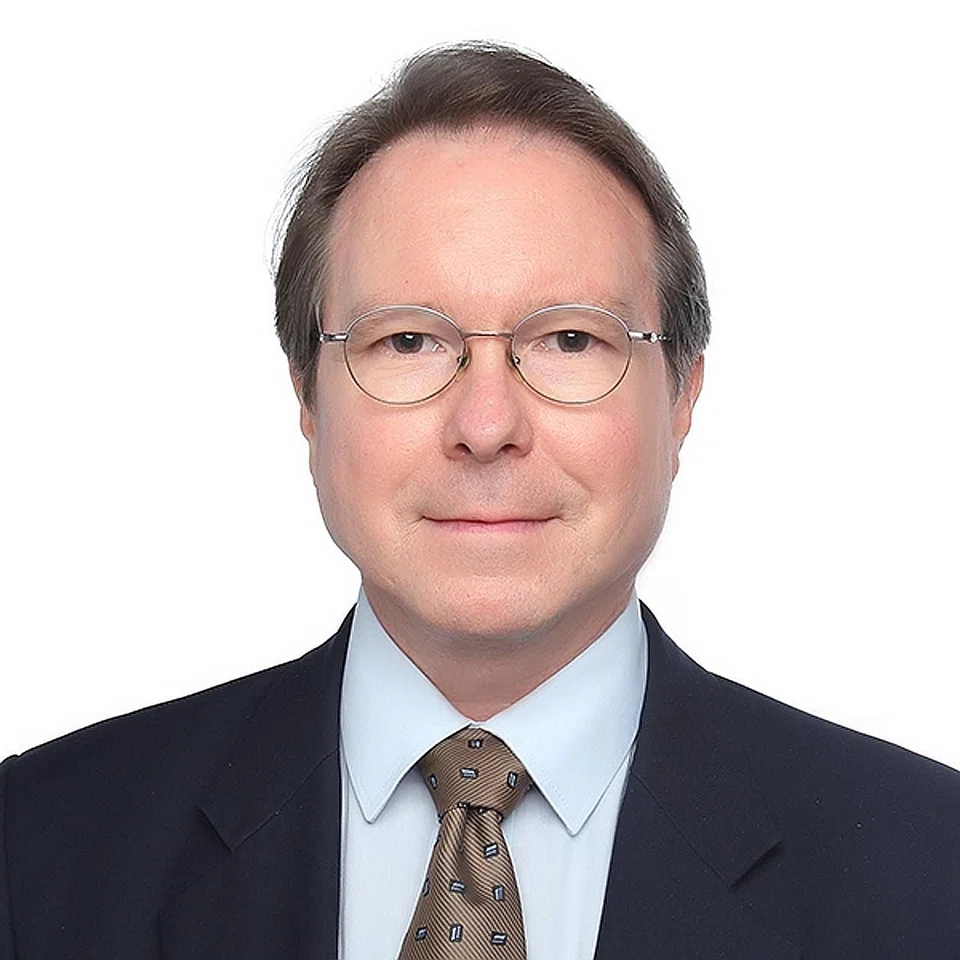
Daniel Cerf, chief executive officer of ARA-CWT Trust Management (Cache) Ltd, which is the manager of Cache Logistics, described the results as "steady".
He said the trust has addressed its financing needs and increased its financial flexibility.
ARA-CWT Trust Management on Thursday completed the refinancing of its existing S$375 million loan facilities.
It entered into a S$400 million club loan facility agreement that provides a four-year term loan facility of S$185 million, a five-year term loan facility of S$150 million and a four-year revolving credit facility of S$65 million.
As at end-September this year, the aggregate leverage ratio was 28.8 per cent, with 70 per cent of total borrowings fixed by way of interest rate swaps.
Cache Logistics' portfolio of warehouse properties is near full occupancy at 99.5 per cent, with a weighted average lease to expiry of 3.6 years, including the initial 10-year lease with DHL Supply Chain Singapore Pte Ltd for the latter's advanced regional centre.
And while there has been a significant increase in the supply of industrial space here, Mr Cerf said the company "feels quite comfortable" in attracting large third-party logistics operators, especially those with ramp-up features and optimal floor plates.
Still, he said the trust will be moving forward quite cautiously and the focus will be on addressing lease expiries in 2015 and 2016.
The Reit is also looking at converting its single-tenancy industrial space into multi-tenancy ones.
Units of the trust ended one cent higher at S$1.185 on Thursday.






