

Hot stock: Yangzijiang sees heavy trading following foray into large LNG vessels via GTT agreement
Yong Hui Ting
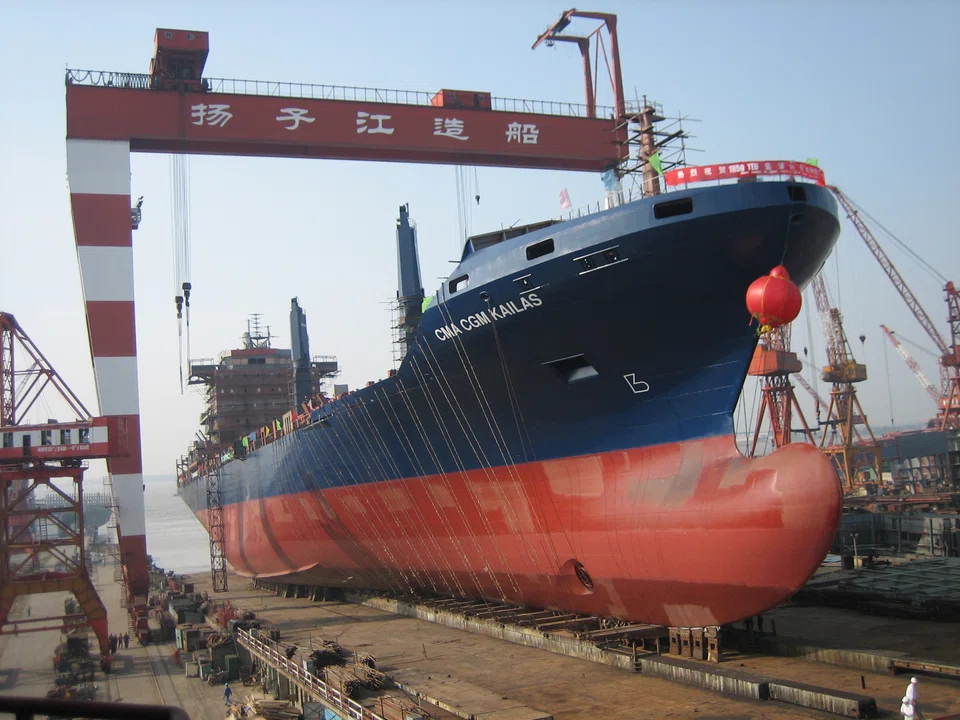
SHARES of Yangzijiang Shipbuilding (YZJ Shipbuilding) gained as much as 3.9 per cent during early trade on Friday (Sep 9) after the shipbuilder announced on Thursday a new licence agreement that would allow it to start constructing large liquified natural gas (LNG) vessels.
The index stock was the top-traded counter by volume at Friday’s opening bell, with more than 22.2 million shares changing hands. The counter reached an intraday high of S$0.945 before easing slightly to S$0.93 as at 9.53 am. It last traded near such levels in August. No married deals were recorded, according to ShareInvestor data.
YZJ Shipbuilding said in a bourse filing that it has obtained a GTT licence for the construction of vessels using GTT Mark III membrane technologies. GTT membranes have been widely chosen as the cargo containment and insulation system for the large LNG carriers, onshore and offshore applications.
Getting the GTT licence will allow the company to move up its technology value chain, to expand its offer to shipowners, and to contribute to the development of LNG vessel solutions, said the company in its bourse announcement on Thursday.
Said Ren Letian, executive chairman and chief executive officer of YZJ Shipbuilding: “The awarded licence will enable us to make strategic inroads into the large LNG carrier market, which we previously have not been able to penetrate into.”
Ren added that the group would now be focusing on building its credentials in the LNG space, and was “on track to meet the growing demand for green vessels”.
In a report issued on Thursday, CGS-CIMB reiterated its “add” call on YZJ Shipbuilding with an unchanged target price of S$1.63.
The research house suggested that the group’s shipping segment could see recurring cash flow due to high bulk carrier demand and locked-in charter contracts, despite freight rate weaknesses. Its analysts also welcomed YZJ Shipbuilding’s latest announcement on obtaining the GTT licence as they see it as a “step forward in YZJ’s ESG (environmental, social and governance) pursuit for greener vessels”.
In separate note on Friday, DBS was also upbeat on the shipbuilding group as it reiterated a “buy” call with a target price of S$1.40 over YZJ Shipbuilding’s “unwarranted share price weakness”.
“The recent GTT accreditation is a testament to Yangzijiang’s technical capability to build large LNG carriers, a big leap in its clean vessel transformation,” said analyst Ho Pei Hwa, who thinks the group is poised for an upwards rerating towards DBS’ target multiples of 1.5 times price-to-book ratio and 12 times price-to-earnings ratio.
Ho believes this could come as the group delivers strong earnings growth, and the shipping market for dry bulk and tankers stage a rebound from the second half of the year onwards.
DBS was also sanguine about the shipping market, as it expects demand and freight rates to improve sequentially in the third quarter.
“Moving into 2023, while rates for containerships may moderate, the outlook for dry bulkers, tankers and LNG carriers remains robust, despite the economic slowdown, as supply remains tight. This will continue to drive newbuild demand for shipyards,” DBS wrote.
“The market seems to have overlooked Yangzijiang’s earnings growth potential, the structural uptrend of shipbuilding demand, and the segment’s transformation into a clean vessel space.”
TRENDING NOW

‘We don’t want to stay as we are’: CEO Patrick Ng builds a more resilient Huationg

URA to review guidelines on floor space to give developers more design flexibility: Chee Hong Tat

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

32 companies, 6 individuals bag accolades at Singapore Corporate Awards 2026

