

Singapore’s private equity markets will keep growing even if stocks stay lacklustre
There are various ways for companies to raise capital without going public, says Hartley Rogers of PE investment giant Hamilton Lane
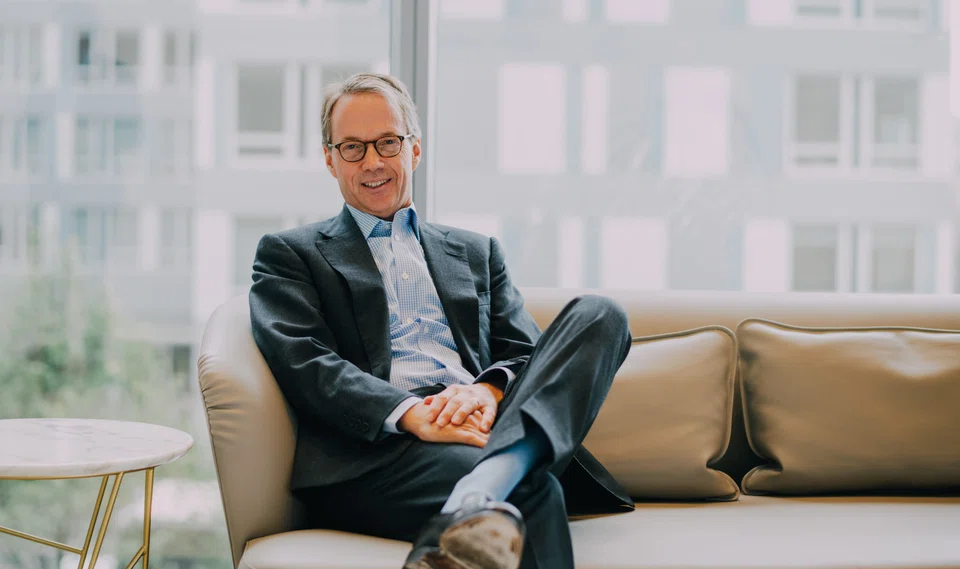
[SINGAPORE] The lack of vitality in Singapore’s stock market is not likely to hamper growth in the private equity (PE) space, as companies find other ways to raise funds, said Hamilton Lane, one of the world’s biggest private markets investment firms with more than US$947 billion in assets under management (AUM).
Pointing out that initial public offerings (IPOs) have generally fallen in the past few years in key global listing hubs, Hartley Rogers, executive co-chairman at the firm, told The Business Times in an exclusive interview that businesses can seek other capital-raising options, instead of going public.
“Broadly speaking, IPO activity in the world has come down. And I think that’s a more fundamental question, because what you have in the private markets is so much dynamism, so many different participants, so many different ways that they can play that it’s quite feasible today for a company never to go public.”
Singapore has announced initiatives to revitalise its stock market, after drawing the lowest number of IPOs since 2011 last year. Four companies raised a total of S$45.9 million on Catalist, the so-called junior board on the Singapore Exchange (SGX), in 2024. On the other hand, a total of 20 companies delisted.
While SGX, brokers and investment bankers have expressed optimism of a pick-up in IPOs this year, there are potentially five companies that could delist, since they announced they had received offers to privatise.
London, which used to be viewed as a key global listing hub, logged 18 IPOs last year, the lowest since the global financial crisis in 2009. The amount raised, at £737 million (S$1.3 billion), was the smallest on record, according to Dealogic. While companies raised around US$40 billion on US bourses via IPOs, the most since 2022, it is still a sliver of the record US$316.6 billion in 2021.
“That’s the change in the world – the rise of private markets, without... having to have IPOs,” Rogers said on a recent visit to Singapore. Before joining Hamilton Lane in 2003, he was a managing director in the PE fund management areas at Morgan Stanley and Credit Suisse.
Active PE market in Singapore
An active IPO market can also encourage more PE activity, particularly for buyout groups. These rely on the ability to sell or list companies – usually within three to five years of buying them – to generate returns for the pension funds, insurance companies and others whose money they manage.
But Rogers points to the different exit avenues. With more players, including mutual funds and other investment vehicles having allocations in private markets, investors can make more money buying and selling their private interests.
Singapore’s PE market has been active, accounting for nearly half of the total number and value of PE deals in South-east Asia last year, which amounted to US$15.8 billion, according to EY. And the private market is primed for more activity after Prime Minister Lawrence Wong announced the launch of a S$1 billion Private Credit Growth Fund to help high-growth Singapore companies access capital.
Noting that governments globally have started such funds, Rogers said the track record is “all over the map”. “There are places where governments have taken too heavy a hand, and there are places where they haven’t.”
But he said the outlook for Singapore’s fund is “pretty good” because the country has both a dynamic target market that is big, as well as a history of government-sponsored investment that is “generally done well”, referring to Temasek and GIC.
And this is against the backdrop of growing optimism over private markets globally. Rogers attributed this to the focus of the current US government on cutting administrative burden, regulations and barriers to doing business.
Another reason is that PE markets have a better shot at outperforming equities, especially after the key US benchmark S&P 500 soared by 25 per cent each in 2023 and 2024.
“Going forward, over the next couple of years, you have to wonder if the public markets will continue to go up so much.” Pointing to research going back decades to predict what happens next, he added that “inevitably there is some kind of flattening out or retrenchment in the public markets, and then the private markets will look very, very good”.
As for investment focus, apart from searching for opportunities within Asia, Asian investors are also looking at other regions to diversify, particularly as they pivot away from China.
PE investors “have to be” in Asia
Giving an overview of the PE landscape in Asia, Rogers said there is broad diversity: from a mature economy such as Japan, where PE activity is thriving with a focus on buyouts, to India where the potential for growth and abundant investment in infrastructure lead to the formation of many new companies.
South-east Asia is presenting opportunities in supply chain management as labour costs have risen in China, with investors looking at several of the key Asean countries to “create elements of their supply chain”.
“If you’re taking a long-term perspective, you really have to be here. And it’s not just Asian investors that are interested in Asia; the longer-term-oriented investors in the US, Europe and the Middle East are (also) very interested in investing in Asia,” he said.
The Pennsylvania-based company has been active in Asia for more than 20 years, where the total AUM was around US$155 billion at the end of last year. Its headcount in the Asia-Pacific – which includes Australia and New Zealand – was 54, compared with about 740 globally.
Rogers expects the region’s contribution to Hamilton Lane’s total business to rise in the next 10 to 15 years, without specifying. The Asia-Pacific accounted for 23 per cent of its global revenues last year.
While the United States is likely to maintain its lead as the world’s largest PE market, Rogers said its current dominance – around 70 per cent – is likely to fall relative to the other regions in the next five to 10 years, as the latter, particularly Asia, expands.






