

CapitaLand Ascott Trust H1 DPS falls 8% to S$0.0255; CEO says top-up to distribution is ‘an option’
The managers attribute the decline mainly to the depreciation of foreign currencies against the Singapore dollar
CAPITALAND Ascott Trust (Clas) posted an 8 per cent drop in distribution per stapled security (DPS) to S$0.0255 for the first half ended Jun 30, from S$0.0278 in the year-ago period.
On Friday (Jul 26), the managers attributed this decline mainly to the depreciation of foreign currencies against the Singapore dollar.
Excluding non-periodic items related to realised exchange gain from the settlement of cross-currency interest rate swaps, DPS inched down by 1 per cent year on year at S$0.0241.
Revenue for the half-year period stood at S$386.4 million, up 11 per cent from the S$346.9 million recorded in the same period the year before.
Clas’ gross profit rose 12 per cent to S$172.9 million from S$154.4 million.
The managers attributed the increase in revenue and gross profit to higher revenue of S$11.8 million from its existing portfolio and S$38.2 million in additional contributions from acquisitions.
This was partially offset by a drop in revenue from the divestment of a hotel in Australia, three properties in Japan and a serviced-residence property in Singapore in the first quarter of 2024.
In a press briefing on Friday, Serena Teo, chief executive of Clas’ managers, said the trust has done 10 divestments since 2023, which have generated S$408.1 million in proceeds at a premium to book value, and an exit yield of 3.8 per cent.
“We have recycled some of the capital... more than 60 per cent has been used to pare down some floating debt, resulting in immediate accretion to DPS,” she said.
Lui Chong Chee, chairman of Clas Management and CapitaLand Ascott Business Trust Management, said: “This strengthens our financial capacity to redeploy capital towards optimal and accretive uses.”
Clas’ portfolio reconstitution strategy – including acquisitions, divestment and ongoing asset enhancement initiatives (AEIs) – is still underway. It added that the AEIs, when completed, are expected to lift its distribution income.
Teo noted that such AEIs could lead to DPS impact, but did not rule out the option of top-ups, such as through the distribution of capital gains, while the initiatives are ongoing.
While Clas has the ability to distribute capital gains, it has not done so for the first half, as it intends to redeploy proceeds for “more optimal uses”, including the paring down of debt or acquiring more assets. This is as such initiatives are likely to provide higher returns on investment when completed.
However, this is “always on the table” for Clas to consider, given that it has the capacity to distribute these gains, she added.
Clas made a top-up to its distributions to stapled security holders after completing the acquisition of The Cavendish London, as the property is slated to be closed for AEI in 2025, noted Teo. (The acquisition was announced in 2023.)
Asked whether the board has a cap on the amount Clas could top up to distributions from its capital gains, she said there was “no arbitrary limit or cap”.
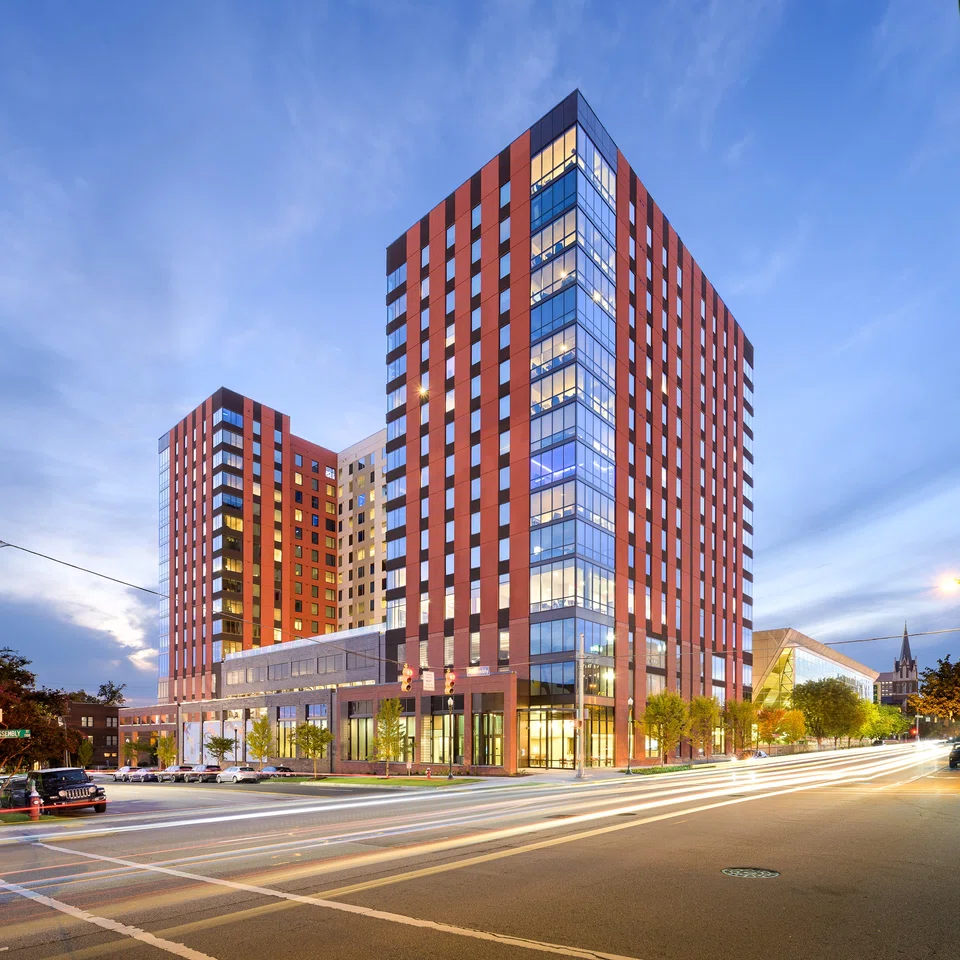
The stapled group acquired three turnkey rental-housing properties in Japan, three properties in Indonesia, Ireland and the UK, as well as one student-housing asset in the US.
When asked what the trust looks for when considering its assets, Teo said: “For divestment, we typically would be more open to divesting assets that we feel have reached their optimal level in terms of returns to the trust.” For example, assets located in places where additional capital expenditure to upkeep might not yield an accretive return to Clas.
As for assets, the trust tends to prefer developed markets, as well as “key markets that are resilient in terms of demand”.
The stapled group’s H1 total distribution inched up to S$96.5 million from S$96.3 million in the corresponding period of the previous year. The distribution will be paid out on Aug 29, after the record date on Aug 5.
For H1 2024, Clas recorded a 5 per cent increase in revenue per available unit (RevPau) of S$145. On a quarterly basis, RevPau for the second quarter of 2024 rose 4 per cent to S$155, reaching 102 per cent of the pre-pandemic levels of Q2 2019 on a pro forma basis.
The increase in RevPau could be attributed to higher room rates, led by Japan and the US, said Clas.
RevPau of its Japan properties rose 30 per cent in H1 2024, driven by higher leisure demand from tourists and the cherry blossom season. Meanwhile, RevPau for its US properties increased by 3 per cent due to higher corporate and leisure demand.
Clas’ gearing stood at 37.2 per cent as at Jun 30, with a debt headroom of about S$1.2 billion, based on an aggregate leverage limit of 45 per cent. The stapled group’s total debt on fixed rates stands at 82 per cent and it has some S$1.29 billion in cash and available credit facilities.
Its average cost of debt stood at 3 per cent per annum as at end June, and the managers expect this to remain stable until the end of the year. This is because about 82 per cent of Clas’ debt is on fixed rates and the weighted average debt to maturity is 3.6 years, they added.
The managers said Clas is expected to remain resilient as its geographic diversification, lodging asset classes and different contract types provide a balance and stable growth income.
Teo also expects that regular travel patterns and seasonality could return in more markets as pent-up demand for travel moderates. “Clas maintains a cautiously positive view on the demand for lodging,” she added.
Stapled securities of Clas were trading 0.6 per cent or S$0.005 lower at S$0.895 as at 9.15 am on Friday.
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Could stablecoins be the future of money?
ST Engineering opens tech-focused aircraft maintenance facility in Changi; to create over 500 jobs

