CapitaLand China Trust posts 3.1% drop in H1 DPU to S$0.041
Vivienne Tay &
Jude Chan
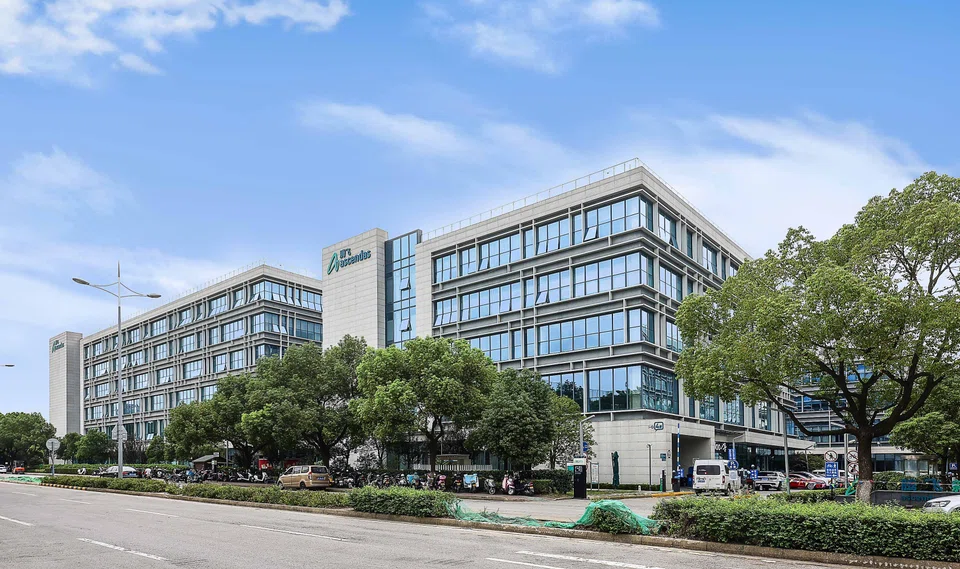
CAPITALAND China Trust (CLCT) on Tuesday (Jul 26) posted a 3.1 per cent year-on-year drop in H1 DPU to S$0.041 after opting to retain S$3.6 million of the amount available for distribution for financial flexibility.
Excluding the amount retained, DPU would have been 2.1 per cent higher on the year at S$0.0432, the real estate investment trust (Reit) manager said.
“The retention is more because, as we close the books in the first half, things are just going back… There’s still that element of uncertainty,” Tan Tze Wooi, chief executive of CLCT’s manager, said at a briefing accompanying the result announcement. “Although we see things are improving, because of China’s zero Covid policy, there will be a bit of this recurring or sporadic restrictive measures in place on our business.”
“We are looking forward to the second half, cautiously hoping that things will be better,” he added. “Business confidence, consumer sentiment and retail spending will take a little bit of time to pick up.”
This brings the distribution yield, on an annualised basis, to 7.1 per cent, based on CLCT’s closing price of S$1.16 on Jul 25. As at the midday trading break on Tuesday, CLCT was trading 0.9 per cent or S$0.01 higher at S$1.17.
The China-focused real estate investment trust reported a net property income of S$139.5 million for the 6 months ended Jun 30, 15.9 per cent higher than the year-ago period.
The manager noted that this was mainly due to an enlarged portfolio and strong contributions from CLCT’s business parks and logistics assets, partially offset by higher rental relief for retail tenants.
Gross revenue was 12.7 per cent higher at S$199.3 million for the half-year period. The manager attributed the growth to the full-half-year contribution from the acquisition of 5 business parks and 4 logistics parks completed in 2021.
The amount available for distribution to unitholders for the period was S$72.3 million, 12.9 per cent higher than the S$64.1 million reported in H1 2021. After retaining S$3.6 million, the distributable amount to unitholders is S$68.7 million, representing instead a 7.2 per cent rise year on year.
The distribution will be paid on Sep 22 after the record date on Aug 3.
CLCT’s retail portfolio occupancy stood at 95.5 per cent as at Jun 30, with improvements in shopper traffic and tenant sales from June 2022 onwards. The occupancy of its business parks and logistics assets stood at 94.7 per cent and 97 per cent respectively, supported by tenants in high-growth sectors.
As at end-June, the Reit’s gearing was 38.6 per cent. The manager noted that the Reit’s debt maturity profile remains “well-staggered”. Its borrowings have an average term to maturity of 3.1 years as at Jun 30.
Tan said that CLCT’s H1 2022 performance was underpinned by the Reit’s pivot towards the more-resilient business parks and logistics asset classes, coupled with a rejuvenated retail portfolio.
“With cities adopting more targeted containment measures and the government rolling out stimulus policies, we are cautiously optimistic that the operating environment in China will improve in H2 2022.”
CLCT has also been engaging in asset enhancement initiatives (AEIs) in preparation for an anticipated upturn in activity. The ongoing AEI for CapitaMall Wangjing to optimise about 14,000 square metres of space is on track for progressive completion from Q3 2022.
Meanwhile, CapitaMall Grand Canyon, previously occupied by a mini anchor tenant, will complete reconfiguration by Q4 2022 to optimise its tenant mix. The manager expects a return of investment of more than 40 per cent, it added.