CapitaLand Investment back in the black with S$148 million H2 profit; proposes special distribution of CICT units
This translates to an earnings per share of S$0.03
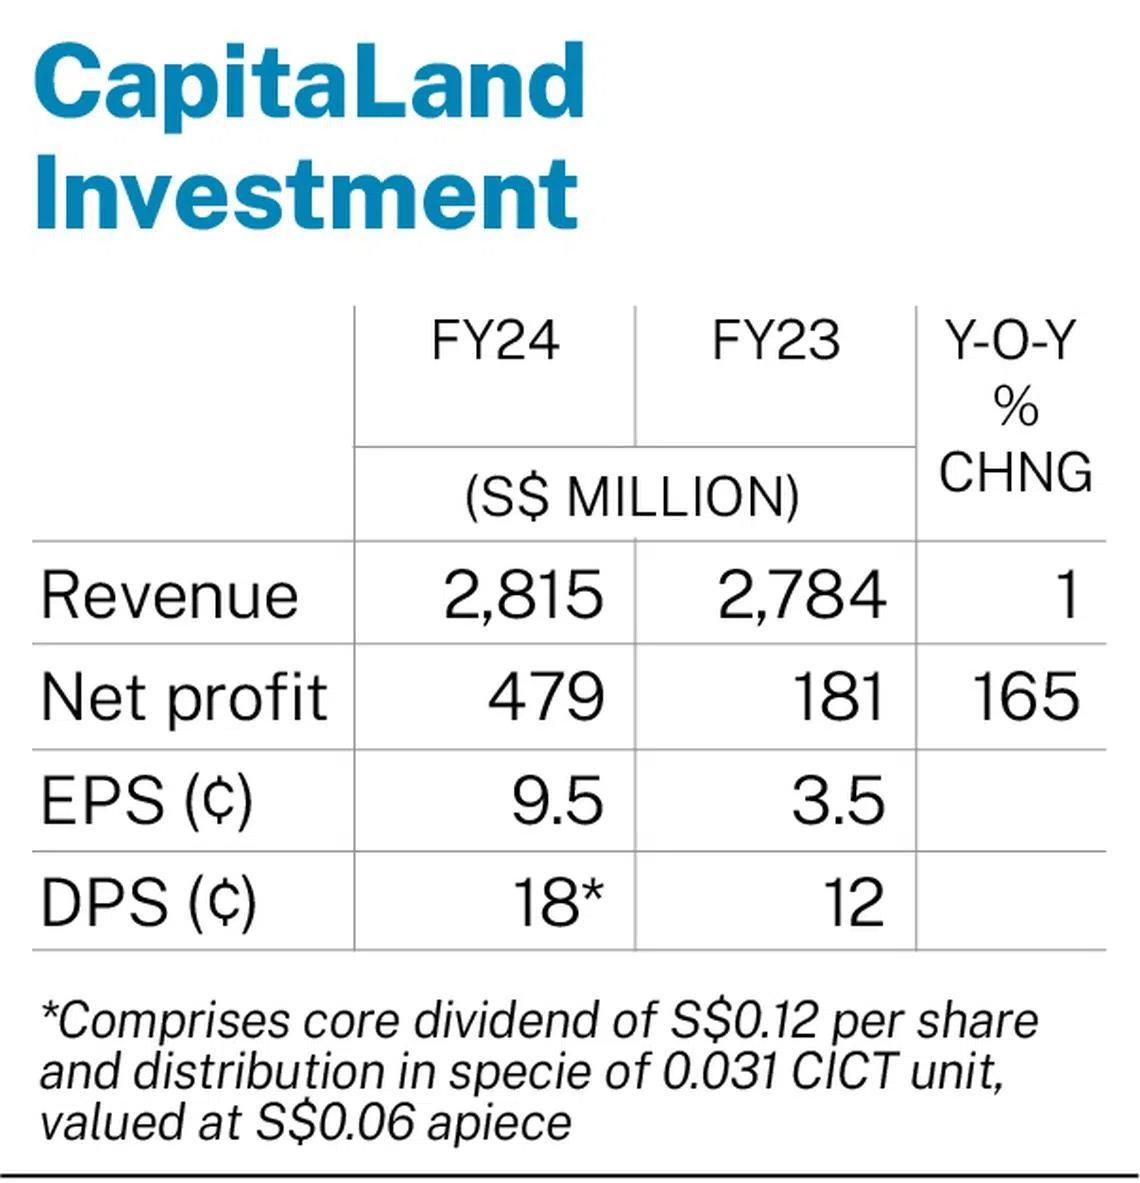
THE board of real estate group CapitaLand Investment (CLI) proposed on Thursday (Feb 27) to distribute a core dividend of S$0.12 per share, as well as a special dividend-in-specie of 0.031 CapitaLand Integrated Commercial Trust (CICT) unit per share – valued at S$0.06 apiece. This brings the total dividend for financial year 2024 to about S$0.18.
The decision to issue a special dividend-in-specie – which are distributions based on assets other than cash – will help CLI to improve its return on equity by reducing its capital base, explained Paul Tham, the group’s chief financial officer.
The proposed distribution is also in line with its ongoing capital management and asset-light growth strategy, added CLI in a bourse filing.
Tham, who was speaking at CLI’s financial results briefing on Thursday, said that the group’s cash flow is strong enough to maintain good dividends for shareholders, and the proposed dividends are intended to reward long-term CLI shareholders.
CLI swung to a net profit of S$148 million for its second half ended December, from a net loss of S$170 million in the previous corresponding period.
This translates to an earnings per share (EPS) of S$0.03, compared with a loss per share of S$0.033 in H2 FY2023.
The improvement in the bottom line came amid reduced losses from the revaluation of investment properties, said the group.
It noted that in H2 FY2024, net portfolio gains from asset recycling declined slightly to S$195 million.
This is because the overall gains were partially offset by the loss arising from the deconsolidation of CapitaLand Ascott Trust, which included non-cash realisation of foreign currency translation losses and remeasurement of the retained stake, said CLI.
Excluding gains or losses from divestments, revaluations and impairments, operating net profit fell 4 per cent on the year to S$214 million.
The decline was mainly due to the absence of contribution from divested properties, partially mitigated by higher fee income from CLI’s fee income-related business, said the group.
Special dividend
In a separate bourse filing, CLI said it plans to distribute up to 155 million units in CICT that it holds, representing about 2.12 per cent of the units in CICT.
It noted that the payout would enable shareholders to participate in the growth of Singapore’s largest real estate investment trust. For FY2024, CICT’s revenue grew by about 1.7 per cent on the year, while net property income rose by around 3.4 per cent.
After the payout of the special distribution, CLI will remain CICT’s largest unitholder with about 21.21 per cent of CICT units.
CLI also revised its dividend policy to 50 per cent of cash profit after tax and minority interests (Patmi), up from 30 per cent previously. Cash Patmi refers to the sum of operating Patmi, portfolio gains or losses and realised revaluation.
“When we look at our cash flow in the longer term, we believe we can maintain our numbers quite comfortably,” said Tham, noting that its current dividends are already above the revised dividend policy.
CLI revenue up
CLI’s revenue for the second half was up 1 per cent on the year at S$1.5 billion.
The slight improvement in the top line came amid an increase in acquisition fee income generated from the fund management business, partially offset by lower rental income from investment properties due to divestments in the US, Australia and China.
For the full year, CLI recorded a net profit of S$479 million, from S$181 million in the previous corresponding period. This translates to an EPS of S$0.095 for FY2024, up from S$0.035 in the previous year.
Revenue for the full year rose 1 per cent to S$2.8 billion, driven by contributions from fee income-related business, which grew 9 per cent on the year.
The fee income-related business includes four segments: listed fund management, private fund management, lodging management and commercial management.
Notably, the private funds management segment logged a 10 per cent increase in revenue, said CLI.
Lee Chee Koon, group chief executive of CLI, said: “CLI is well-positioned to pursue organic and inorganic growth opportunities, having further strengthened our talent bench through our strategic platform acquisitions and new senior hires.”
He added that the group is “on track” to achieve its target of S$200 billion funds under management (FUM) by FY2028. Its FUM is currently S$117 billion.
Investing for growth
With CLI’s gearing at 0.39 times – its lowest in two decades – the group now has room to grow through its investments, said Tham.
Therefore, divestments will be “less critical” to CLI’s strategy, and the group will focus on investing in platforms through mergers and acquisitions, as well as warehousing assets.
Looking ahead, CLI will generate more of its income through fund management fees, and less so from its real estate investment business, said Tham.
This is in line with its efforts to be viewed as a real asset manager, rather than a property investment company.
Shares of CLI ended Wednesday 0.8 per cent or S$0.02 lower at S$2.50.