

CapitaLand's restructuring move is not for everyone, say analysts
Other locally listed developers may not have the size and scale to pull off such a change, they say
Singapore
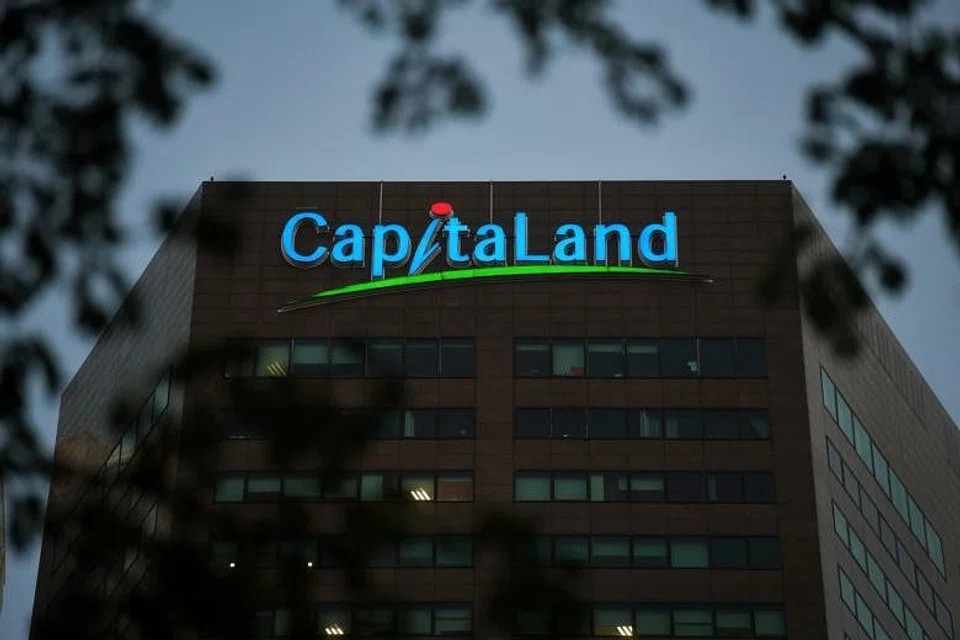
CAPITALAND'S restructuring deal seems the perfect solution to the middling valuations that the market has been awarding to property developers, but market watchers said replicating the deal may be difficult for locally listed developers without similar size and scale.
On Monday, CapitaLand announced a deal that will place its real-estate development business under private ownership, and consolidate its investment-management platforms and lodging arm into a new listed entity called CapitaLand Investment Management (CLIM).
CapitaLand had been trading at a discount to its book value of S$4.30 a share for some time, and the restructuring is expected to help shareholders realise some of that value.
If CLIM does indeed trade at a premium to its book value, other property developers may be prompted to do the same.
But CGS-CIMB analyst Lock Mun Yee said CapitaLand has a "unique business model" spanning property development, investment and fund management, as well as a full-stack lodging platform. It is this depth and breadth that has "enabled the group to strategically reorganise its structure to optimise growth", she added.
With assets under management of about S$115 billion, CLIM is expected to be the largest real-estate investment manager (REIM) in Asia, and the third-largest listed REIM company globally.
Frasers Property, Keppel Corporation and Mapletree are potential candidates for similar restructurings, suggested Jefferies equity analyst Krishna Guha, because of their "relatively significant presence in listed real-estate investment trusts (Reits) and private funds".
RHB analyst Vijay Natarajan cited City Developments (CDL) as another possibility.
He added, however, that CDL is facing another set of challenges: Its joint-venture investment in Sincere Property Group is facing some balance sheet difficulties. While there may be an option for CDL to carry out a restructuring similar to CapitaLand's down the road, such a consideration may not be "a suitable thing for them" to undertake now.
Meanwhile, other smaller developers are unlikely to be able to follow suit, Mr Natarajan said. Some of them may not have as large of an asset-management platform; others may not have access to a capital recycling platform in the form of multiple Reits.
On why size is such an important factor, Joel Ng, head of Singapore Research at KGI Securities (Singapore), said developers will have to factor in considerations such as the additional costs in finance, administration and procurement for a separate company. As a result, "the benefits of such a split structure may not be as clear cut".
He added that smaller real-estate asset managers will still likely face a valuation gap, even while they "forgo the flexibility of having the two functions (of manager and developer) in the same company".
Investors tend to look at the branding of a manager, its pipeline of new projects, as well as its track record. And they will likely gravitate towards those who "benefit from scale and who have established backing", he said. This is already evident among the S-Reits, where there is a "clear premium" accorded to the larger Reits backed by government-linked entities over the smaller ones.
There may also be value to some property developers in not jumping on the bandwagon - not just to gauge the market appetite for a structure like CLIM's, but also to see if investor sentiment turns.
DBS Group Research analyst Derek Tan believes that there is still value for a real-estate origination business model, given the ability to land bank and sell across market cycles to generate profits.
The past year has generally been a difficult one for real-estate developers, as investors have shown a preference for growth stocks and those with the potential to benefit from the pandemic. Old-economy plays, particularly banks and property, were overshadowed by technology counters and glove-makers.
There have, however, been a number of privatisations in recent months as major shareholders have taken advantage of low market valuations to make offers at low prices. Investors may yet see activity among the property developers.
READ MORE:
TRENDING NOW
How Vietjet’s US$250 million global asset freeze complicates its 600-aircraft financing plans
Work Permit holders increase by 10,900, but S Pass, EP holders decline by 900 each in Q2: Jasmin Lau
US midterms: What investors can expect after Democrats shatter Republican strongholds

The AI frenzy gets a reality check

