

Cash management is king for DBS
It is expected to hit its 2020 target to quadruple its cash management business by this year and will expand its transaction banking business in Vietnam, China
Singapore
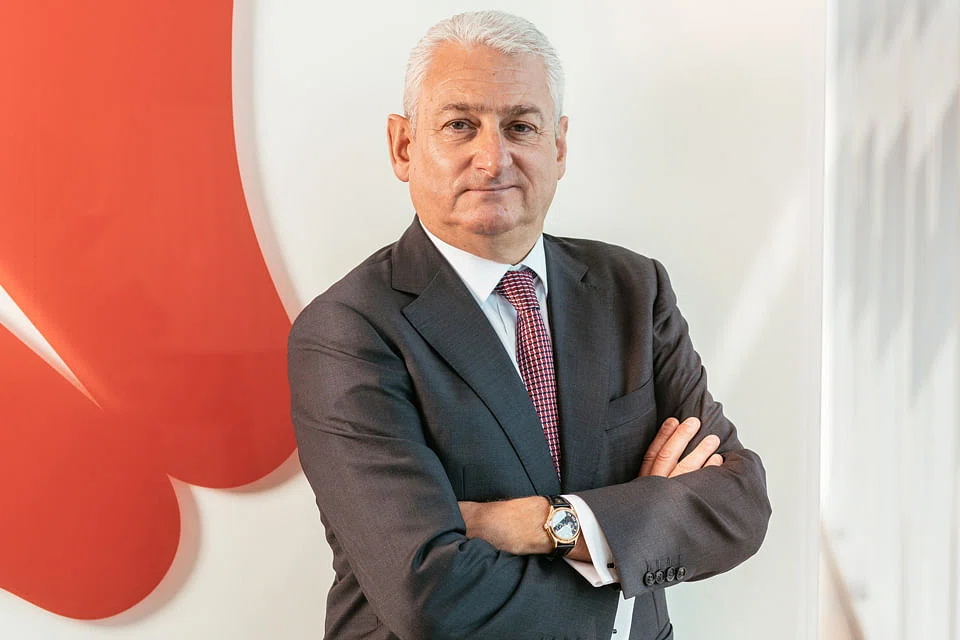
DBS looks to hit a five-year target to quadruple its cash management business by 2020 a year ahead, and will expand its transaction banking business in growth markets such as Vietnam and China's Greater Bay Area, said John Laurens, DBS group head of global transaction services (GTS).
With the uncertainties from the US-China trade war, the bank is starting to see the re-plumbing of trade flows within Asia, Mr Laurens told The Business Times.
Vietnam is frequently brought up as one of the key benefactors within the region. With that, DBS is increasing the size of its overall transaction banking business in Vietnam, with plans to grow GTS revenue by 30 per cent over the next five years. It also targets to triple the tech investments in cash management solutions there to support growing trade financing and cash needs.
China's Greater Bay Area is another promising market for DBS, with plans to grow its GTS revenue by 55 per cent in the next five years.
Cash management entails helping companies to manage their cash flow through deposit accounts, payables and receivables management services and liquidity management solutions, and is "absolutely core to corporate customer relationships", said Mr Laurens. "If you are not the cash management bank to a company, it is unlikely that you will be a core or lead relationship bank."
The overall global transaction banking business revenue at DBS has grown from S$1.59 billion in 2015 to S$2.45 billion in 2018, representing a compound annual growth rate (CAGR) of about 15 per cent. This comes amid a shift in the transaction services landscape from the time that Mr Laurens joined the bank in late 2014 from HSBC, he said.
Back then, trade finance formed the bulk of transaction services revenue at 70 per cent, with cash management making up the rest. Trade finance refers to financial instruments and products used by companies to facilitate international trade and minimise risk. Trade finance now makes up about 30 per cent of the global transaction services business at DBS, having been hurt by a slowdown in China and falling commodity prices.
Mr Laurens said: "A lot of this has to do with structural changes in the marketplace which has led to a big compression in margins."
Today, income from cash management has sped up to become the main growth driver for the transaction services business, contributing about 70 per cent. Revenue from DBS's cash management business registered a three-year CAGR of 39 per cent between 2015 and 2018.
DBS's ramping up of digital capabilities, on the back of the blistering pace of technological change, has been a key driving force behind the growth in cash management.
Mr Laurens added: "There's no question that the larger the bank, the greater the legacy and the slower the change.
"We are turning this on its head. Today, we don't have this kind of a weighted legacy."
Instead of spending money to maintain traditional legacy architecture through software licences, the bank is using open source capabilities to eliminate costs, he added.
This has allowed DBS to move quickly in terms of using digital means to explore new business propositions to meet customer needs.
For instance, the bank has close to 500 application programme interface (APIs) solutions, out of which 168 were developed for transaction banking clients - and are all used regularly. APIs - one of the latest buzzwords in the banking world - help enable other brands, corporates and fintechs to integrate their services with the bank.
DBS's digital strategy has helped close a number of mandates from big multinational names when it comes to cash management, including those in the new-tech space. Among them are Indonesian unicorns Gojek and e-commerce player Bukalapak.
The "hot sectors" that Mr Laurens is eyeing include insurance, logistics, e-commerce, health care and pharmaceuticals. Opportunities for the transaction banking business will continue to be driven by going digital, he said.
"To be at the forefront, we need to not only understand and apply technology in terms of driving our business, but also to provide the kind of advisory for our customers that they are looking for as they continue to explore and pursue their digital journeys," he noted.
This means being conversant with the technology stacks of customers, and helping them to manage and process data and use it for their business. While digital readiness in the marketplace and geopolitical issues are some potential roadblocks, Mr Laurens remains confident about the future of the business.
"Transaction banking will become one of the most fast-moving, technologically advanced aspect of banking - this is a good place to be," he added.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Singapore’s S$80 million vertical farm must pass the 50-cent test to succeed
Data centre energy demand from Asean telcos not a ‘big risk’, says industry group

