

CDL Hospitality Trusts H1 DPS jumps 67.2% on strong leisure demand
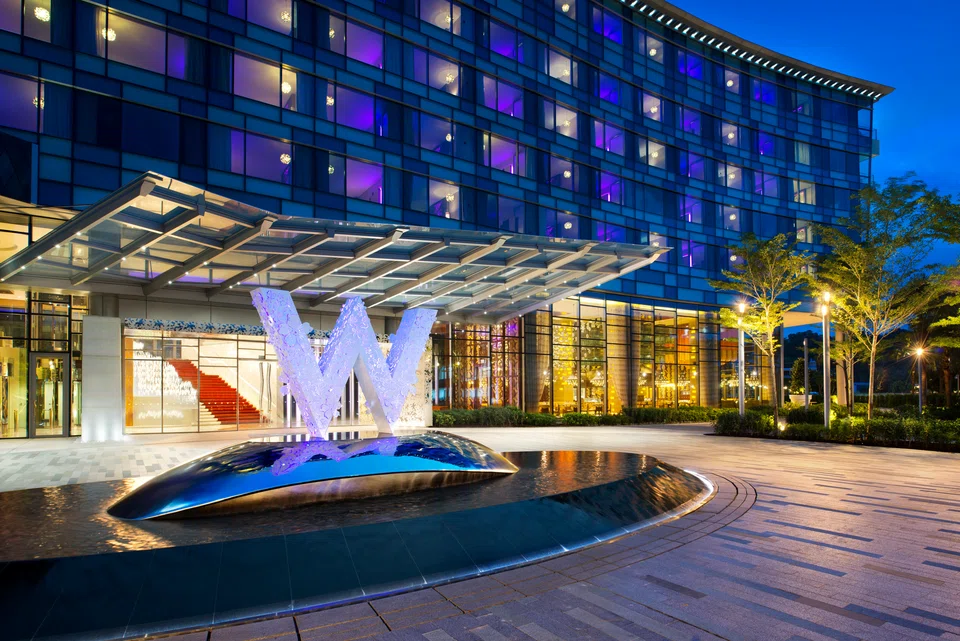
CDL Hospitality Trusts ’ distribution per stapled security (DPS) rose by 67.2 per cent to S$0.0204 for its first half ended Jun 30, from S$0.0122 a year ago, as leisure demand accelerated in the second quarter.
The strong demand was seen in the stapled group’s hotels in Singapore and the UK, as well as resorts in Maldives, where net property income (NPI) collectively grew by S$16.9 million in the half year, the group’s managers said in a bourse filing on Friday (Jul 29).
Behind the NPI growth is an almost doubling of revenue per available room (RevPAR) for the Singapore hotels in the second quarter to S$151, from S$76 over the same period a year ago.
H1 RevPAR for their Singapore hotels, which include Grand Copthorne Waterfront Hotel and W Singapore Sentosa Cove, therefore came in at S$123, up 72.1 per cent from S$72 a year ago.
RevPAR for their Maldives resorts also grew by a substantial 64 per cent to hit US$381, while that of their UK hotels came in at £107 (S$180), up from £30 in the first half of 2021.
The managers added that a firm recovery is now evident, except for a few regions in the group’s portfolio.
The Australia and New Zealand portfolio collectively recorded a S$4.8 million drop in NPI for the half year on a reduction in Grand Millennium Auckland’s room utilisation rates as a managed isolation facility and state-wide Covid-19 restrictions that stuck around up till late April in Perth.
Meanwhile, NPI growth is relatively muted for their Japan hotels amid the lack of international arrivals, improving 32.2 per cent to S$189,000 from a low base of S$143,000 in the first half of last year on domestic travel.
Gross revenue was up 49 per cent on year in the half year to S$98.6 million from S$66.2 million, while NPI grew 37.8 per cent to S$51 million, from S$39.6 million.
NPI growth for the second quarter itself came in at 55.4 per cent as income jumped to S$26.8 million in the period, from S$17.2 million over the same period last year.
Apart from the hotels and resorts, the managers said NPI growth was also contributed by Claymore Connect, a retail property under the group’s portfolio. Its NPI grew S$1 million in the half year due to continued tenant recovery and the normalisation of Singapore’s retail trade, they highlighted.
At a briefing on Friday, Vincent Yeo, chief executive officer of CDLHT’s managers, told reporters that the group is “still in acquisitive mood” following a series of acquisitions, which included Manchester’s Hotel Brooklyn in February and a UK build-to-rent development project last August.
On this front, Yeo said purpose-built student accommodation remains an “interesting proposition” as the ratio of students to bed is still very high, indicating that a high “unsatisfied demand” exists.
Rental housing also presents an opportunity, he added, pointing out that there is a situation in the UK where many millennials are finding it tough to transit from renting to owning a home amid a rising interest rate environment.
Meanwhile, the managers will continue to focus on hospitality, given a “widespread revival” in the sector currently, he said. “We are waiting for the Japan market to fully reopen. Once it opens, the Japan market will boom as well,” he added.
Yeo also acknowledged that while the group is fighting to protect margins amid rising labour costs and the Covid-induced fall in transient corporate travel demand, there is still more room for hotel room rates to grow.
This is as he observed that the amounts people are willing to spend on leisure are higher than pre-pandemic levels, he said.
He added: “My speculation is that there is an element of Yolo (you only live once) in the mentality of the travellers, and therefore, they’re prepared to stay longer, pay more for a good experience, do more activities whilst they are travelling.”
Stapled securities of CDLHT were trading at S$1.33 as at 2.24 pm on Friday, down S$0.02 or 1.5 per cent, after the release of the latest financials.
CDL Hospitality Trusts is a stapled group comprising CDL Hospitality Real Estate Investment Trust and CDL Hospitality Business Trust.
TRENDING NOW
Singapore tech stocks plunge as Nasdaq bloodbath spills into region

S$3 billion money laundering case: Rare Pateks and Rolexes, diamond-covered Hermes and more head to auction

OCBC Q3 profit rises 3% to S$2.04 billion, slightly above expectations

From legacy to launch: Francis Yeoh and Yeoh Pei Xien on family unity and YTL’s next‑gen ventures

