China Reits could give S-Reits some competition
Given the vast properties in North Asia that could be injected as assets, C-Reits have tremendous potential
Singapore
CHINA real estate investment trusts (C-Reits) might give Singapore Reits (S-Reits) a run for their money, given the vast properties in the North Asian country that could be injected as assets.
While C-Reits are starting in a modest way, they have "tremendous" potential, said Gabriel Yap, executive chairman of investment firm GCP Global.
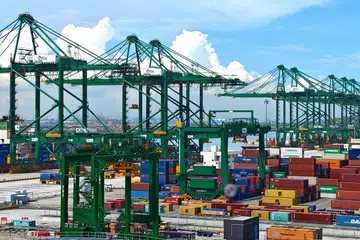
The first crop of nine Reits, including GLP C-Reit, with a total portfolio value of 31 billion yuan (S$6.45 billion) will list on the Shanghai and Shenzhen stock exchanges on June 21.
These C-Reits - comprising three industrial park Reits, two warehouse Reits, two toll road Reits and two waste management Reits - have reported an average oversubscription rate of about seven times, with a majority of them priced at a premium over valuation, according to a DBS Group Research report.
The five industrial property C-Reits have expected yields of 4-4.5 per cent (FY2022) while the toll road and waste management Reits have yields of 7-10 per cent, according to the DBS research report.
C-Reits are required to distribute no less than 90 per cent of their income as dividends. They are currently not available to foreign investors, but they could serve as valuation benchmarks for S-Reits with a focus on China assets, DBS noted.
Mr Yap stated that China has a plethora of properties as potential Reit assets - far wider choices compared to Singapore - which could give S-Reits some competition. Also, he noted, the Chinese Big Tech companies are now adopting an asset-light strategy that might see them spin off their logistics properties, industrial parks and warehouses as Reits.
Natalie Ong, analyst at Phillip Securities Research, said the S-Reit market has a head start with 42 listed Reits and business trusts, providing exposure to various types of property assets in Singapore and other countries.
S-Reits, Ms Ong added, are also subject to more stringent disclosure obligations, compared to C-Reits. "One of the factors that contributes to the appeal of S-Reits is the clear and stringent guidelines on asset allocation, leverage, interest coverage and inter-party transactions. For example, S-Reits must disclose proposed transactions that are between 3 per cent and 5 per cent of its net asset value (NAV), and they must obtain shareholder approvals for proposed transactions equal to or greater than 5 per cent of NAV.
"In contrast, acquisitions sized below 20 per cent of the C-Reit's net assets only require disclosure, while acquisitions sized between 20 per cent and 50 per cent require majority shareholder approval and those exceeding 50 per cent require two-thirds shareholder approval. The more stringent threshold for S-Reits impose a higher level of transparency and accountability, and give minority shareholders more control over their investment," Ms Ong noted.
There are three factors to assess when investing in C-Reits should they become available to Singapore investors: capital gains, relative yields, and the foreign exchange movement of the yuan vis-a-vis the Singapore dollar, Mr Yap stated.
But it could take a while before one is able to better evaluate the performance of C-Reits in terms of liquidity, participation and accessibility, going by the S-Reits experience. S-Reits took several years to take off, after the debut of CapitaMall Trust (now CapitaLand Integrated Commercial Trust) as the first S-Reit in 2002.
Mr Yap noted that the initial strong interest in C-Reits bodes well for S-Reits, and he has seen growing interest among Chinese family offices in the asset class.