

China’s real estate woes weigh down S-Reits, but retail sector could be bright spot
Rental reversions in the segment are starting to turn positive amid a recovery in consumer spending
SINGAPORE-LISTED real estate investment trusts (S-Reits) with exposure to China will continue to see downward pressure on their valuations in the coming quarters amid the ongoing slump in China’s property market.
However, the country’s retail sector, which is starting to see positive rental reversions, will be a bright spot in the otherwise gloomy real estate market, said market analysts in comments on the latest season of financial results.
Latest results
The property market in China has been in a protracted slump since 2021, after the Chinese government’s crackdown on developers’ high reliance on debt for growth.
This has led to some Singapore companies with exposure to China’s property sector facing challenges not seen in recent years.
Pure-play China Reits reported lower distributions in their latest financial results. BHG Retail , which has a portfolio of retail properties in Chinese cities such as Beijing and Chengdu, saw its distributable income fall by 27.8 per cent to S$1.3 million; its distribution per unit (DPU) also fell, by 28.6 per cent to 0.25 Singapore cent for the first half of this year.
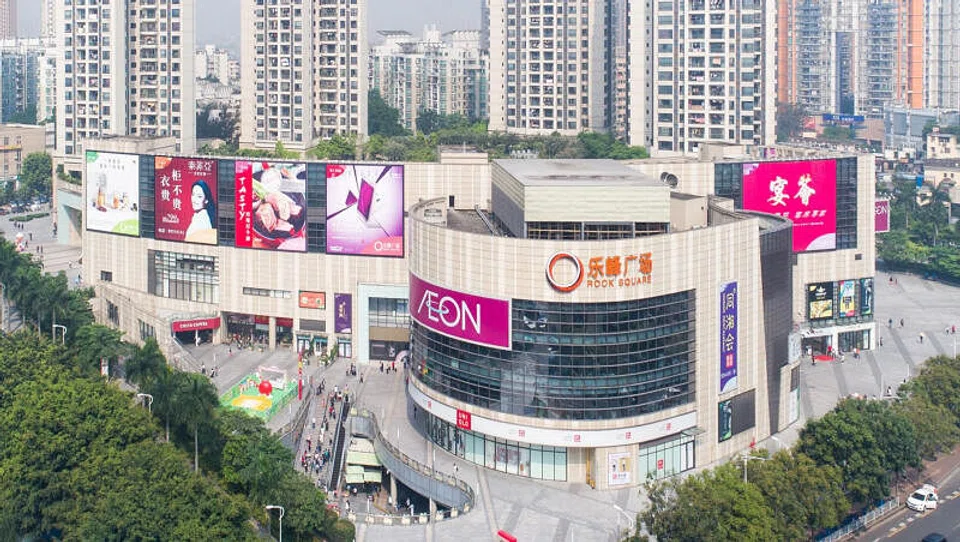
Likewise, the distributable income of Sasseur Reit , which has retail outlet malls in cities such as Chongqing and Kunming, fell by 2.9 per cent to S$42.7 million. Its DPU shrank by 5.1 per cent to 3.153 Singapore cents.
CapitaLand China Trust , whose properties include retail, business and logistics assets, saw its distributable income decline by 18.7 per cent to S$51.3 million. Its DPU fell 19.5 per cent to 3.01 Singapore cents.
Other Reits with exposure to China, such as Mapletree Logistics Trust (MLT), CapitaLand Ascott Trust , Mapletree Pan Asia Commercial Trust and OUE Reit , also reported lower distributions.
At MLT’s most recent financial results briefing, Jean Kam, the chief executive officer of the trust’s manager, attributed its performance partly to weakness in China.
Residential sector hardest hit
Across the various sectors, the residential sector seems the hardest hit, amid an oversupply of units and weak buying demand, said RHB Singapore’s vice-president for equity research, Vijay Natarajan.
There is also a huge oversupply in the office and logistics sectors, with market vacancy rates above 20 per cent, said Xavier Lee, an equity analyst from Morningstar Investment Adviser Singapore.
However, vacancy rates for China’s retail malls are “slightly better” at under 10 per cent, he noted.
Negative rental reversions to continue
Lee expects rental reversions to continue being in negative territory for S-Reits’ China portfolios, as they will be focused on maintaining occupancies.
However, the retail sector in China has been an exception, with rental reversions starting to turn positive, said Natarajan. He pointed out that outlet malls, which attract cost-conscious buyers, have also been doing well in China.
Darren Chan, a senior research analyst at Phillip Securities Research, expects asset devaluations in the low-single-digit percentages for properties in China, mainly due to weaker operating performance. He also predicts the DPU of S-Reits with China exposure will fall further this year and next.
But with operating conditions likely to improve by 2026, he believes S-Reits with China exposure will recover by then.
Fewer divestments and acquisitions
Market watchers said that S-Reits with assets in China are unlikely to make major divestments because it is doubtful they will get good prices for their assets in the current economic climate.
Nevertheless, Natarajan of RHB said that Reits could possibly divest smaller assets that are in attractive locations or that can offer a change in use.
One such example is CapitaLand Investment’s divestment of a 95 per cent stake in Capital Square Beijing, a Grade-A office building, to AIA Life Insurance in January 2024.
Although Morningstar’s Lee does not expect S-Reits to “expand aggressively” in China in light of the challenging market conditions, RHB’s Natarajan thinks that S-Reits with ample debt headroom and a good sponsor pipeline for navigating the current market could make opportunistic acquisitions.
S-Reits with assets in China’s retail sector could also engage in acquisitions, given the nascent recovery in consumer spending and domestic spending-focused outlet malls, said Natarajan. (*see amendment note)
Outlook
Market analysts that The Business Times spoke to, however, do not see China’s real estate sector bottoming out soon. They estimate that it may take another one to three years to recover.
Carmen Lee, the head of OCBC Investment Research, said that there have been signs of recovery in China’s property transaction volumes since late June.
She noted that the seven-day rolling-average transaction volume year-on-year growth turned positive for the first time since the Chinese New Year in February, raising hopes that property easing measures by the Chinese government are starting to bear fruit.
“However, sentiment may take a while to improve,” she added.
Natarajan of RHB said that the China market is currently undergoing a major shift with state-led transformation of investments in sectors such as renewables (solar), electric vehicles, high-tech automation, and artificial intelligence-related sectors.
“Real-estate assets that support or align with these sectors could also benefit from this ongoing transformation,” he said.
Although the outlook for S-Reits remains promising with potential interest rate cuts on the horizon, Chan of Phillip Securities cautioned that S-Reits with exposure to China properties are likely to keep experiencing weakness in operating performance. This will affect their net property income.
Said Lee of OCBC: “We continue to recommend investors to stick with quality S-Reits backed by strong sponsors, that are in healthy financial positions with room for capital recycling, and have at least some Singapore asset exposure.”
Amendment note: An earlier version of this story incorrectly attributed the comment to Xavier Lee from Morningstar Investment Adviser Singapore, instead of Vijay Natarajan from RHB Singapore.






