

CICT enters Australia market with acquisition of 2 office buildings for A$330.7m
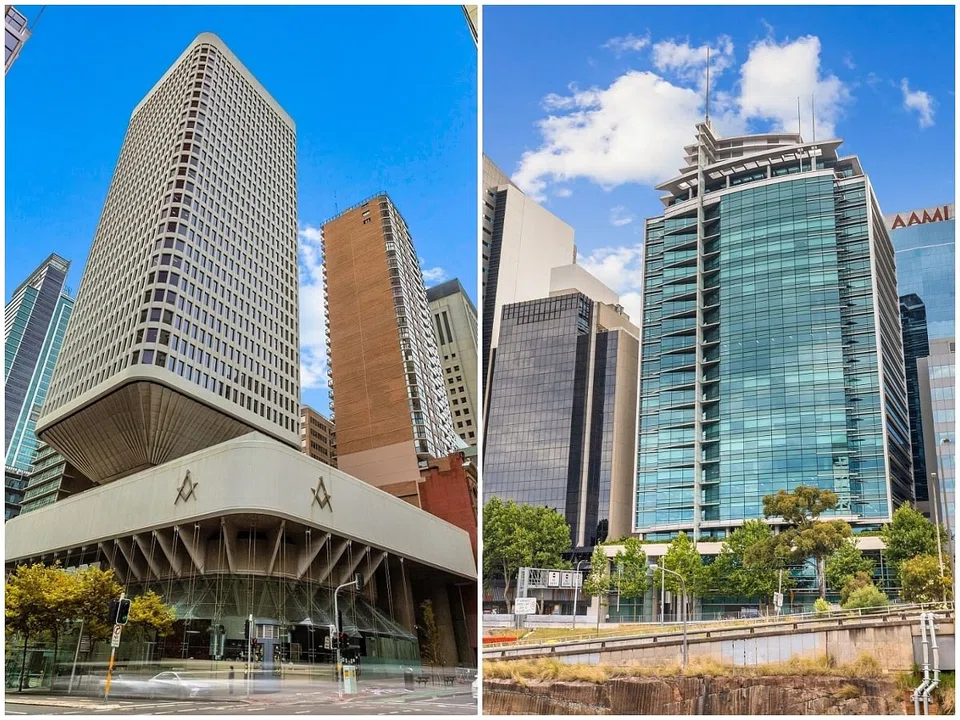
CAPITALAND Integrated Commercial Trust's (CICT) C38U indirectly wholly-owned subsidiary has entered into a unit sale agreement to acquire 2 Grade A office buildings in Sydney, Australia for A$330.7 million (S$330.7 million).
This would mark CICT's first inroad into Australia, its second overseas developed market after Germany, the real estate investment trust's (Reit) manager said in a bourse filing on Friday (Dec 3).
Tony Tan, the chief executive officer of the manager, said in a briefing on Friday (Dec 3) that the acquisition should not be looked at "in isolation".
"We are going through a journey to slowly recalibrate our portfolio," Tan said. "We want to have a portfolio that eventually will have heavy concentration in Singapore and not more than 20 per cent outside of Singapore. That's the big picture."
Tan added that this geographical diversity is to ensure that CICT's income stream will not be materially disrupted by "any kind of action in any of the assets".
Post-acquisition, CICT's overall portfolio property value will increase by 3 per cent to S$22.4 billion. Some 93 per cent of the enlarged portfolio by property value will be based in Singapore, with 4 per cent in Germany and 3 per cent in Australia.
"Once you're in the market, you actually open yourself up to more possibilities," Tan said. "This is just an entry point (into the Austalian market). Surely I think from now onwards, we probably can hear more market opportunities that will surface to us."
The estimated aggregate purchase consideration is based on the adjusted net asset value of the trusts that hold 66 Goulburn Street and 100 Arthur Street, taking into account the aggregate agreed property value of A$672.0 million. The agreed property value was negotiated on a willing-buyer-willing-seller basis, in line with 2 independent valuations commissioned separately by the trustee and manager of CICT.
The purchase consideration also takes into account other adjustments such as tenant incentives, other assets, and the total amount of liabilities of the 2 trusts, including external bank loans.
CICT's total acquisition outlay is about A$381 million, subject to completion adjustments. The acquisition is expected to be completed in Q1 2022.
Assuming the transaction was completed on Jan 1, 2021, the distribution per unit (DPU) after the acquisition would be 10.54 Singapore cents, from 10.23 cents, according to pro forma estimates. This translates to pro forma DPU accretion of 3.1 per cent.
The 2 buildings are located in Sydney's central business district within easy access of public transport and amenities.
The first property, 66 Goulburn Street, is a 24-storey Grade A office building with ancillary retail space and a basement car park.
It is a leasehold property with approximately 95 years remaining until Aug 16, 2116, and has a total net lettable area of 22,887 square metres (sqm) - comprising 22,630 sqm of office space and 257 sqm of retail space.
The property has a committed occupancy rate of 95.3 per cent and 25 tenants as at Sep 30, with a weighted average lease expiry (WALE) of 2.7 years, based on committed gross rental income as at Sep 30.
The second property, 100 Arthur Street, is a 23-storey freehold Grade A office tower with ancillary retail space. It has a total net lettable area of 27,082 sqm.
The property has a committed occupancy rate of 62.3 per cent and 16 tenants as at Sep 30 with a WALE of 4 years, based on committed gross rental income as at Sep 30.
The vendor, Acacia Commercial Investment Trust, will provide a rental guarantee of A$7 million for 100 Arthur Street as leasing efforts for the property are being ramped up.
The rental guarantee amount was arrived at based on market rent for vacancy at the Arthur Street property as at completion of the transaction, and assumes that the property's vacancy will be filled over a period of 12 months after the acquisition is complete, or when the sum is fully utilised.
The acquisition is expected to be partially funded with Australian dollar denominated bank loans for natural hedge. The net distributions from the 2 trusts holding the assets are also expected to be hedged, said the Reit manager.
After the acquisition, CICT's aggregate leverage is expected to be about 41 per cent, based on pro forma estimates.
"At this level, I don't think we are uncomfortable. It is a manageable level," Tan said.
"Bear in mind that the leverage is also a function of your denominator - your asset value base," he said. "We just have to do our job, make sure that we work the asset hard, optimise it as much as possible (and) create value."
Tan added the acquisition enables CICT to recycle capital from the divestment of its 50 per cent interest in One George Street, at an exit yield of 3.17 per cent per annum, into 2 higher-yielding office assets at a combined implied net property income yield of 5.2 per cent per annum.
Teo Swee Lian, chairman of the manager, said it is an opportune time for CICT to enter Australia given its "attractive office market underpinned by healthy economic fundamentals in the medium to long term, and expected recovery as the country emerges from Covid-19 restrictions".
She noted that Sydney is witnessing major development and rejuvenation initiatives in line with its government-backed ambition to become a leading innovation and technology hub in the region.
"The acquisition will allow CICT to gain a foothold in Australia, one of Asia Pacific's largest developed markets, and opens CICT to more opportunities to drive growth."
Units of CICT closed S$0.03 or 1.4 per cent lower at S$2.07 on Thursday.
TRENDING NOW

Fed hike throws Singapore banks a margin lifeline; UOB most likely to feel impact

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Real-estate veteran Desmond Sim quits from CEO roles at Realion, ETC

Chagee, Mixue and Luckin won the market. Sustaining their edge is the harder part

