CICT’s H1 DPU up 0.8% on post-pandemic tailwinds, acquisitions
CAPITALAND Integrated Commercial Trust (CICT) on Thursday (Jul 28) posted a 0.8 per cent increase in distribution per unit (DPU) to S$0.0522 for the first half ended June.
Distributable income rose 3.4 per cent to S$347.3 million for the period, from S$335.9 million a year ago, amid an income boost from Singapore’s reopening and the trust’s portfolio reconstitution efforts.
Net property income for the period was up 6.2 per cent to S$501.6 million, driven by CICT’s acquisition of a 70 per cent interest in the CapitaSky development and 3 Australian assets, as well as higher rental income. This was partly dampened by its divestment of the JCube mall, as well as a 7.2 per cent rise in property operating expenses to S$186 million.
The trust’s aggregate leverage was higher at 40.6 per cent as of end-June, compared to 37.2 per cent as of end-2021, due to the acquisitions. Its interest cover remained unchanged at 4.1 times. Some 81 per cent of its total borrowings were on fixed rates, with an average term to maturity of 4.4 years.
The average cost of debt is 2.4 per cent per annum.
Meanwhile, committed portfolio occupancy stood at 93.8 per cent as of end-June, with about 1.7 million square feet (sq ft) of new leases and renewals in H1. This comprises 600,000 sq ft of retail space and 1.1 million sq ft of office space. Notable tenants include Lululemon at Raffles City Singapore and Rakuten Asia at CapitaGreen.
“We continue to see CICT’s portfolio recovery, in line with the reopening of Singapore’s borders and easing of Covid-19 community measures. Riding on the positive momentum, CICT’s operating metrics, including tenant sales, shopper traffic, atrium space take-up and return of office community have recorded improvements,” said Tony Tan, chief executive of the trust manager.
Tan anticipates higher occupancy levels for the hotels at Raffles City Singapore and the serviced residence at CapitaSpring. CapitaSky and the Australian assets are also expected to lift third-quarter portfolio performance. Over in Australia, there is a “flight to quality”, which resulted in increases in face rents in core location buildings, the trust noted in its earnings report.
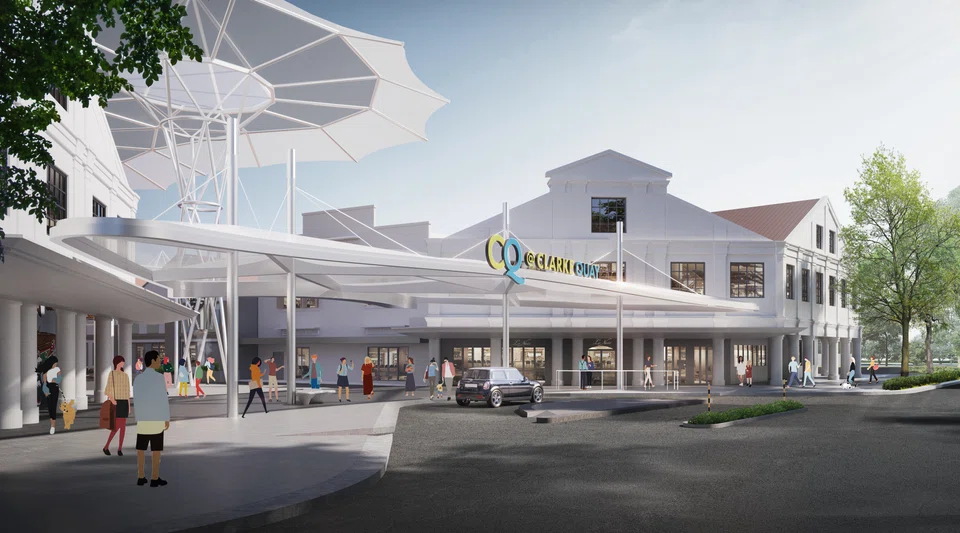
CICT will also be refreshing its malls, with over 50 new stores in Raffles City Singapore following its asset enhancement initiative (AEI) and 10 new brands at Bugis Junction and Bugis+. As recently announced, it is also embarking on a S$62 million AEI to transform CQ @ Clarke Quay.
CICT will continue to explore opportunities that fit its strategic investment criteria, Tan said. However, speaking at a briefing accompanying the result announcement, Tan played down rumours of CICT’s interest in the Mercatus portfolio.
Earlier media reports, citing people with knowledge of the matter, claimed that CICT is sounding out sources of financing for the prospective acquisition of NTUC Enterprise Co-operative’s S$4 billion portfolio of shopping malls in Singapore. “I don’t know why people speak on our behalf,” Tan said. “But if I said we’re not looking at it, nobody will believe it, right?”
“It’s in our own backyard, in a space we’re familiar with, so we’ll naturally be interested,” he noted. “I would say that there are some interesting elements within the portfolio… There are some pluses and minuses overall.” Tan added that CICT viewed the portfolio as it would any other potential assets.
Units of CICT were trading 0.5 per cent or S$0.01 lower at S$2.13 as at 1.30 pm on Thursday, following the result announcement.