

CICT’s H2 DPU up 2.7% to S$0.0536; market watchers mostly optimistic despite earnings miss
CAPITALAND Integrated Commercial Trust’s (CICT) distribution per unit (DPU) for the half year ended December 2022 rose 2.7 per cent year on year to S$0.0536, compared with S$0.0522 from FY2021.
The real estate investment trust’s (Reit) H2 FY2022 DPU was slightly lower than consensus estimates, as higher financing expenses offset gains from higher rental income and contributions from acquisitions.
“I know (DPU) is below market consensus, but I think we’ve done a little bit of things and hopefully going forward we’ll see some improvement from there,” said Tony Tan, chief executive of the Reit manager, at a briefing accompanying the results announcement on Wednesday (Feb 1).
“Bear in mind that we also have certain potential measures that will help improve the operating numbers going into 2023,” he added.
The way Citi analyst Brandon Lee sees it, CICT’s H2 results painted a positive picture on the ongoing recovery in Singapore’s retail sector.
Lee noted that CICT’s retail segment posted a fourth straight quarter of positive rent reversion amid improved occupancy rates. Tenants’ sales also remained above pre-Covid levels.
While the office segment appears to be slowing down in terms of rent reversions and leasing demand, Lee forecasts that rent reversions for CICT’s office portfolio will remain positive in FY2023 amid competitive rents.
“Despite the slight earnings miss today, we maintain our ‘buy’ rating in view of decent DPU growth – driven by increased income from CapitaSpring and 2 asset enhancement initiatives (AEIs) in Singapore – (as well as) continued recovery in the Singapore retail sector and potential redevelopment opportunities,” Lee said in a flash note.
For H2 FY2022, CICT posted a 14.4 per cent year-on-year increase in gross revenue to S$754.1 million, compared with S$659.4 million the previous year.
Net property income (NPI) for the second half rose 13.1 per cent year on year to S$541.7 million.
The topline increase was mainly driven by contributions from the trust’s recently acquired interests in CapitaSky in Singapore as well as assets in Australia, along with higher rental income from most of the Singapore assets.
This was however partially offset by higher operating expenses and the divestment of JCube, which was completed in March 2022.
CICT’s distributable income for H2 rose 4.8 per cent year on year to S$355.1 million from S$338.8 million the previous year. The record date for H2 DPU is Feb 9 and unitholders can expect to receive the payout on Mar 17.
For FY2022 ended Dec 31, DPU rose 1.7 per cent to S$0.1058 from S$0.104 in FY2021.
Gross revenue for the full year increased by 10.5 per cent year on year to S$1.44 billion compared with S$1.31 billion previously. NPI rose by 9.7 per cent year on year to S$1.04 billion from S$951.1 million in FY2021.
Tan noted that CICT’s NPI crossed the S$1 billion mark for the first time, calling it a “major milestone” for the Reit.
Based on CICT’s proportionate interests in its investment properties and joint ventures as at Dec 31, the trust’s aggregate portfolio property value increased by 8.9 per cent year on year to S$24.2 billion.
Committed portfolio occupancy for retail and office properties as well as integrated developments was 98.3 per cent, 94.4 per cent and 97.1 per cent respectively as at Dec 31, bringing the total committed portfolio occupancy to 95.8 per cent.
In FY2022, the trust signed approximately 2.5 million square feet (sq ft) of new leases and renewals, comprising around 1 million sq ft of retail space and 1.5 million sq ft of office space. The tenant retention rate for its retail properties and office properties in Singapore was 89.1 per cent and 80.9 per cent, respectively.
CICT’s manager expects Singapore’s commercial portfolio to benefit from continued consumption recovery, mainly due to an anticipated increase in tourist arrivals and a repositioned retail tenant trade mix.
Tan said the Reit manager will focus on riding the tailwinds of post-pandemic recovery to improve its operating metrics while navigating macroeconomic uncertainties to manage costs.
“There are some dark clouds out there. Everyone knows about it; there’s no surprise,” Tan said. “We have not seen a very widespread impact in Singapore yet, but because the environment is in the mood of rationalisation… in line with what some consultants are saying, we’ll probably see a little bit of slowdown in terms of rental growth going into 2023.”
“Nevertheless, there are other positive factors underpinning Singapore’s office market,” he added.
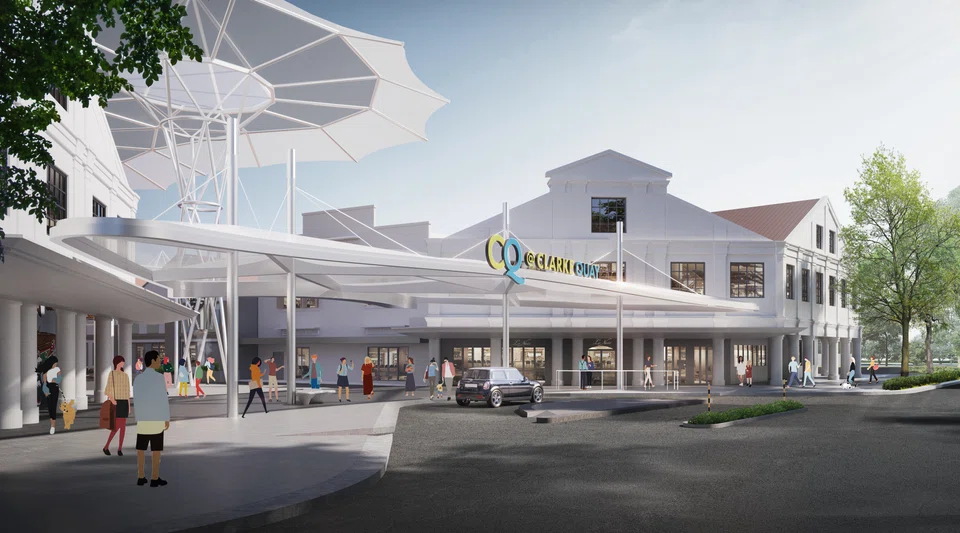
At the same time, Tan said the Reit is on track to complete its ongoing AEI at CQ @ Clarke Quay by this year. “We are already planning ahead… (and) there are a couple of projects we are studying,” he said.
At CICT’s closing price of S$2.14 on Tuesday, Lim & Tan Securities noted that the trust is capitalised at S$14.2 billion and is up 5 per cent this year to slightly beat Straits Times Index’s 3.5 per cent gain.
The brokerage on Wednesday morning noted that the consensus one-year target of S$2.23 implies a potential upside of just 4.2 per cent.
This, coupled with a “higher for longer” terminate rate outlook as well as fair valuations, has prompted Lim & Tan to downgrade its call on CICT to “hold”.
Meanwhile, Citi’s Lee noted that CICT is expected to see a “slight negative share price reaction” following the earnings miss.
Units of CICT are trading 1.4 per cent or S$0.03 lower at S$2.11 as at 3.49pm on Wednesday, following the results announcement.
TRENDING NOW

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Income Insurance appoints former Manulife Singapore top man as new CEO

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

