

CICT’s proposed acquisition of stake in Ion Orchard ‘opportune’; S-Reits expected to make more buys
Interest-rate cuts are imminent, and market appetite for equity fund-raising is improving, say analysts
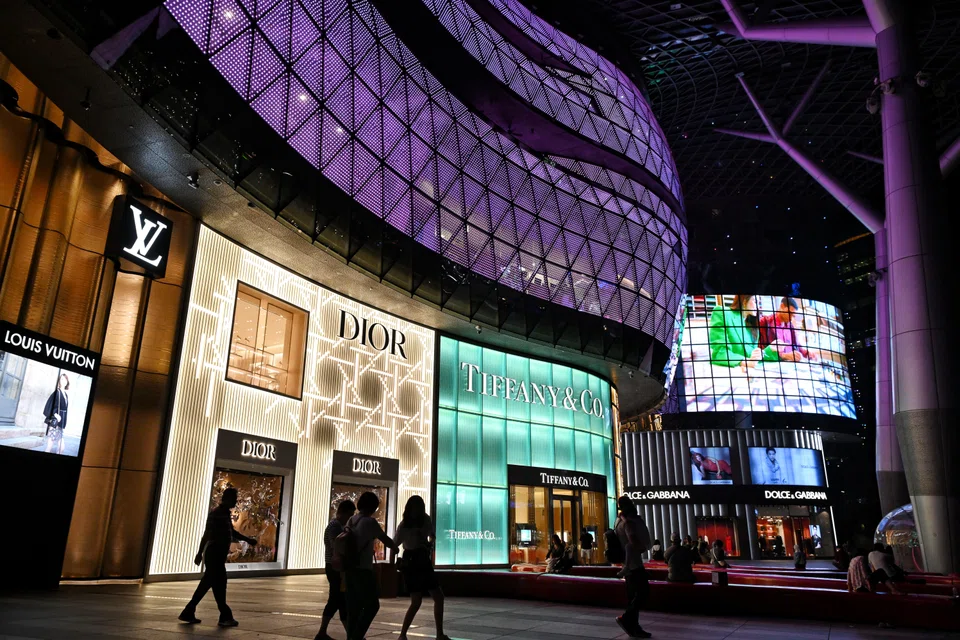
THE proposed acquisition of a 50 per cent stake in Ion Orchard, one of Singapore’s largest malls, by , comes at an “opportune time” – ahead of potential rate cuts and an improving market appetite for equity fund-raising.
Analysts say that the transaction, which amounts to S$1.85 billion based on 50 per cent of the agreed property value, also marks the start of more such transactions among Singapore-listed real estate investment trusts, or S-Reits.
“We expect more transactions, including both acquisitions and divestments, in the coming months as interest rates decline,” said Darren Chan, a senior research analyst at Phillip Securities Research.
Background
On Tuesday (Sep 3), CICT proposed to buy a 50 per cent interest in the mall and its connecting underpass, Ion Orchard Link, from its sponsor CapitaLand Investment (CLI).
The total outlay for the deal is estimated to be S$1.1 billion, after factoring in transaction-related expenses and adjustments for 50 per cent of a secured bank loan taken out by Ion Orchard.
CICT said that it intends to finance the transaction with net proceeds from a private placement and pro-rata, non-renounceable preferential offering to raise gross proceeds of at least S$1.1 billion.
Boost to CICT’s share price
Xavier Lee, an equity analyst at Morningstar, said Ion Orchard is “easily” one of the most expensive malls in Singapore by net lettable area. At S$3.7 billion, it is valued higher than other large malls such as VivoCity (S$3.4 billion) and Suntec City Mall (S$2.4 billion).
The deal comes at an “opportune time” with rate cuts on the horizon, said RHB analyst Vijay Natarajan in a research note on Wednesday. The US Federal Reserve is expected to cut interest rates later this month. “The Reit’s enhanced size, Singapore focus and improved liquidity post-acquisition will help to propel CICT’s share price further,” he added.
Morningstar’s Lee was also positive about the acquisition, noting that it would expose CICT to the luxury retail segment in Singapore. Moreover, Ion Orchard will benefit from the ongoing recovery in Singapore tourism. Its prime location means it will outperform its retail competitors on Orchard Road, he added.
The divestment, for CLI, would enable the group to unlock value from its Ion Orchard asset. CLI will continue earning recurring fee income and retain some exposure to the mall’s performance through its 24 per cent stake in CICT, said Lee. But he added that while an interest rate cut may push up CICT’s share price and enable the trust to raise equity funds, the lower interest rates may result in a lower capitalisation rate and higher valuation for Ion Orchard.
Gearing
The acquisition is expected to be immediately accretive to CICT’s distribution per unit (DPU), while keeping the trust’s leverage ratio relatively stable at 39.9 per cent, against the current 39.8 per cent.
Analysts said that the move by CICT to acquire Ion Orchard through equity fund-raising, rather than exclusively through a bank loan, ensures that the trust maintains a “healthy and stable” leverage ratio. Analysts are also confident that there would be appetite among investors for the private placement and preferential offering.
CICT closed its private placement at S$2.04 per new unit on Wednesday. It was 3.7 times subscribed, with “strong demand” from new and existing institutional, accredited and other investors, said CICT.
Phillip Securities’ Chan believes that market appetite for equity fund-raising is starting to improve, with the impending rate cuts and positive outlook for the Reits sector.
Added Lee of Morningstar: “We think CICT is currently undervalued and encourage existing unitholders to subscribe for the units under the preferential offering.”
Minimal change to DPU in near term
He said he retains a fair-value estimate of S$2.32 per unit for CICT, and expects minimum change in the DPU for 2024, as the acquisition is estimated to be completed in the fourth quarter of this year.
For the following financial year, Morningstar projects a 1 per cent accretion in DPU for CICT.
Lee noted that the trust is working to achieve tax transparency for Ion Orchard; Morningstar expects a further 0.9 per cent accretion to DPU when the tax transparency is approved by the authorities.
He does not expect a huge change in CLI’s earnings per share this year as Ion Orchard is only about 1.4 per cent of CLI’s current real estate assets under management. “We think the shares are attractive at the current price, and like the group for its fund-management business that enables it to retain long-term operational control of its assets while capturing recurring fee income,” he added.
More transactions by S-Reits to come
Analysts expect more transactions, including acquisitions and divestments, in the coming months as interest rates decline.
Natarajan of RHB said that there is room for CICT to make more divestments in the near term from its mature or non-core assets, such as Bukit Panjang Plaza, 21 Collyer Quay and Citadines Raffles Place. The proceeds from these divestments may be channelled to acquisitions and asset enhancements.
Lee of Morningstar said that such acquisitions and divestments among Reits will pick up on the back of interest rate cuts, although their frequency would depend on market opportunities.
Chan added that it would be easier for Reits to make acquisitions that are accretive with the impending interest rate cuts.
In a separate announcement on Wednesday, CLI announced that it aims to more than double its funds under management (FUM) in India in the next four years, as the global real asset manager remains optimistic on the country’s economic growth.
The increase would contribute to the group’s global target of achieving S$200 billion in FUM by 2028, said CLI. As at end-June, its India portfolio had S$7.4 billion in FUM.
Shares of CLI have climbed 3.4 per cent since the proposed deal was announced on Tuesday morning. Units of CICT fell 3.3 per cent on Wednesday following the lifting of its trading halt.
TRENDING NOW

‘My grandfather’s legacy’: Sherman Kwek lays out three-year plan for CDL to drive returns

CDL to hire dedicated CEO for fund management as it steps up push into private funds

Built on trust since 1964: How this award-winning finance company has grown with its SME customers

VSMC opens US$7.8 billion chip fab in Singapore, bets on ‘physical AI’ demand

