

CLCT posts 35.1% rise in H2 DPU to S$0.045 driven by pivot to 'new economy'
CAPITALAND China Trust (CLCT) AU8U was hit with 96 days of closures at 3 of its shopping malls - CapitaMall Xuefu and CapitaMall Aidemengdun in Harbin, and CapitaMall Xinnan in Chengdu - in the second half of FY2021 due to sporadic Covid-19 outbreaks in China.
But for the real estate investment trust (Reit), this brings to the fore the merits of its diversification strategy following the expansion of its investment mandate in September 2020.
"Despite 2021 still going through a volatile business environment and also China taking a zero Covid stance, management has stayed focused to achieve the strategies to build portfolio strength and income resilience across the market cycles," said chief executive officer of the manager Tan Tze Wooi at a briefing on Monday (Jan 31) following the Reit's FY2021 results announcement.
On the face of it, CLCT did remarkably well in FY2021. The Reit posted a distribution per unit (DPU) of 4.50 Singapore cents for its second half ended Dec 31, 2021, up 35.1 per cent from a DPU of 3.33 cents a year ago.
This comprised an advanced distribution of 2.70 cents per unit for the period Jul 1 to Oct 20, 2021 following a private placement on Oct 21, which was paid in November 2021, and a distribution of 1.80 cents for the period Oct 21 to Dec 31, 2021, its manager said in a press statement.
Gross revenue was up 84.5 per cent to S$201.1 million for H2 2021, from S$109 million a year ago.
Net property income (NPI) grew 86.1 per cent on the year to S$130.1 million for the half year, from S$69.9 million, mainly due to CLCT's new acquisitions.
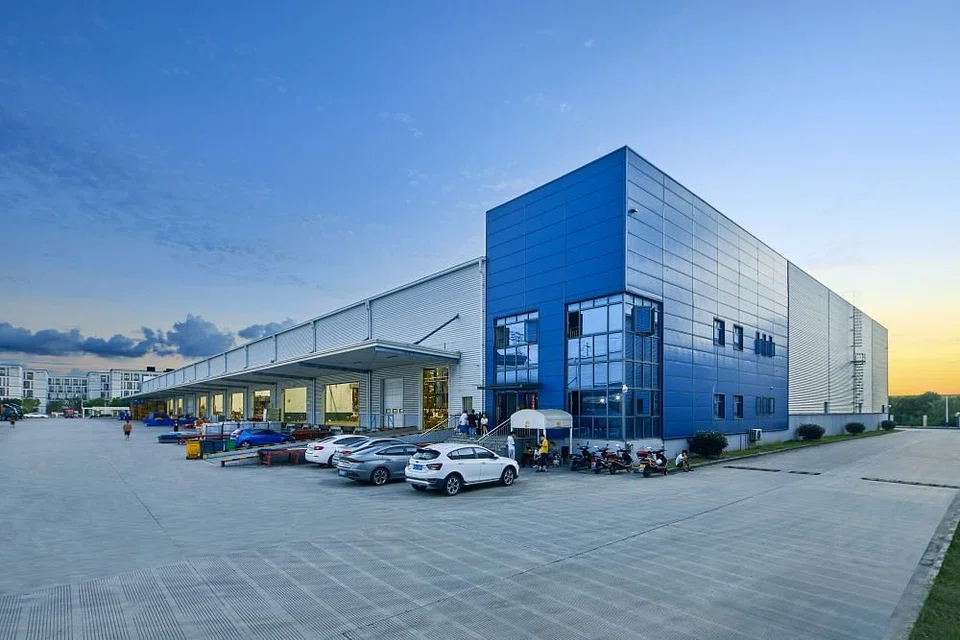
The improvements, however, were largely driven by contributions from its recently acquired 4 logistics assets in Shanghai, Kunshan, Wuhan and Chengdu, as well as 5 business parks - Ascendas Xinsu Portfolio, Ascendas Innovation Towers, Ascendas Innovation Hub, and Singapore-Hangzhou Science & Technology Park Phase I and Phase II.
Total distributable income for the second half was S$71.4 million, up 67.4 per cent from S$42.7 million in H2 2020.
For the full year ended Dec 31, 2021, the Reit posted a DPU of 8.73 Singapore cents on an enlarged unit base, versus 6.35 cents in the year before. Total distributable income was 70 per cent higher at S$135.5 million, while gross revenue was 79.5 per cent higher at S$378 million.
Full-year NPI was 85.2 per cent higher at S$250.4 million - its highest annual NPI since listing. Besides its new acquisitions, this rise in NPI was attributable to a 100 per cent contribution from Rock Square, the first full-year contribution from CapitaMall Nuohemule which officially opened in December 2020, and lower rental relief provided.
Noticeably, CLCT has seen differing fortunes for its retail assets compared with the new economy assets.
While the Reit manager said shopper traffic and tenant sales have improved 9.3 per cent and 16.1 per cent, respectively, year-on-year in FY2021, rental reversions remain weak in the retail space.
CLCT clocked negative retail rental reversion of 3.4 per cent for FY2021. In contrast, business park rental reversion saw a positive 7 per cent growth, while logistics park rental reversion was up 2.7 per cent.
"Given what we see happening across China, it's a very tightened phase of Covid containment strategy right now. So in terms of consumer spending, the confidence level is quite susceptible to how things are being contained and how the Covid-19 situation is being controlled," Tan said.
Meanwhile, he said the Reit's business parks are well-positioned to benefit from the central government's vision for a more innovative and technology driven economy while the logistics parks are expected to continue to ride a fundamental growth in e-commerce, third party logistics and manufacturing sectors.
Tan said CLCT will look to continue in FY2022 to divest mature, non-core retail assets as it recontitutes its portfolio.
As at Dec 31, 2021, retail assets accounted for 78.1 per cent of CLCT's assets under management, with business parks at 14.6 per cent and logistics parks at 7.3 per cent.
The Reit had earlier unveiled a 5-year plan to achieve a portfolio mix of 40 per cent in commercial and integrated developments, 30 per cent in retail properties and 30 per cent in new economy assets - including business parks, logistics and data centres - by 2026.
As at Dec 31, CLCT owns and invests in a portfolio of 11 retail malls, 5 business parks and 4 logistics parks located in 12 cities in China. This brings its total portfolio valuation to 24.7 billion yuan (S$5.3 billion), from 18.1 billion yuan in end-2020.
Its gearing stood at 37.7 per cent with an average term to maturity of 3.4 years as at Dec 31.
On the retail front, CLCT registered an improved portfolio occupancy of 96.3 per cent for its shopping malls. This is a result of its continual efforts to "optimise tenant mix and redefine traditional retail spaces to create meaningful experiences for shoppers", its manager said.
For its new economy assets, CLCT registered a portfolio occupancy of 96.2 per cent for its business park properties, and 97.4 per cent for its logistics properties as at Dec 31, 2021. As at Dec 31, weighted average lease expiry for its retail portfolio stood at 2.4 years by gross rental income and 3.8 years by net lettable area.
Looking ahead, CLCT will continue to adopt an "active and flexible" approach for its retail segment, with a focus on offering lifestyle essentials and necessities to densely populated catchments, according to its manager.
Meanwhile, it expects "steady" leasing demand to continue for the Reit's business parks, and underlying growth for its logistics parks buoyed by demand from e-commerce, third party logistics and manufacturers from Eastern and Western China.
Soh Kim Soon, chairman of CLCT's manager, noted that the Reit has "enhanced" the overall quality of its portfolio over the last 2 years, with the addition of new economy assets and a reconstitution of its portfolio in line with China's focus on domestic consumption and innovation-driven growth.
In addition to entering China's logistics market with its acquisition of 4 logistics properties, CLCT sold 2 mature retail assets to unlock 918 million yuan of capital for redeployment into higher-yielding opportunities.
"The transformed CLCT is now better positioned to capture opportunities in China's future economy across multiple sectors and through market cycles," Soh said.
CLCT will pay a distribution of 1.80 cents per unit for the Oct 21 to Dec 31, 2021 period come Mar 7, 2022, after the record date of Feb 10.
Units of CLCT closed at S$1.18, up S$0.04 or 3.5 per cent, on Monday after the results release.
READ MORE:
- CapitaLand China Trust's 9M NPI up 81.1% on retail and business park assets
- CLCT prices private placement at bottom end of price range, exercises upsize option
- CLCT to raise S$120m to fund S$297.7m acquisition of 4 China logistics assets






