

DFI shrinking Giant’s footprint to focus on Cold Storage amid growing competition
Analysts say DFI’s focus on multi-format retailing continues to keep the counter attractive
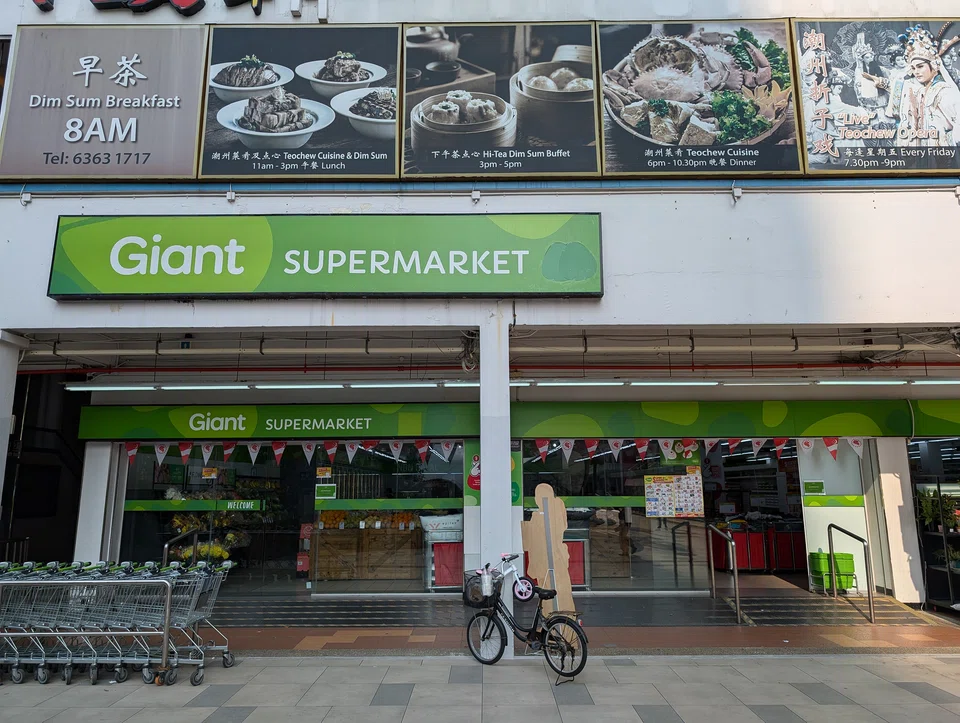
SUPERMARKET chain Giant has recently shuttered several outlets here. But market watchers believe there is little cause for concern, as it is part of DFI Retail Group ’s right-sizing approach as it turns towards ready-to-eat and fresh produce in its other grocery brands Cold Storage and CS Fresh.
Despite the closures, analysts say DFI’s focus on multi-format retailing, with health and beauty and convenience as key segments, continues to keep the counter attractive.
DBS analysts Andy Sim and Chee Zheng Feng said DFI appears to be focusing on the Cold Storage and CS Fresh branding, as well as fresh, ready-to-eat options – bakeries, salad bars and takeaway Japanese sushi – to supplement its fresh products and grocery repertoire.
DFI has also been differentiating itself from its peers through its Meadow house brand and Yuu rewards platform, they added.
Meanwhile, management had previously guided that the Giant store closures “are part of its right-sizing strategy to improve profitability by shutting down unprofitable stores”, they noted.
“We understand and believe that there are no specific consumer habit changes that led to the shutdown,” they added.
Giant recently announced the closure of its supermarket on Toa Payoh Lorong 4. The closure on Sep 15 is its ninth since February this year, after the shutters came down on its hypermart in Sembawang, three supermarkets and four smaller express stores.
Following the closure, Giant will still have 45 outlets here.
Jayden Vantarakis, Macquarie Capital’s head of Asean and Singapore research, noted that DFI has shown a “willingness to downsize, divest and focus on improving shareholder returns”.
He pointed out that the company has divested or closed some of its international Giant operations. In 2021, its subsidiary Hero Supermarket closed all its Giant supermarkets in Indonesia. It also sold its Malaysian Giant operations to retail group Macrovalue in 2023.
He noted that consumers have been looking for more “value options” and that Giant has faced considerable competition from FairPrice, a cooperative of the National Trades Union Congress, and Singapore-listed peer Sheng Siong Group .
Stock analysis
Since the beginning of the year, shares in DFI have delivered a total return of minus 21.4 per cent while shares in Sheng Siong have returned minus 2.3 per cent.
Over the same period, the benchmark Straits Times Index’s total return was 15.3 per cent.
DBS’ Sim and Chee said DFI’s underperformance compared to the STI is likely due to investor wariness towards companies with China exposure – North Asia accounts for 73 per cent of DFI’s revenue.
DFI Retail Group posted an underlying profit of US$75.6 million for the six months to end-June, more than doubled from US$33.3 million for the same period last year.
Its total H1 profit, which includes non-trading items, stood at US$95.1 million, up from US$8.2 million the year prior. This came even as its half-year revenue fell 4 per cent to US$4.4 billion.
Within its reportable segments, food revenue – which includes its grocery retail business – dipped 6.5 per cent to US$1.6 billion, from US$1.7 billion.
The DBS analysts noted that its food revenue was slightly lower than expected because of the sale of Giant Malaysia and store closures in Singapore. They adjusted their full-year revenue forecast downwards to US$3.1 billion, from US$3.3 billion.
The analysts said DFI’s store network rationalisation in Singapore, and its continued market share gain in Hong Kong, had resulted in its operating margin expanding to 1.6 per cent in H1 FY2024, compared to 0.8 per cent in H1 FY2023.
In comparison, Sheng Siong posted a H1 profit of S$69.9 million, up 7 per cent from S$65.4 million in the year-ago period. Revenue also increased by 3.4 per cent to S$714.2 million, from S$690.5 million.
The group only operates in the supermarket segment, with the majority of its stores in Singapore.
Macquarie Capital’s Vantarakis said: “Sheng Siong is more profitable, but it is heavily Singapore-focused and only has one format. DFI is a multi-format retailer, and its most attractive growth avenues are health and beauty (beauty chain Mannings and pharmacy Guardian) and convenience (the 7-Eleven franchise).”
Despite its focus on new avenues, he nonetheless expects DFI “to retain a grocery presence in Hong Kong and Singapore, where it is a top three player and enjoys economies of scale”.
Shares of DFI fell 1.1 per cent or US$0.02 to US$1.81 on Friday, while Sheng Siong shares closed flat at S$1.50.






