

Glove manufacturers, medical suppliers surf new Covid-19 wave
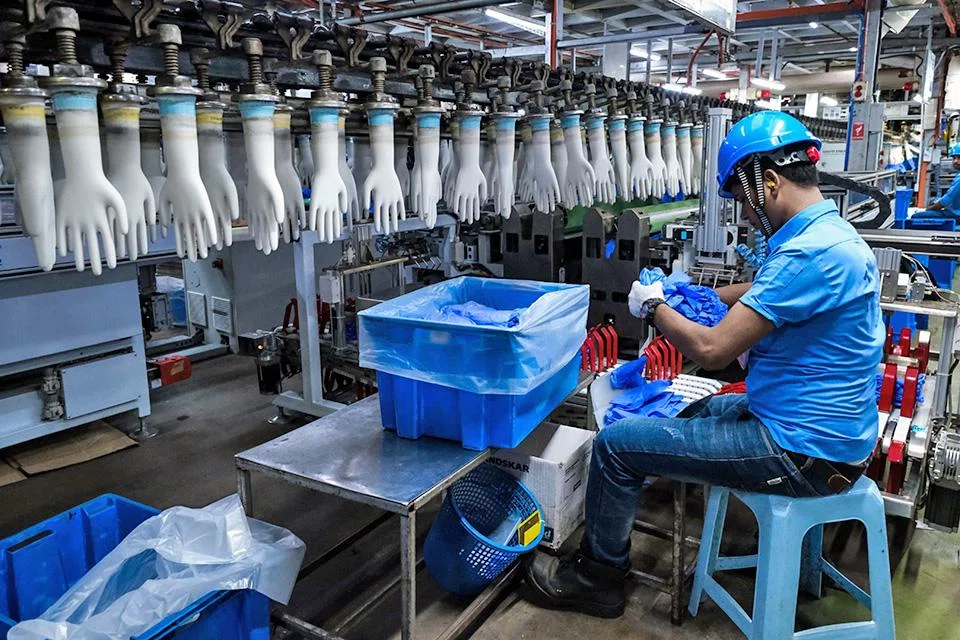
SHARES of Singapore’s listed glove manufacturers and other medical equipment suppliers are up as much as 20 per cent year to date on the back of a Covid-19 wave, although analysts said the price spike is unlikely to be sustained in the longer term.
Among the most traded healthcare-related stocks on the Singapore Exchange (SGX) are Malaysia-based glove manufacturers Top Glove Corporation and Riverstone Holdings as well as personal protective equipment supplier and distributor Medtecs International Holdings .
The trio have risen sharply in the past week. From Dec 13 to 19, Top Glove is up 21.7 per cent and Riverstone has climbed 18.7 per cent. Medtecs has jumped by 48.1 per cent.
Other glove makers, such as mainboard-listed Sri Trang Gloves (Thailand) and Catalist-listed UG Healthcare Corporation , are up 25 per cent and 130.8 per cent respectively, over the same period.
In comparison, the benchmark Straits Times Index has risen 0.5 per cent over the same period.
The outperformance of healthcare-related stocks comes as the Ministry of Health on Dec 15 announced that the estimated number of Covid-19 cases spiked to 56,043 for the week of Dec 3 to 9, up 75 per cent from 32,035 cases in the previous week.
In a statement, the ministry strongly encouraged the public to wear masks in crowded areas or when interacting with vulnerable persons.
Market watchers said investors could be banking on the Covid-19 resurgence to push up the earnings of these medical equipment manufacturers and suppliers.
Glove makers had been a key beneficiary of the Covid-19 pandemic. The counters had soared to record highs in tandem with their earnings, as medical institutions stocked up on gloves.
As the pandemic waned, however, their earnings retreated on the back of fewer orders, as customers sat on ample inventory.
Top Glove, the world’s largest maker of rubber gloves, reversed into the red in its latest financial year, with a net loss of RM$926.6 million (S$263 million) versus net profit of RM225.6 million in FY2022.
Catalist-listed Medtecs widened its losses for its half-year ended June to US$5.4 million from US$3.7 million in H1 FY2022.
Riverstone remained in the black, but its third-quarter profit slid in its latest financial update to RM59.3 million from RM63.5 million.
Surge expected to be “short-lived”
Analysts believe the current share price correction is unlikely to be prolonged, as earnings are not likely to stay elevated in the longer term.
Maybank Securities analyst Jarick Seet said: “There might be a temporary surge in sales, but definitely less than (sales) during Covid-19.”
A Covid-driven earnings surge had already shown itself to be unsustainable after the pandemic ended, he added.
Maybank has, nevertheless, turned “positive” on Malaysia’s glove sector. In a December report, it noted improving sales volumes and stabilising raw prices.
“While sales volume remains volatile with a shorter order lead time, as buyers are in no rush to lock in a contract due to excess supply in the glove market, sales volume has improved significantly quarter on quarter among the Malaysian glove makers,” said Maybank Securities analyst Wong Wei Sum.
AmInvestment Bank also upgraded the sector to “neutral” from “underweight”, reflecting recent upgrades for Bursa Malaysia-listed glovemakers Hartalega Holdings and Kossan Rubber Industries.
Analyst Chee Kok Siang sees a “high possibility of demand recovery” among Malaysian glove makers.
“Considering the standard three-year expiration period for medical rubber gloves, inventories in western countries may be depleted between the second to third quarter of 2024,” he said.
“We anticipate that distributors should restock by the first quarter of 2024, prior to the full depletion of inventories.”
No glove lost
Analysts are more cautious on Top Glove. After the glove manufacturer’s full-year results release in October, UOB Kay Hian analyst Jack Goh trimmed his estimates on Top Glove’s FY2024 and FY2025 earnings due to lower utilisation rate and average selling price forecast.
He anticipates a milder-than-expected recovery pace, with key risks including softer volume sales and inability to pass costs down to consumers.
According to Citi analyst Fais Megat, the company’s quarter-on-quarter improvement was “encouraging, but not unexpected”. He noted that Top Glove’s Q4 volumes were down 10 per cent on a quarterly basis, as the group prioritised pricing and margins over volume.
“A sustained recovery in volume and signs of better pricing power are key for us to revisit our view on the stock and the sector as a whole,” he said. Top Glove will announce its fiscal first-quarter results on Dec 20.
On Sri Trang Gloves, Megat noted the glove manufacturer’s recent earnings were unexciting, which would likely cap any significant share-price upsides, despite its “undemanding valuations”.
CGS-CIMB upgraded Riverstone to “add” after its third-quarter results, as the Malaysia-based glove maker managed to lift its segment average selling price and gross processing margin by focusing on higher-margin customised glove offerings.
TRENDING NOW

‘My grandfather’s legacy’: Sherman Kwek lays out three-year plan for CDL to drive returns

CDL to hire dedicated CEO for fund management as it steps up push into private funds

Built on trust since 1964: How this award-winning finance company has grown with its SME customers

VSMC opens US$7.8 billion chip fab in Singapore, bets on ‘physical AI’ demand

