

In corporate governance, good form is predicated on better substance
The recent fracas at CDL is both ironic and unfortunate; lessons should be learnt all round
[SINGAPORE] Many moons ago as a young executive, I was fortunate to be schooled by a titan – JY Pillay. One of the Last Fools, or Eight Immortals of the Lee Kuan Yew era of public service mandarins, he went on to make his mark at Singapore Airlines, DBS and Singapore Exchange (SGX), among others.
As a non-executive chairman, he was kind enough to host me for lunch every so often in his office, where I tried to soak in his wisdom and take instructions, typically when dessert was served.
On one memorable occasion, as I tried to convince him of grand strategies and various plans, he remarked: “Strategies or grand tactics one must have. It is expected that management will have the expertise, detailed plans for efficient and effective execution. However, do you have the right people? If you get the people right, success follows – or not, if not.”
Good intentions
He was a chairman par excellence, one that some of us can only dream of emulating, as we trail far behind in the paths he has trod.
And so it is with corporate governance, both the code and the Act, or listing rules. They are designed to help guide and ensure that de minimis standards objectively can be set and over time, raised with good intentions.
We dedicate resources to dot the i’s and cross the t’s, and build up mechanisms of assurances around because we must. There is a need for transparency and accountability especially in public companies.
However, ever so often we get caught up in the form, and sometimes miss the intent and substance once things are codified. We must not forget.
Take as example the diversity, equity and inclusion programmes that US President Donald Trump rails against. It is with some relief, expressed only in private, that US chief executive officers roll back some of the policies to get with the White House zeitgeist today. The risk of a CEO being cancelled by being out of step, having misspoke or inadvertently tripping up over the far corners of woke, has abated somewhat.
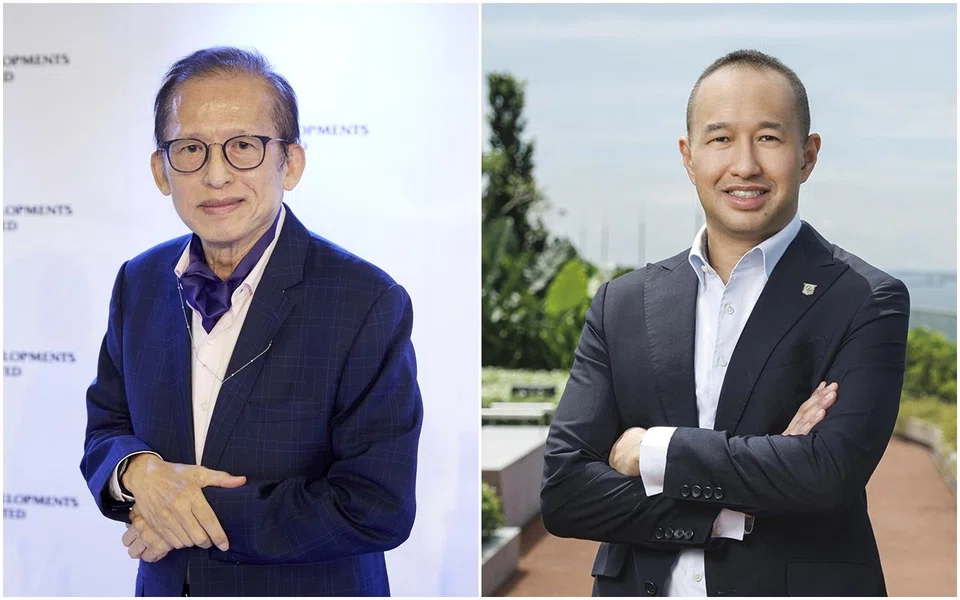
More recently, a lot of commentary was generated around the unfortunate lawsuits between City Developments Ltd (CDL) executive chairman Kwek Leng Beng, group CEO Sherman Kwek, two directors and the majority of its board.
We are all delighted that cooler heads have prevailed and the parties have since stood down their lawyers, and declared they will collectively work in the interests of the company and shareholders. (That is personally reassuring as I have to declare I am a shareholder and, during the skirmish, bought a little more for good order.)
Vagueness around corporate governance code
During the fracas, a lot was said about bypassing the nomination committee, creating a combined nomination committee and remuneration committee as well as alleged listing-rule breaches.
Expert commentators have pointed out the vagueness around the corporate governance code, even while others may be rightly convinced no laws were broken.
After all, the majority of the board voted to onboard two new directors, and the board in substance is where the approving or disapproving authority rests, irrespective of what the subcommittees may recommend or not.
It is also not uncommon to have combined nomination and remuneration committees – provided the work that is required is done.
To split them in order to follow a letter or guidance often is form over substance, where overlapping or even similar directors constitute these board committees, especially for smaller listed companies. Substantial approving authority still resides with the board nonetheless.
More importantly, while many investors in Asia place their bets on family controlled companies often with the founder, or a next-generation family member as an executive chairman or the CEO, our rules require a majority of directors to be independent in order to ensure that governance safeguards are in place.
Merit or self-interest?
For years, corporate governance proponents have pointed out that this form does not always work in practice if the “independents” are stacked with friendly parties. They of course bring diverse skills to the table – as the codes and rules – or form – dictates or requires on paper.
It is impossible to ascertain whether often they agree with the executive chairman wholly on merit, or with various shades of potential self-interest.
There is thus an interesting observation about the CDL episode. Contrary to the initial outcry about “governance issues” based on press releases from the executive chairman and subsequently a director – Philip Yeo – who was first appointed to the board in 2009, I cannot recall, having been a market observer since the 90s, a single instance that a majority of directors took a position contrary to the executive chair in the interest of the company and shareholders that spilled into the public.
While this may happen in private, and minority dissent and votes do happen in all boardrooms, it typically results in the said directors standing down soon after. Whereupon the market and press speculate about cause, as in the case of CDL itself post the Sincere episode in 2020, after which director Kwek Leng Peck stepped down.
The aspersions cast on the majority of the board and its two new directors during this episode are ironic and unfortunate. There are lessons to be learnt all round, however.
It is not just that board tenure beyond a certain period per se is problematic for independence. A family member or friend, or simply a director choosing to take a position to go along with the chairman, can be newly onboarded, or be past the nine-year cap on independent-director tenure.
It is not the form per se, but substance by what each chooses to do, to discharge their board duties well.
Board renewal paramount
However, it may be fair to say that very long-serving directors may be more at risk of preconceived ideas or judgement, and less able to see round the corner, whatever their allegiance.
Board renewal is thus paramount. Not so frequently as to be disruptive and not effective, but something useful that listed companies should be considering, not only because of a nine-year rule.
In addition, this episode has shown the need for listed companies to step up and ensure effective communication and stakeholder management, especially during periods of public disputes among or between management and board.
The clear, transparent and timely communication from CDL’s board early on helped maintain trust with investors. This is evidenced by the minimal change to its trading price on resumption of trading after the cancellation of its results briefing, also helped by the resolution among its board members in less than two weeks.
The Monetary Authority of Singapore’s equities market review group has recently proposed a shift in regulatory approach towards more disclosure and less merit judgement on the part of the regulators, to give the market more free play. There may be more spelt-out forms, but it is imperative that all of us remember the substance and play our respective parts.
SGListCos supports these initiatives, and will continue to facilitate training for investor relations, communications, governance and best practice among our SGX-listed members, and believes that substance and valuations will prevail when we all play our part.
Chew Sutat is chairman of SGListCos, an association representing companies listed on the mainboard and Catalist of the Singapore Exchange. Chew retired in 2021 from SGX, where he was a senior managing director.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Can Mark Shaw bring Singapore back to Orchard Road and the movies?

Ex-Sembcorp Marine CEO Wong Weng Sun acquitted of charges in Brazil corruption case
‘Under human control’: Xi urges AI safeguards at White House summit as Trump resists curbs

