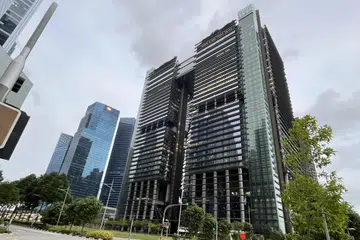
CRCT proposes to buy five business parks, remaining stake in mall for 4.95b yuan
Properties are in China's Tier 2 cities and they have an occupancy rate of more than 90 per cent
Vivienne Tay
Singapore
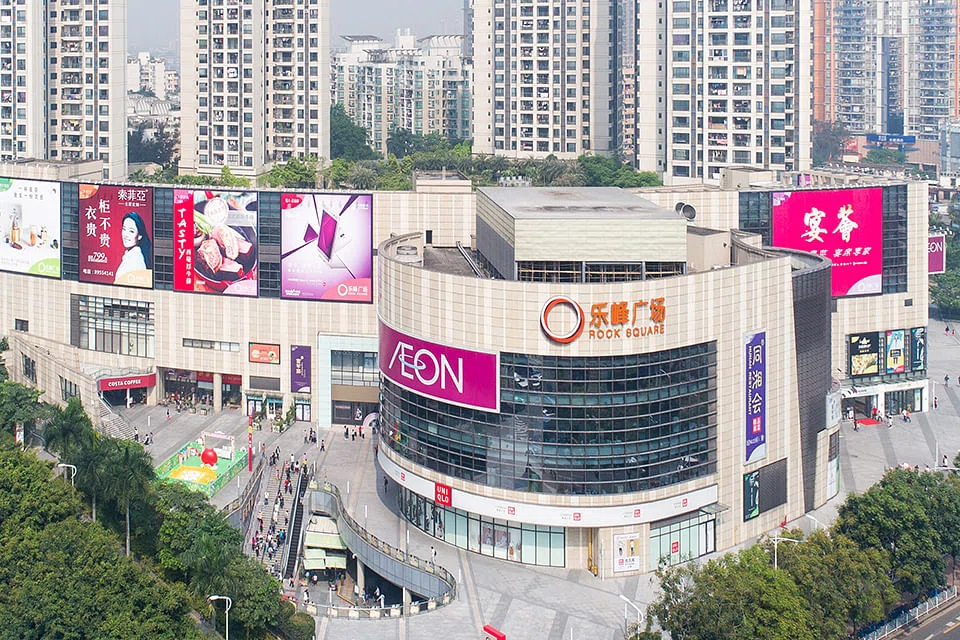
THE manager of CapitaLand Retail China Trust (CRCT) has proposed to buy interests in five business park properties and the balance 49 per cent interest in its Rock Square mall asset for an agreed property value of about 4.95 billion yuan (S$1.01 billion) from related parties.
The five business park properties are located in Suzhou, Xian and Hangzhou, while Rock Square is located in Guangzhou, the real estate investment trust's (Reit) manager said in a bourse filing on Friday.
Total acquisition cost is estimated at S$822.4 million, subject to post-completion adjustments, said the Reit's manager.
CRCT is looking to acquire a 51 per cent interest in the Ascendas Xinsu portfolio in Suzhou. In Xian, it is proposing to buy the entire stake in Ascendas Innovation Towers and an 80 per cent interest in Ascendas Innovation Hub.
In Hangzhou, CRCT has proposed to acquire 80 per cent interests in phases one and two of the Singapore-Hangzhou Science & Technology Park (SHSTP).
Speaking to the media and analysts at a briefing on Friday, Tan Tze Wooi, chief executive of the manager, said that business parks in China stand to benefit from preferential policy support anchored by national and local government initiatives.
A decentralisation trend among various enterprises towards China's Tier 2 cities - where the acquisition targets are located - will also support the "favourable outlook of business parks", Mr Tan said, adding that these assets are also supported by "excellent transport, infrastructure and connectivity".
On its Rock Square proposed investment, CRCT's manager said the mall has achieved double-digit positive rental reversions in 2018, 2019 and for the year to September 2020.
It continues to demonstrate resilience post Covid-19 lockdown, it added.
Having full ownership of Rock Square will allow CRCT to fully capture upside from asset enhancement initiatives (AEIs). Ongoing AEIs are expected to create more than 1,000 square metres of net lettable area over the next two to three years.
CRCT intends to finance the acquisition through an optimal mix of debt, equity and hybrid securities, which will result in distribution per unit accretion. The proposed acquisition is expected to be completed by Q1 2021.
Subject to unitholders' approval at an extraordinary general meeting to be convened at a later date, CRCT's enlarged portfolio will consist of 18 properties. Its gross floor area will increase by 76 per cent to about 1.8 million square metres.
Assets under management will increase by 28.5 per cent to S$4.5 billion, while net property income will grow substantially by 54.1 per cent on a pro forma H1 2020 basis, he added.
The business parks will contribute more than 40 per cent in gross floor area to CRCT's enlarged portfolio post-acquisition.
Relative to the overall business parks market - which has a vacancy of about 15 to 20 per cent - the properties that CRCT are acquiring have an occupancy rate of more than 90 per cent. Mr Tan said this demonstrates their strong position in the marketplace and ability to command demand.
While leasing activities, especially in the first half of the year, have slowed as a result of the Covid-19 pandemic, CRCT's manager is optimistic of a better operating environment going into 2021.
That being said, divestments can also be expected for some of the Reit's less competitive assets in its portfolio.
Wuhan's CapitaMall Minzhongleyuan could be a "potential candidate", said You Hong, head of investment and portfolio management of the manager.
In the long run, Mr Tan said CRCT is looking to position itself as a "well diversified China Reit play". This means moving away from being just a retail-centric Reit.
Business parks and industrial space - which are considered new economy sectors - are areas that the manager is interested to further look at in terms of opportunity, "both in-house and external".
DBS Group Research, in a note to clients dated Nov 6, said such acquisitions would "bring stability and 'future-proof'" CRCT's earnings profile. DBS has maintained its "buy" call on CRCT as well as its target price of S$1.55.
CRCT units closed down S$0.03 or 2.38 per cent at S$1.23 on Friday.