

Credit Bureau Asia aims for ‘multiplier effect’ with digital banks
Claudia Chong
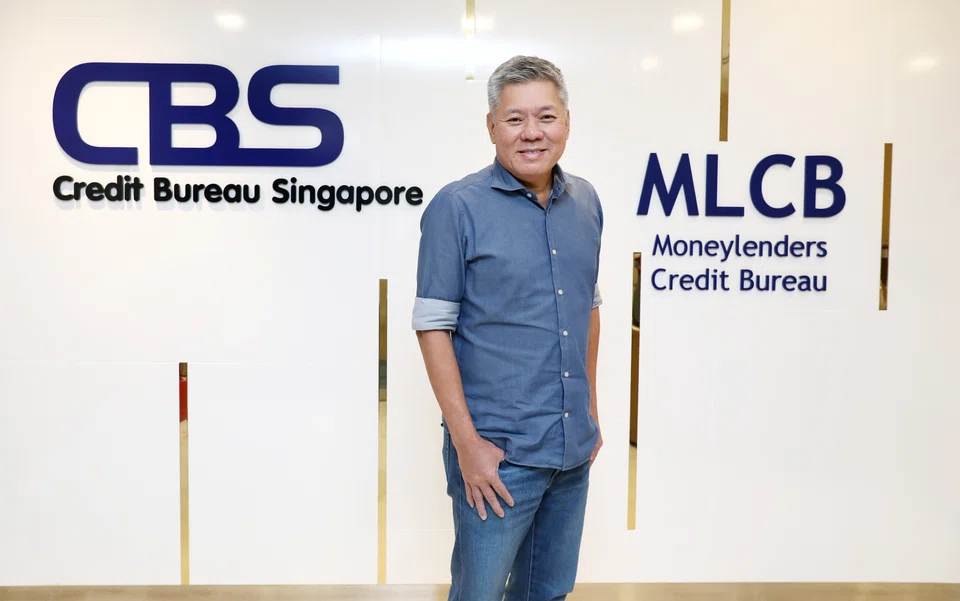
CREDIT Bureau Asia (CBA), which runs the largest consumer credit bureau in Singapore, is eager for the local digital banks to finally launch.
CBA’s growth is linked to the growth of its member network. The inclusion of a new financial institution in Credit Bureau (Singapore)’s (CBS) platform has a ripple effect, amplifying the data pool for all members while creating more revenue opportunities for the group.
CBS' fees are based on how many reports it generates for its customers (the banks), whether each report comes with a score, the size of the portfolio the customer is monitoring, and the number of triggers or alerts sent out.
When an individual signs up for a new credit card or loan with a digital bank, the bank uses CBS’ platform to generate a credit report.
But it is not only the digital banks that will generate these reports. If the consumer has existing relationships with other banks, CBS’ monitoring system alerts them to the consumer’s increased credit exposure. The banks might decide to review that customer’s status, prompting them to pull reports of their own.
Lenders may also place certain consumers within a portfolio with a higher frequency of reviews, due to higher credit exposures.
“It becomes a multiplier effect,” said CBA’s executive director, William Lim, in an interview with The Business Times.
There are 5 digital banks that can operate in Singapore. Sea’s Maribank, Grab and Singtel’s GXS, and Standard Chartered and the National Trades Union Congress (NTUC)’s Trust Bank are digital full banks. Ant Group’s ANext and Green Link Digital Bank operate under a digital wholesale bank licence.
One of the banks – Lim declined to say which – signed up as a customer in Q1 this year, and CBA has started recognising revenue from the deal. “They signed a volume purchase and bulk review agreement, so as to enjoy slightly better pricing. Typically, such contracts are for 2 or 3 years and may come with a fixed monthly spend for certain agreements,” Lim said.
CBS drives the lion’s share of CBA’s revenue. During the year ended Dec 31, 2021, the subsidiary accounted for about 43 per cent of CBA’s S$45.4 million topline. Group net profit was S$7.8 million, rising 14.6 per cent from a year ago.
CGS-CIMB analyst Andrea Choong said the ramp-up of digital banks in Singapore is key to progressive earnings accretion for CBA. “This will depend greatly on the type of products rolled out and the adoption of both DFBs (digital full banks) and DWBs (digital wholesale banks) by the marketplace,” she wrote in a Jun 12 report.
She added, however, that earnings visibility for the group is likely to emerge only in the medium term, once the banks firm up their growth strategies.
Resilient model
CBA has plans to deepen its regional presence, but rising interest rates could have an immediate impact on its business as consumers scale back on borrowing.
Lim said new credit card applications fell 30-40 per cent during the pandemic, as consumer sentiment took a hit. According to figures from the Monetary Authority of Singapore, credit card transactions dropped from S$67 billion in 2019 to S$56.7 billion in 2020.
Still, Lim believes the company will get through the downturn relatively unscathed. “New applications will get hit, but reviews will get a kick,” he said.
Lim expects portfolio monitoring frequency to increase and the number of reviews to jump as banks tighten their risk monitoring. He noted that the group’s revenue continued to grow even throughout the global financial crisis, the outbreak of Sars (severe acute respiratory syndrome) and the Covid-19 pandemic.
As at December 2021, CBA’s financial institution (FI) data business serves more than 200 FI members across Singapore, Cambodia and Myanmar, including banks, microfinance institutions, leasing companies and rural credit operators.
In Singapore and Malaysia, the group has joint ventures with American analytics company Dun & Bradstreet to provide a wide range of business information and risk management services under the non-FI data business.
Although CBA’s regional expansion is in its early stage, the company has a first-mover advantage. It operates the only credit bureaus in Cambodia and Myanmar. In FY2021, revenue from its joint venture Credit Bureau (Cambodia) grew 24.9 per cent to S$12.5 million.
CBA expects its bureau in Myanmar to begin generating revenue soon, following a prolonged delay indirectly caused by the political situation in the country. It now has 31 banks uploading data to its platform, up from 10 a year ago when the bureau was announced.
Lim said the company is evaluating acquisition opportunities within South-east Asia and North Asia, Japan, South Korea and certain parts of Australia and New Zealand. It will focus on complementary businesses instead of credit bureaus. As at Dec 31, 2021, CBA had cash and bank balances of S$53.5 million and no debt.
The company’s share price has fallen 2.94 per cent since it debuted on the Singapore Exchange in December 2020, to close at S$0.99 on Jul 29. That is still 6.5 per cent above its initial public offering price of S$0.93, and gives the counter a market capitalisation of S$227 million and a price-to-earnings ratio of 29.1 times.
TRENDING NOW
Stocks to watch: Clar, Seatrium, Sheng Siong, MPACT, NetLink NBN, Starhill Global Reit

Singapore government slaps loan curbs on individual private-hire car buyers

If Europe goes to war, the fallout will be felt in East Asia

DBS denies rumours of Indonesia unit merging with Bank Central Asia; analysts see sense in a deal

