

Daiwa House Logistics Trust to raise S$575.5m in IPO, selling units at S$0.80 each
DAIWA House Logistics Trust (DHLT) is rolling into the Singapore market as the first real estate investment trust (Reit) with significant exposure to logistics and industrial properties in Japan.
But for sponsor Daiwa House Industry Co (DHI), a property developer and real estate fund manager listed on the Tokyo Stock Exchange (TSE), DHLT represents its move to capture growth opportunities in the wider Asian market.
The Reit manager intends to raise gross proceeds of approximately S$575.5 million from its initial public offering (IPO) on the Singapore Exchange (SGX), including the issuance of the sponsor's subscription units, the cornerstone units as well as perpetual securities.
It also intends to draw down 35.6 billion yen (S$421.1 million) of loan facilities on the listing date.
Some S$840.5 million of the funds will go towards the purchase of the 14 properties in the IPO portfolio; the remainder will be used for issue expenses, other transaction costs and working capital, among other things.
According to the prospectus lodged with the Monetary Authority of Singapore on Friday (Nov 19), the Reit manager will offer over 244.4 million units at S$0.80 per unit for subscription as part of an offering which comprises a placement tranche of over 219.4 million units and a public offer of 25 million units to Singapore investors.
In addition, cornerstone investors have entered into separate subscription agreements at the same offer price for a total of nearly 336.1 million units. Among the cornerstone investors are Bangkok Life Assurance Public Co, asset manager DWS Investments Australia, Metro Holdings' wholly-owned unit, Metro ARC Investments and Kuang Ming Investments, an investment holding company privately owned by Philip Ng and family.
Separately, sponsor DHI has entered into a subscription agreement, under which it will subscribe for up to 94.5 million units at S$0.80 per unit, assuming that the over-allotment option is not exercised.
Based on the IPO price of S$0.80 and a total number of outstanding units at 675 million after completion of the offering, DHLT will have a theoretical market capitalisation of S$540 million.
The public offer will close at noon on Wednesday (Nov 24); trading in units of DHLT commences at 2pm on Friday (Nov 26).
"Historically, Daiwa House has been a company primarily focused on the Japanese domestic market," said Takeshi Fujita, chief executive officer of the manager of DHLT. Daiwa House's overseas businesses achieved net sales of S$3.8 billion in FY2020, but Fujita noted that this was only 7.4 per cent of total net sales of the group.
"Now, Daiwa House has recognised that they must expand to overseas markets for future growth. For the logistics business, Daiwa House has identified Asia, especially the Asean region, as the most promising market," he said in an interview with The Business Times.
Fujita added that DHI was setting up the Reit here "to accelerate" its property development and asset management business in Asia.
"As Daiwa House has been achieving fast growth in Japan through establishing capital recycling model by setting up the Reit and funds, Daiwa House intends to embark on asset management business, and try to build another capital recycling model in Singapore," he said. "Singapore is one of the global financial hubs, so I believe there will be big investor space."
However, he stressed that DHI does not see the Singapore-listed real estate investment trust (S-Reit) as an "exit fund".
"Rather than that, Daiwa House expects the S-Reit to be a key strategic infrastructure through which Daiwa House can accelerate development activities and asset management business in Asia, as well as expand investor base and access to the latest local information," Fujita added.
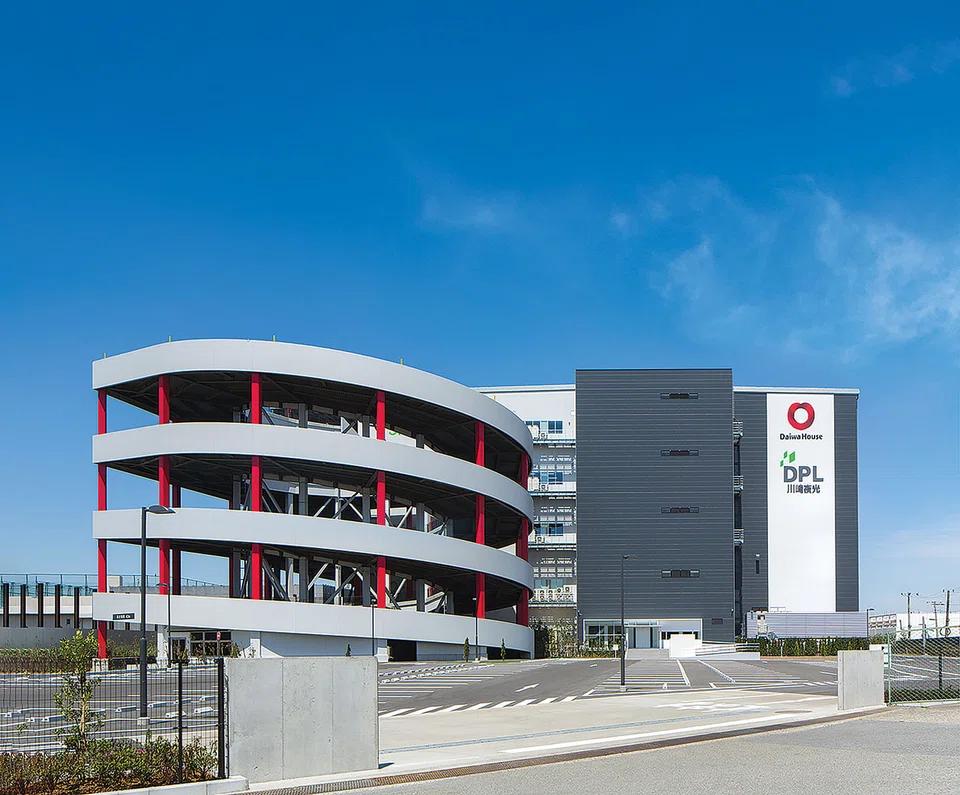
While the Reit manager said South-east Asia will feature prominently in its plans, DHLT will kick off with an initial portfolio of 14 logistics properties in Japan.
Under its potential acquisition pipeline, the Reit manager says it has right of first refusal (ROFR) from its sponsor to 6 completed properties in South-east Asia and another 5 properties in the region that are still under development.
The Reit manager highlighted that the sponsor has successfully developed logistics real estate in South-east Asia "in partnership with existing Japanese tenants who are looking to expand internationally".
For example, the DHML 1 property in Malaysia, which was completed in 2020 with a gross floor area (GFA) of 16,500 square metres (sq m), was developed as the result of a long-standing relationship between the sponsor and a major Japanese food wholesaler.
Similarly, several tenants in DMLP 1 in Indonesia are Japanese companies with an existing relationship with the sponsor.
In Japan, the Reit will have ROFR over a total acquisition pipeline of another 17 logistics properties - 5 completed and 12 under development.
This could mean a potential portfolio size of 42 assets in Japan, Vietnam, Indonesia and Malaysia, with a GFA of over 1.5 million sq m) - more than trebling the initial portfolio. The South-east Asian assets will account for just over a third of this potential pipeline portfolio by GFA.
The IPO portfolio, however, is surprisingly modest, considering the size of the sponsor.
As at end September, DHI is managing real estate funds with aggregate assets under management (AUM) of 1.66 trillion yen, including TSE-listed Daiwa House Reit Investment Corporation (DHR).
DHR holds a diversified portfolio of 227 properties in Japan, including 64 logistics facilities, with an AUM of 846.5 billion yen and a market capitalisation of 757.5 billion yen as at Sep 30.
In contrast, DHLT will purchase its initial portfolio at just S$840.5 million, which is an 11.8 per cent discount to the appraised value of the portfolio of around S$952.9 million.
The way Fujita describes it, however, the initial portfolio provides a good starting point for the Reit. He noted that the quality of the assets - including high occupancy rates, blue chip tenants and strategic locations - help to create a stable and balanced portfolio.
"Especially during the Covid period, we carefully monitored the market (and) finally ascertained that this is a good time to launch the new fund with pure logistics properties," Fujita said, adding that concerns over trading liquidity could fade as the Reit grows. "With the potential pipeline properties, we can let the fund grow gradually."
Without any in-built rental escalations in its tenancy agreements, the bulk of the Reit's growth will have to be inorganic in the form of acquisitions.
Immediately following its listing, DHLT will have a high aggregate leverage of 43.8 per cent, based on the purchase consideration of the 14 properties in the initial portfolio.
The Reit manager said it expects to repay a short-term consumption tax loan after the consumption tax is refunded by the end of June 2022. It noted that the Reit's leverage will then be lowered to 36.9 per cent, giving it a debt headroom of close to S$252 million.
In addition, the Reit manager said that there could be a revaluation gain at the end of 2021, as the IPO portfolio is being acquired at a significant discount to the appraised value.
Post the rebate of the consumption tax, and based on the appraised value of the properties instead of the purchase consideration, DHLT's aggregate leverage could possibly be lowered to around 33.1 per cent.
DHLT could also see an increase in its net asset value (NAV) per unit after a valuation in December, assuming the appraised value of the properties remain the same. On a pro forma basis, the Reit's NAV was estimated to be at S$0.76 as at end June.
The initial portfolio of 14 logistics properties, which have an average age of 3.7 years, sit on a land area of 420,393 sq m, with a total net lettable area (NLA) of 423,920 sq m.
As at Oct 1, the occupancy for the IPO portfolio was 96.3 per cent while the weighted average lease expiry by occupied NLA was 7.2 years as at June 30.
The Reit manager has forecasted distribution per unit (DPU) yield of 6.3 per cent for 2021, on an annualised basis, and projected DPU yield of 6.5 per cent for 2022.
"We believe this regional market for logistics assets is highly attractive, but have historically been overlooked by peers," Fujita said.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

What role can Japan play in Asean’s future?

Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet

As Malaysia’s chip goals morph into a multi-state model, are they outgrowing Penang?

